
Beginner's Guide to Hedera Hashgraph & HBAR


Key Takeaways
- 🔘 HBAR is Hedera's native cryptocurrency and utility token, used to pay network fees, support staking, and power activity across Hedera's core services.
- 🔘 Hedera is not a blockchain in the narrow sense. It is a public distributed ledger that uses hashgraph consensus, based on gossip about gossip and virtual voting.
- 🔘 Hedera's fixed total supply is 50 billion HBAR, and changing that cap would require unanimous Hedera Council consent.
- 🔘 HBAR's investment case depends on more than price speculation. Supply releases, fee demand, enterprise adoption, staking, liquidity, and regulatory access all matter.
Disclaimer
Nothing in this guide constitutes investment advice. HBAR is a volatile cryptocurrency, and its price can move independently of network fundamentals, adoption announcements, or fee activity. Supply figures, market data, transaction counts, and ecosystem metrics can vary by source depending on indexing methodology and timestamp. When evaluating Hedera activity, readers should cross-check claims against network data, market aggregators, and official Hedera resources where available.
Meet HBAR: Hedera's native cryptocurrency and utility token. It pays for network activity, supports staking, and connects users and developers to the services running on Hedera. One standalone feature of it is that unlike traditional cryptocurrencies which settle transactions through a blockchain, Hedera uses hashgraph consensus, which changes how the network reaches agreement, orders events, and finalizes transactions.
In this guide, we will define what HBAR is, explain how hashgraph works, review HBAR tokenomics, compare HBAR vs XRP, and walk through practical considerations for buying, storing, and evaluating the asset.
HBAR and the Hedera Network
Native Cryptocurrency and Utility Token

Although the introduction briefly outlined them, let’s define the key terms:
- HBAR — the native token and cryptocurrency of the network. It is the asset users hold, send, stake, and spend to pay for actions on Hedera.
- Hedera — the public distributed ledger itself. It is the network responsible for processing transactions, hosting applications, and maintaining the shared ledger.
- Hashgraph — the consensus algorithm Hedera uses. Its role is reaching agreement among nodes on transaction order and validity.
In short: HBAR is the fuel, Hedera is the vehicle, and hashgraph is the engine. ‘Hedera Hashgraph’ or ‘Hedera Network’ are sometimes used to refer to the network, which is the second in this group.
As a utility token, HBAR is required for everyday network actions, including:
- Sending HBAR or other tokens between accounts;
- Submitting a transaction to the network;
- Creating or updating an account on the ledger;
- Executing a smart contract call.
HBAR is necessary for interacting with Hedera at all. The more detailed breakdown of fees, staking, Smart Contracts, Token Service, and Consensus Service comes later in the HBAR Token Utility section.
Hedera as a Public Distributed Ledger
Hedera operates as a public distributed ledger, meaning there is no central gatekeeper deciding who can submit transactions or verify outcomes. Anyone can interact with the network and independently check publicly available data without requiring approval from a central authority.
This is the important distinction between a public ledger and a private or permissioned system. A private network can restrict access to approved participants; a public distributed ledger exposes its state and transaction history for open verification.
Distributed ledger technology (DLT), especially public, has a large overlap with blockchain. However, in the sections to follow we will explain why Hedera is a special case and DLT should not automatically equate to blockchain.
At a high level, Hedera is designed around fast confirmation and predictable costs. The exact figures depend on transaction type, network conditions, and fee mechanics, but the core model is straightforward: users pay HBAR to use network services, and the network orders those actions through hashgraph consensus.
“Ħ” in HBAR Crypto vs Physics
HBAR is the more common cryptocurrency ticker written in uppercase Latin letters but the official symbol according to the orignal Hedera documentation is ħ. This is also a symbol for the reduced Planck constant used in quantum physics.
One is a digital asset, the other is a fundamental physical constant, but the context should be more than enough to distinguish what the symbol represents. For all intents and purposes, it is safe to refer to hbars with the Latin-letter ticker symbol.
Hashgraph Technology
As we have established, Hedera does not use a blockchain in the traditional sense. It uses hashgraph, a consensus mechanism built on a different data structure from block-and-chain networks that you became familiar with while learning cryptocurrency basics.
This is the first major reason Hedera behaves differently from many crypto networks: it does not wait for blocks to be mined or appended in a line.
Hashgraph Consensus Mechanism

Hashgraph consensus relies on two core ideas: gossip about gossip and virtual voting. Together, they let nodes agree on transaction order without broadcasting extra voting rounds across the network.
Here is what the transaction flow in Hedera looks like:
- Event creation — A node receives a transaction and wraps it into an “event,” a data container that includes the transaction payload (what is being moved and how), a timestamp, and references to parent events.
- Gossip propagation — The node shares this event with another randomly chosen node. That node passes along not only the transaction but also what it already knows about other gossip it has received. This layered sharing of gossip history is what “gossip about gossip” means.
- Local DAG growth — As nodes keep syncing, each node builds its own local view of events and parent links, forming a directed acyclic graph (DAG) that reflects the history of who told whom what.
- Vote inference, or virtual voting — Because every node can see how information spread through the graph, it can mathematically infer how other nodes would have voted on transaction order without those votes ever being broadcast.
- Ordering — Using the inferred votes, nodes independently calculate a consensus order for transactions.
- Timestamps and finality — Each transaction receives a consensus timestamp, and once enough of the network's weighted history confirms the same ordering, that ordering is treated as final.
A consensus timestamp is the agreed-upon time value assigned to a transaction once the network has determined its position in the overall order. Finality means that ordering is settled. It is not the same as a probabilistic model where each new block merely increases confidence. Once consensus is reached on order, it does not get renegotiated.
Directed Acyclic Graph Structure
The structural difference is easier to picture visually. A traditional blockchain looks like a straight line of blocks, each one connected to the block before it. A hashgraph looks more like a web of events. Each event is a vertex created by a node, and each one references two parent events: the node's own prior event and the event received from the node it most recently gossiped with.
This creates the aforementioned growing directed acyclic graph, or DAG, rather than a single-file chain.
The “acyclic” part matters. It means the graph never loops back on itself; an event can never become its own ancestor. That absence of cycles creates a partial ordering among events, which later becomes the raw material for virtual voting and complete transaction ordering.
Every node maintains its own local view of the DAG based on the gossip it has received. There is no single master copy of the graph sitting on a central server. Consensus emerges because, once enough gossip has spread, nodes have similar enough local knowledge to independently infer the same result.
Asynchronous Byzantine Fault Tolerance
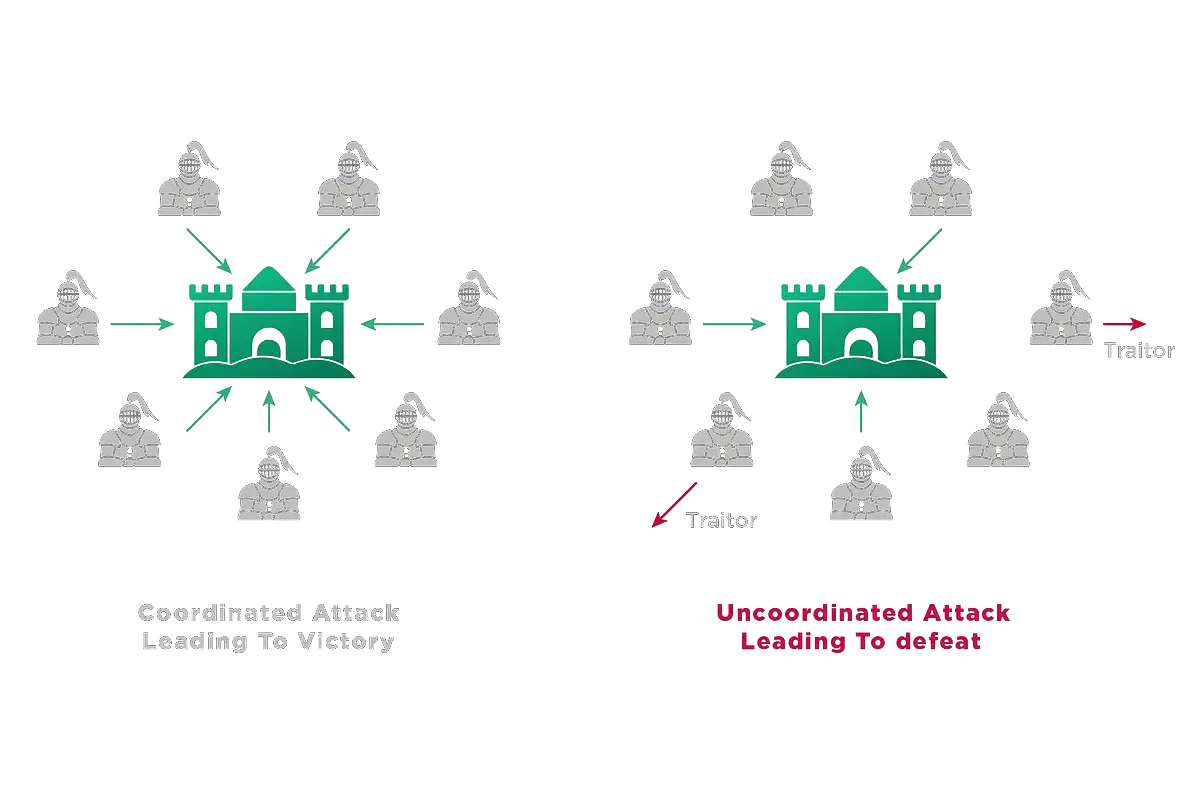
Hashgraph's consensus model is described as achieving asynchronous Byzantine fault tolerance, often shortened to aBFT. This term describes the type of reliability guarantee the consensus layer is designed to provide:
- Safety — nodes will not finalize conflicting transaction orders. Once ordering is decided, it stays decided.
- Liveness under asynchrony — the network can still make progress toward consensus even when message delivery times are unpredictable.
What aBFT does not guarantee:
- It does not prevent bugs or flaws in applications built on top of the network;
- It does not guarantee instant message propagation;
- It does not remove the need for sound governance or operational security.
Consider a temporary network partition or congested connection. Some nodes may see one slice of gossip while others see another. An aBFT-designed algorithm does not assume all messages arrive within a fixed time window. Once communication resumes and gossip catches up, nodes are designed to converge on a single agreed transaction order rather than permanently conflicting histories.
The guarantee being preserved here is agreement on ordering, not instant speed or guaranteed low cost.
Hashgraph vs Traditional Blockchain
| Dimension | Hashgraph (Hedera) | Regular Blockchain |
|---|---|---|
| Data structure | Directed acyclic graph of linked events | Linear chain of sequentially linked blocks |
| Message pattern | Gossip about gossip between randomly paired nodes | Broadcast mining or leader-based block proposals |
| Ordering mechanism | Order derived through virtual voting on local DAG knowledge | Order determined by on-chain confirmations added over time |
| Finality style | Deterministic-style consensus once ordering is decided | Probabilistic or common-knowledge-based confirmation that strengthens with more blocks |
| Resource emphasis | Emphasis on efficient bandwidth usage for gossip spread | Emphasis on computational or energy-intensive block production |
When Hedera is described as “not a blockchain,” it is still a distributed ledger. The data is simply organized and ordered differently.
HBAR Token Utility
Moving on to HBAR, it is not just a speculative asset. It is the token that makes actions on Hedera possible. Every transaction, smart contract execution, token operation, and node security mechanism depends on HBAR changing hands in some form.
Network Fees and Stable Pricing
At the most basic level, HBAR is what users spend to get something done on Hedera. Submitting a transaction, transferring tokens, calling a smart contract, or using any other network service requires a small transaction fee paid in HBAR.
- What you pay for: account creation, token transfers, smart contract calls, consensus message submission, and similar network actions.
- What “priced in USD, paid in HBAR” means: Hedera's fee schedule is denominated in USD, but users pay in HBAR. The required USD-equivalent amount is converted into HBAR based on the prevailing exchange rate at the time of the transaction.
- Why this is pitched as stable: the cost of using the network is anchored to a USD-denominated schedule, even though HBAR's own market price can fluctuate.
This distinction matters. You are not trying to guess how many HBAR a transaction will cost next month in isolation. You are paying a roughly consistent USD-denominated fee, converted into HBAR at that moment.
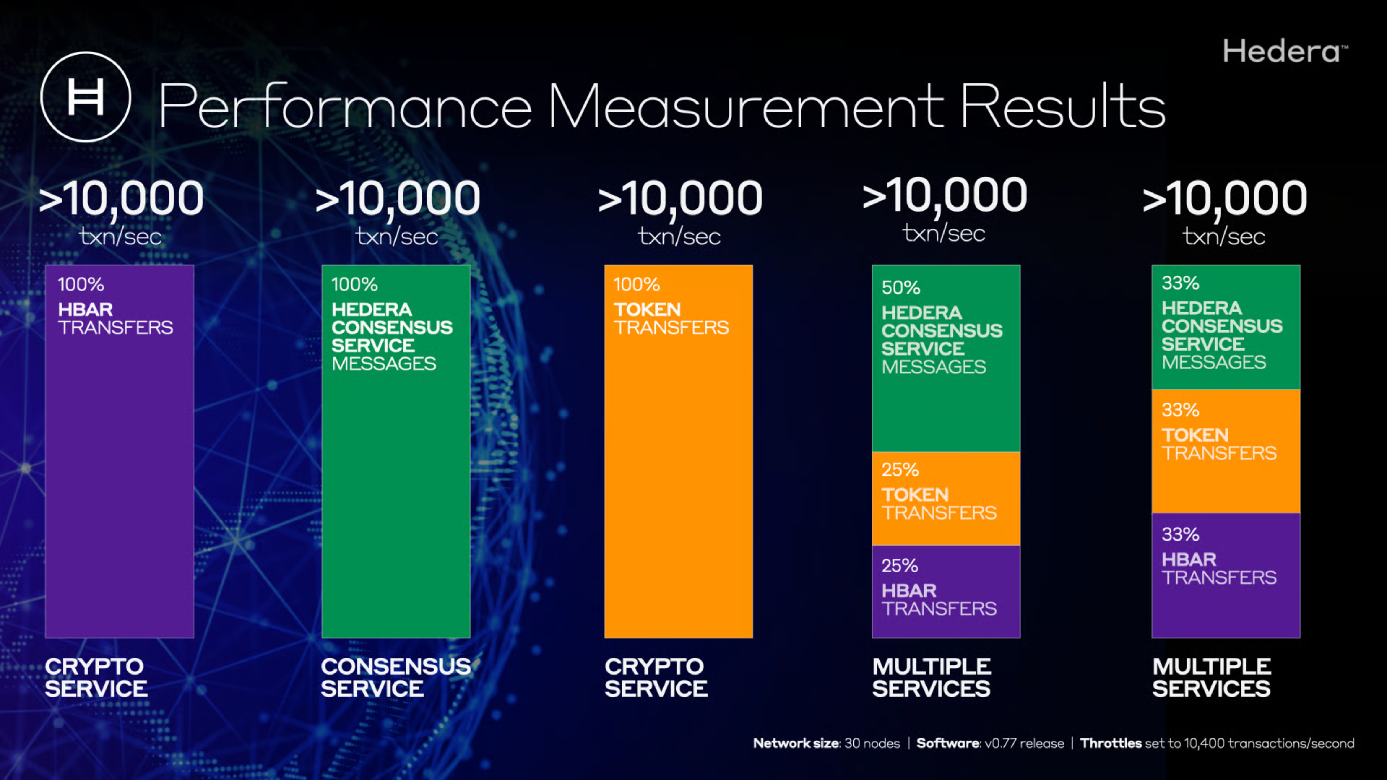
Typical network performance is described like this: Hedera's mainnet is throttled to a maximum of 10,000 transactions per second, a typical HBAR transaction fee is often cited around $0.0001, and transaction validation is generally expected to land in the 3–5 second range. However, actual fees and latency vary by transaction type, network conditions, and demand.
What changes your fee?
- Transaction type — a simple HBAR transfer costs less than a smart contract call (such as a token transfer).
- Payload or memo size — larger data attached to a transaction can incur a higher fee.
- Smart contract compute — more complex contract logic consumes more gas-equivalent resources.
- Network throttles and congestion — when the network operates near throughput limits, processing conditions can shift.
The useful takeaway is not that every fee will always be identical. It is that the network is designed to make fees more predictable than systems where the native asset price and fee market both move independently.
Staking and Network Security
HBAR also plays a role in securing the network through staking. Hedera's security model follows proof-of-stake principles: economic weight, rather than computational work, supports consensus participation.
There are two very different roles to understand:
- Proxy staking — a typical HBAR holder delegates staking weight to a node operator without running infrastructure.
- Running a node — an operator manages the server infrastructure that participates in consensus, which brings more technical responsibility, operational work, and risk.
For most holders, proxy staking is the practical entry point. Running a node is a separate infrastructure commitment.
The security logic is simple. More HBAR staked across a broad set of nodes increases economic alignment between token holders and network health. It can also reduce concentration if staking weight is distributed widely enough. None of this changes the aBFT mechanics under the hood; it connects HBAR holders economically to the integrity of the network. Gives them a stake in it, if you will.
Smart Contracts, Token Service, and Consensus Service
Beyond fees and staking, HBAR is also what users spend to access more of Hedera's core services.
- Smart Contracts — Enables EVM-compatible execution of custom logic, the same programming model used across much of the Ethereum ecosystem. A representative use case is running a DeFi protocol or dApp logic directly on Hedera. Users pay HBAR for deploying and executing contract calls, with gas-equivalent costs scaling based on computational complexity.
- Token Service (HTS) — Enables native creation and management of fungible tokens, NFTs, and stablecoins without writing full smart contract code. A representative use case is a business issuing a loyalty token or an NFT collection directly through the service. Users pay HBAR for token creation, minting, transfers, and management operations.
- Consensus Service (HCS) — Enables ordering and timestamping of arbitrary messages, giving applications a verifiable, tamper-evident sequence of events. A representative use case is logging supply chain checkpoints or creating an audit trail for a multi-party workflow. Users pay HBAR for each message submitted for ordering and timestamping.
Not every use case needs a smart contract. HTS and HCS exist precisely to handle common patterns more efficiently than full contract logic.
HBAR Supply, Market Data, and Price Drivers
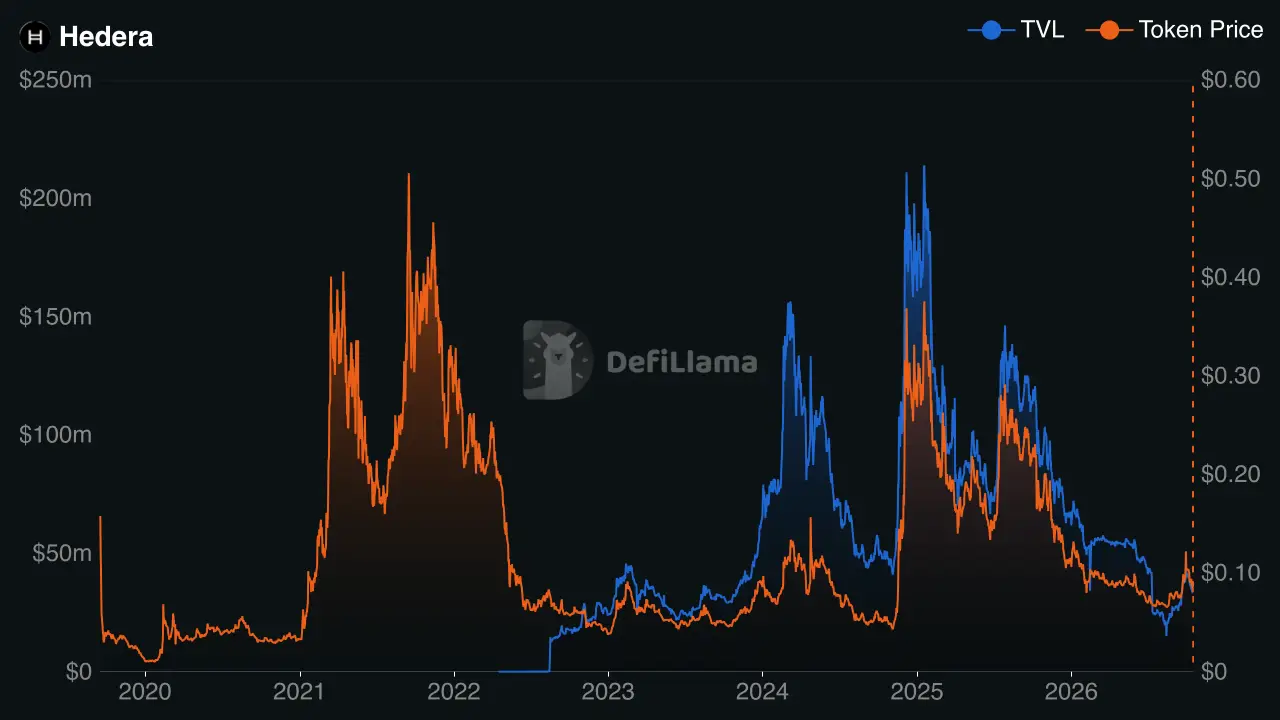
Total Supply and Circulating Supply
Before looking at an HBAR price chart, it helps to understand where the numbers come from. Hedera has a fixed total supply of 50 billion HBAR, and changing that fixed supply would require unanimous Hedera Council consent — a deliberately high bar that makes the cap effectively immovable under normal circumstances.
There are three separate supply concepts to keep in view:
- Total supply — the fixed, hard-capped ceiling of 50 billion HBAR that will ever exist.
Why it matters: it removes the risk of arbitrary inflation but also sets the denominator against which full dilution is measured. - Circulating supply — the portion of HBAR that is tradable and held by the public right now, excluding tokens still locked or unreleased. At the time of writing, it is 43,997,753,476.06 HBAR according to CoinMarketCap.
Why it matters: this is the float that interacts with buy and sell pressure on exchanges. - Treasury, locked, and allocated supply — HBAR set aside for ecosystem grants, Council allocations, or scheduled releases that have not yet entered circulation.
Why it matters: this represents potential future supply overhang.
When reviewing any supply schedule or unlock calendar, do not just note the date. Check which category the release belongs to, whether the timing is firm or projected, and whether the source is citing on-chain data or a modeled forecast.
Mind that circulating supply can rise even if HBAR's price does not move. Because market capitalization equals price multiplied by circulating supply, market cap can shift purely from a supply-side release rather than from new demand. Treat supply and price as two separate variables; this is central to HBAR's tokenomics.
Live Metrics and Ecosystem Trackers
Reading Hedera's ecosystem data well means knowing not only where to look, but what each number implies when placed next to the others.
A blockchain explorer is a web interface that lets users look up individual transactions, accounts, and smart contract activity in human-readable form. Another key concept, a mirror node is the underlying infrastructure that explorers and applications query. It mirrors network state and history without participating in consensus itself.
For practical tracking, separate tools into two categories:
- Official network surfaces — explorers and mirror nodes that reflect raw, verifiable network data.
- Market aggregators — platforms that compile price, market capitalization, and volume data from exchanges.
The first category tells you what is happening on the network. The second tells you how the market is pricing that activity.
Use this metric map to complete the picture step by step:
- The current market price per HBAR. On its own, HBAR price says very little about network health.
- Market capitalization — price multiplied by circulating supply. If market cap rises while circulating supply is flat, the move is likely price-driven rather than supply-driven.
- Circulating supply — the tradable float at a given moment. If circulating supply rises while price stays flat, new tokens are being absorbed without obvious price appreciation.
- 24-hour volume/liquidity — how much HBAR is trading in a day. A price move on low volume may be less durable than one supported by deep liquidity.
- Transaction count — how many transactions the network is processing. If transaction count rises while fee revenue stays flat, the activity may be low-fee or subsidized.
- Fee revenue — the aggregate HBAR spent on network fees over a period. If fee revenue rises while active accounts stay flat, existing users may simply be transacting more.
- Active accounts — accounts interacting with the network. If active accounts rise while transaction count stays flat, this may point to testing rather than sustained use.
- Developer activity — code commits, SDK usage, or new project launches. If developer activity rises while on-chain metrics stay flat, building may be ahead of adoption.
Adoption, Demand, and Fee Revenue
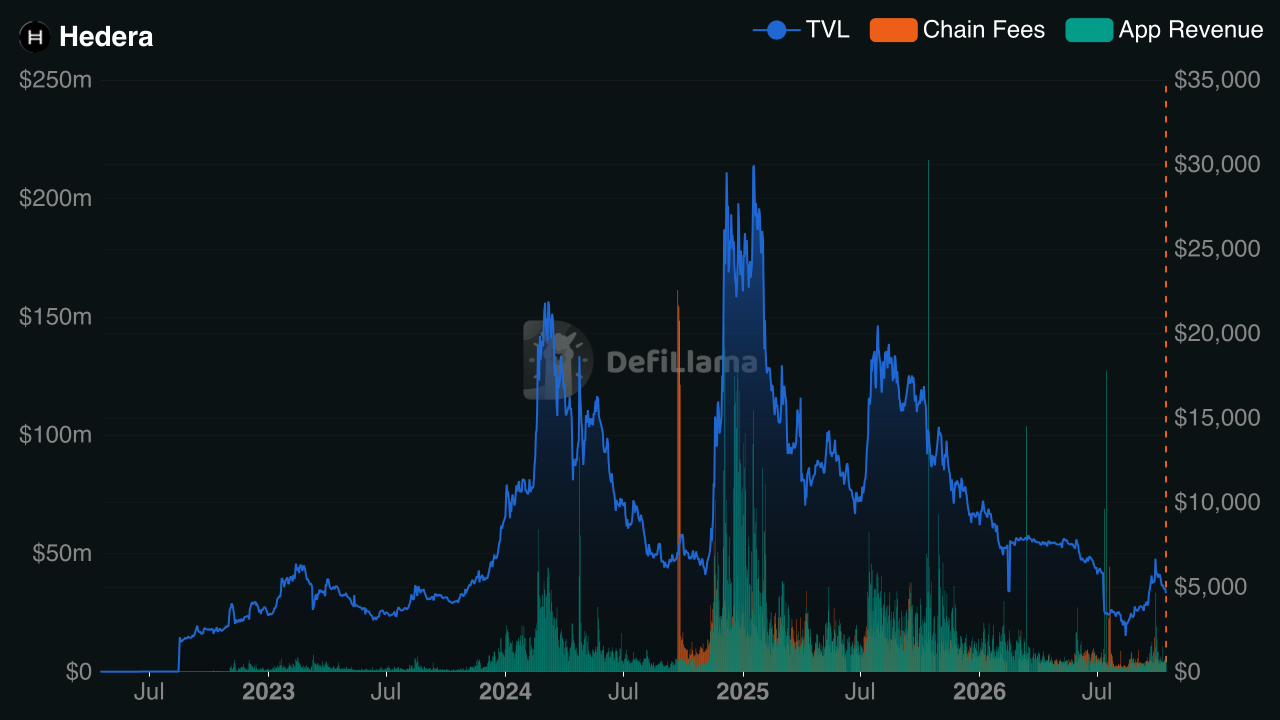
Despite what many crypto users would very much like, adoption does not translate into price through a single direct line. It works through several mechanisms, each with its own assumptions.
- Fee demand — every transaction, smart contract call, or token operation requires HBAR. As real usage grows, more HBAR is needed to interact with the network.
- Staking and holding behavior — HBAR committed to proxy staking or held long term is not actively trading, reducing liquid float.
- Narrative and enterprise credibility effects — partnerships, pilots, and Council-level endorsements can influence how marginal buyers perceive the network.
This is where the mechanical channel and the narrative channel separate. Fee demand is mechanical: usage requires HBAR. Enterprise credibility is narrative: it can influence attention and market perception. Both can matter, but they are not the same thing.
What can break the thesis:
- Demand not translating to token demand — if usage grows but fees remain negligible or subsidized, the fee-demand mechanism weakens.
- Supply releases increasing float — scheduled unlocks or treasury allocations can expand circulating supply faster than demand absorbs it.
- Broader crypto risk-off cycles — HBAR still trades inside the wider crypto market, where liquidity contractions can suppress price regardless of project-specific fundamentals.
None of these mechanisms guarantee price appreciation. They describe how adoption could pressure HBAR's market dynamics, not that it necessarily will.
Governance and Ecosystem Adoption
Hedera Governing Council
Hedera is governed by a formal governing body: the Hedera Governing Council. This differs from networks where informal community consensus or a single founding company drives protocol decisions. Some of the names currently present in the Council that you might recognize are Dell, Deutsche Telekom, LG, Google, IBM, and Mondelēz.
The Council governs network-level policy. That includes node operating standards, treasury-level allocations, protocol upgrades, and the overall direction of the codebase. Individual token holders and app developers do not directly control these decisions in the same way they might in token-vote governance models.
This creates an important split:
- Protocol-level authority is centralized among Council members;
- Transaction validation and ordering are handled through hashgraph consensus across nodes.
Hedera presents this model as credible long-term stewardship for enterprise users that need predictable rules. The trade-off is obvious: structured governance can provide stability, but it is less open-ended than pure tokenholder governance.
The Council's composition is deliberately constrained: membership is capped at up to 39 organizations across up to 11 industries, a structure Hedera frames around industry diversity rather than concentration in one sector. This design appears to reduce single-sector capture risk. At the same time, coordinating up to 39 independent organizations can slow decision-making compared with a small founding team or centralized operator.
This is important to token holders because Council-level decisions can affect network economics. Fee schedule parameters, operational policies, treasury-held HBAR allocations, and release practices all influence the environment in which HBAR circulates.
Enterprise Partnerships
Not limited to Council seats, enterprise partnership announcements are common across crypto. Hedera is no exception. The issue is that not all partnership claims carry the same analytical weight.

Before treating a partnership as proof of real adoption, run it through this filter:
- Production usage vs. pilot — Is the organization running workloads on Hedera mainnet, or is this a proof-of-concept that may never reach production?
- Which Hedera service is involved — Is the partnership using Smart Contracts, Token Service (HTS), or Consensus Service (HCS)?
- What on-ledger activity should be observable — Should there be recurring HCS message submissions, HTS token operations, or smart contract calls?
A claim that cannot be mapped to at least one of these categories is difficult to verify.
The common gap should be named plainly: enterprise interest does not automatically equal sustained on-chain activity or meaningful fee demand. Pilots can stall. Some integrations keep most workflow off-ledger and only anchor occasional checkpoints on Hedera. Even successful integrations can generate sporadic usage if the underlying business process itself does not require constant on-chain interaction.
In other words, the announcement is not the adoption. The observable activity is.
Real-World Use Cases
Hedera's services map to several real-world workflows. The useful question is not only “could this work?” but “what would success look like on-chain?”
- Supply chain checkpoint logging (HCS) — A manufacturer or logistics provider submits messages marking shipment checkpoints such as origin scan, customs clearance, and warehouse receipt. A public ledger provides independent, tamper-evident timestamping. Success would look like recurring message submissions tied to actual checkpoint events.
- Tokenized loyalty or rewards programs (HTS) — A retailer or platform issues a loyalty token or NFT-based rewards credential through Token Service. A public ledger makes issuance and transfers auditable by participants. Success would look like ongoing minting and transfer operations tied to customer activity.
- DeFi lending or exchange protocols (Smart Contracts) — A decentralized finance application deploys EVM-compatible contract logic on Hedera to handle lending, swaps, or collateral management. Success would look like regular contract calls corresponding to real user transactions.
- Multi-party audit trails for regulated industries (HCS) — Healthcare, insurance, or financial services organizations timestamp document hashes or workflow milestones across multiple parties. Success would look like sustained message submissions correlated with business events.
- Asset tokenization for securities or real-world assets (HTS + Smart Contracts) — An issuer tokenizes a real-world asset, such as a bond or fund share, using HTS for the token and smart contract logic for compliance rules or transfer restrictions. Success would look like recurring token transfers and management operations, not a one-time issuance.
If a claim cannot be connected to observable accounts, contracts, messages, or token operations, it should be treated as narrative until proven otherwise.
HBAR vs XRP
| Dimension | Hedera (HBAR) | XRP Ledger (XRP) |
|---|---|---|
| Ledger architecture | Hashgraph — a directed acyclic graph (DAG) of gossiped events | XRPL — a blockchain network using its own purpose-built ledger design |
| Consensus approach | Gossip-about-gossip with virtual voting among weighted nodes | Validator-based agreement among a trusted set of validator nodes who confirm ledger versions |
| Finality/confirmation style | Deterministic-style ordering once consensus on an event's position is reached | Validators converge on a single, agreed ledger state close to transaction submission, with confirmation treated as settled rather than growing more certain over time |
| Smart-contract model | EVM-compatible execution environment (Smart Contracts), plus native services (HTS, HCS) that don't require contract code at all | No general-purpose EVM layer natively; XRPL instead offers native primitives, including built-in decentralized exchange, escrow, and payment channels |
| Token supply model | Fixed cap, changeable only with unanimous Hedera Council consent | Fixed total supply set at issuance, held and released over time by Ripple, the company most closely associated with the ledger's ongoing development |
| Primary usage focus | General-purpose network services — smart contracts, tokenization, and ordered messaging for applications | Payments, cross-border liquidity, and settlement-oriented use cases |
| Typical fee framing | Fees are pitched around predictable, USD-anchored budgeting for network actions rather than a fixed HBAR amount | Fees are framed around being low-cost enough to support high-volume payment and remittance activity, without a USD-anchored schedule |
| Governance posture | Council-led governance — a defined, capped set of enterprise organizations holding protocol-level authority | More validator- and ecosystem-driven governance, with decisions shaped by a broader set of participants rather than a single capped council structure |
Technology Differences
Both networks get referred to as blockchain network infrastructure in the broad sense that they are public distributed ledgers. However, they organize and confirm data in structurally different ways.
Hedera's hashgraph DAG and XRPL's blockchain-style ledger represent two approaches to the same coordination problem: getting a decentralized set of validator node participants to agree on transaction order and achieve finality without a central authority.
“Not a blockchain” does not mean “not comparable.” Hashgraph is not block-and-chain architecture, but Hedera and XRPL are still comparable as public distributed ledgers solving ordering, validation, and interoperability problems.
EVM compatibility is not the same as identical tooling. Hedera's Smart Contract service is EVM-compatible at the execution-environment level. That does not mean its consensus mechanics are the same as EVM chains. XRPL, by contrast, does not rely on EVM compatibility; it offers native primitives like a built-in DEX and escrow functionality.
Token Utility Differences
At a category level, HBAR and XRP serve different roles.
HBAR utility:
- Paying for network services;
- Participating in staking and network security;
- Powering app-level actions built on Hedera's core services.
XRP utility:
- Supporting payments, liquidity, and cross-border settlement flows;
- Serving as the native fee token for transactions on XRPL;
- Providing broader ecosystem utility within payment-focused applications and infrastructure.
For holders, this means the demand drivers differ. HBAR demand tends to track developer and enterprise service usage. XRP demand tends to track payment volume and liquidity needs. This does not imply one asset should outperform the other; it simply identifies different sources of utility.
Network Strategy Differences
The networks are also pursuing adoption through different strategies.
- Hedera leans on enterprise governance and a service-layer approach: Smart Contracts, HTS, and HCS. It positions itself as infrastructure for businesses that want programmable, auditable application services with Council-backed stewardship.
- XRP and XRPL lean on a payments-centric narrative, emphasizing liquidity, settlement speed, and cross-border value movement.
Buying, Storage, and Investment Considerations
Exchange Availability
Before you buy HBAR, evaluate the venue rather than relying on name recognition. Exchange availability, fees, liquidity, and withdrawal policies change too often for a static ranking to be useful, but the criteria below remain relevant.
- Order types and liquidity — Where possible, check the bid-ask spread and recent trading volume for the HBAR pair you intend to use.
- Fiat on-ramps and settlement time — Confirm whether the venue accepts bank transfers, cards, or other fiat funding methods, and how long funds take to settle.
- Withdrawal availability — Make sure HBAR withdrawals are enabled before depositing meaningful funds. Alternatively, consider non-custodial platforms like ChangeHero that deliver straight to the address you specified.
- Fee structure — Separate trading fees from withdrawal fees; they affect cost basis differently.
- Jurisdiction and KYC constraints — HBAR trading pairs and withdrawal rights can vary by country.
Wallet Options and Custody
Even before you actually get HBAR, the next decision is custody. This splits into two main models: custodial and non-custodial.
| Custodial Wallet | Non-Custodial Wallet | |
|---|---|---|
| Key control | Exchange or platform holds your private keys | You hold your own private keys |
| Recovery model | Platform-managed account recovery | Self-managed recovery via seed phrase or key backup |
| Typical failure mode | Account lock or withdrawal freeze | Permanent loss if backup is lost |
| Best suited for | Active trading | Long-term holding and third-party risk reduction |
Beyond that basic split, storage falls into three practical postures:
- Leaving funds on an exchange — Convenient for trading, but you do not control the keys.
- Self-custody in a software wallet — Direct control through your own wallet address, but recovery responsibility shifts entirely to you.
- Cold storage — Stronger isolation from online threats, but every transaction requires more friction.
No matter the chosen custody arrangement, address hygiene is something you should not ignore:
- Send a small test amount before moving your full balance.
- Confirm the receiving address format.
- Double-check copy/paste integrity.
- Wait for the deposit to credit before sending the remainder.
This sounds basic because it is. It is also where many avoidable losses happen. Seed phrase security is also something that you should look into, regardless of your choices about HBAR in particular.
Risk Factors
HBAR investment risk is not one thing. It is an entire set of separate risk categories. See the non-exhaustive list of examples below to get an idea of what you might be getting into.
Market risks
- Crypto volatility can produce sharp drawdowns independent of Hedera-specific news.
- Liquidity can thin during risk-off periods, widening spreads and worsening execution.
Token-supply and treasury dynamics
- Scheduled releases from treasury or ecosystem allocations can expand circulating supply.
- The timing and pace of releases may add uncertainty to supply-side modeling.
Technology and operational risks
- Network outages or degraded performance can disrupt transactions.
- Wallet or exchange-side issues can temporarily block access to funds.
Adoption risks
- Enterprise pilots do not automatically become sustained, fee-generating activity.
- Narrative-driven valuation is more fragile than valuation backed by recurring usage.
Regulatory risks
- HBAR's legal classification and trading availability can differ by jurisdiction.
- Exchange delisting or access restrictions can affect how and where investors trade or hold the asset.
To manage the risks, size your position according to the category you are least prepared to tolerate. If regulatory uncertainty worries you most, that should shape your exposure more than optimism about enterprise adoption.
Portfolio mechanics also matter. A high-volatility asset like HBAR can dominate day-to-day portfolio movement even if the allocation looks modest on paper. Rebalancing discipline helps prevent a volatile holding from silently becoming a larger risk than originally intended.
Regulatory and ETF Outlook
Regulatory developments change the access pathway to HBAR more than they change the token's underlying mechanics. The clearest example is the arrival of ETF products.
Canary's HBR HBAR exchange-traded fund began trading on Nasdaq on October 28, 2025, giving investors a way to gain HBAR price exposure through a standard brokerage account rather than a crypto exchange.
This changes how someone can gain exposure, not what HBAR is. An ETF can improve visibility and accessibility for traditional finance investors, but it does not provide direct token ownership. ETF shares cannot be moved to a wallet address, used to pay fees, or used for proxy staking.
Long story short, ETF exposure generally does not confer on-network usage rights. You cannot use ETF shares to interact with Smart Contracts, Token Service, Consensus Service, or any other Hedera network function that requires HBAR directly.
Conclusion
HBAR pays transaction fees, supports staking, and ties the economics of the Hedera ecosystem to the security of a public distributed ledger built on Hashgraph consensus rather than a traditional blockchain. Although the network has been built for institutions first, it does not mean that anyone else cannot avail of the many benefits of this technology and ecosystem.
Make sure to check out more similar guides and articles from ChangeHero’s blog! If you want updates daily, why not sign up for updates on our X, Facebook, and Telegram?
Frequently Asked Questions
What is HBAR used for?
HBAR fuels activity on the Hedera network. It is used to pay transaction fees, participate in staking and network security, and access services such as Smart Contracts, Token Service, and Consensus Service. In practical terms, HBAR is the asset required to interact with Hedera's public distributed ledger.
Is Hedera Hashgraph a blockchain?
Hedera Hashgraph is not a blockchain in the narrow sense of blocks linked sequentially one after another. It is still a public distributed ledger, but it uses a directed acyclic graph and hashgraph consensus instead of block-and-chain architecture.
How does Hedera Hashgraph work?
Hedera's nodes use gossip about gossip to spread transaction history and virtual voting to infer consensus without broadcasting separate votes. Events form a DAG, and nodes use that structure to agree on transaction order and assign consensus timestamps.
How do you buy and store HBAR?
You buy HBAR through a cryptocurrency exchange that lists the token, then decide whether to leave it with a custodian or move it to a non-custodial wallet. Custodial storage is more convenient for trading; self-custody gives you direct control but makes you responsible for key backup and recovery.
Can HBAR reach $10?
A $10 HBAR price would require a very large implied market capitalization, especially when measured against the fixed total supply of 50 billion HBAR. The scenario depends on circulating supply, fee demand, enterprise adoption, liquidity, and broader crypto market conditions. It is better treated as a valuation stress test than a realistic Hedera (HBAR) price prediction.
What is the difference between HBAR and XRP?
HBAR powers Hedera's general-purpose network services, including smart contracts, tokenization, and ordered messaging. XRP is more closely associated with payments, cross-border liquidity, and settlement use cases on the XRP Ledger. They are both public distributed ledger assets, but their architecture, utility, and governance models differ.