
What is Liquid Staking? Beginner's Guide


Key Takeaways
- 💧 Liquid staking lets users stake proof-of-stake assets while receiving a transferable Liquid Staking Token (LST) that represents a claim on the underlying stake plus accrued rewards;
- 💧 The core trade-off is liquidity and DeFi composability in exchange for additional protocol, validator, market, custody, and regulatory risks;
- 💧 LST rewards can appear through rebasing balances or rising exchange rates, but the economic anchor remains the same: how much underlying asset each LST represents;
- 💧 Exiting a liquid staking position usually means choosing between selling the LST on the open market or redeeming it through the protocol, and each path has different timing and pricing implications.
Disclaimer
Liquid staking involves smart contract risk, validator risk, market liquidity risk, and custody or regulatory exposure depending on the provider used. Nothing in this article constitutes investment advice. Always verify protocol documentation, fee schedules, audits, validator sets, and redemption rules before depositing funds. When possible, use on-chain data as the primary source of truth.
Staking typically locks up your capital, but liquid staking solves that tension by keeping your exposure to staking rewards while restoring liquidity through a tokenized claim. In practice, you can stake ETH and receive an LST like stETH in return. This token represents a receipt, or claim, on your originally staked asset plus the rewards it accrues over time. The mental model this guide will walk you through is straightforward: you deposit an asset, receive a receipt token, and that token continues to reflect both ongoing rewards and the flexibility to use it elsewhere in DeFi on a blockchain.
Liquid Staking Process
Proof-of-Stake Deposits

To understand liquid staking, trace where the funds go and who performs each part of the work. The typical sequence looks like this:
- User deposits an asset, for example ETH, into a liquid staking protocol's smart contract or pool.
- The protocol aggregates deposits from many users into a shared pool rather than requiring each person to stake alone.
- The pool delegates the pooled capital to a validator set, the group of validators responsible for proposing and attesting blocks under proof-of-stake.
- Validators perform consensus duties — proposing blocks, attesting, and staying online — using the delegated stake as their economic backing.
- Rewards accrue on the staked capital as validators fulfill their duties correctly and stay in good standing.
- The user holds a claim — a receipt token — that represents their proportional share of the pooled stake and its accumulated rewards.
Naturally, staking through an intermediary like a liquid staking protocol differs from running a validator directly. The protocol handles delegation, validator selection, and operational uptime on the user's behalf. Running a validator, for reference, means managing your own infrastructure, keys, and validator duties.
Pooled staking exists largely because solo staking has a real barrier to entry. On Ethereum, running a solo validator requires 32 ETH as a minimum deposit — a threshold many users cannot or do not want to meet on their own. Liquid staking protocols solve this by aggregating smaller deposits from many users before delegating the combined total to the validator set, letting users participate regardless of how much ETH they hold.
Liquid Staking Tokens
The second crucial component of this arrangement is also called LST, a tokenized claim on a share of pooled staked assets plus the rewards that share accumulates over time, net of protocol and validator fees. What you actually see in your wallet depends on which accounting style the protocol uses.
Some LSTs use a rebasing model, where your token balance itself increases periodically to reflect earned rewards. You hold more tokens over time, while each token's underlying value stays pegged near 1:1 with the staked asset. Others use an exchange-rate model, where your token balance stays fixed, but the token's redeemable value against the underlying asset rises as rewards accrue. Either way, these are recognition cues visible to users; the underlying mechanics of how rewards are calculated and distributed are covered in more depth in the later sections.
LSTs follow a clear mint-and-redeem lifecycle. They are minted at the moment of deposit, when the protocol issues the receipt token representing your claim. They are burned at the moment of redemption, when you initiate an unstake and exchange the LST back for the underlying asset. Upon redemption, you are entitled to receive the underlying asset plus the rewards earned during the holding period, net of fees.
Redemption is not always instantaneous. Depending on the protocol, it can involve a queue or an unbonding period — the time validators need to formally exit and release the staked funds back into circulation.
Trading and DeFi Use

Because by design, the LST is a liquid, transferable token, it can be put to work while the underlying stake continues earning rewards:
- Sell or trade on spot markets to regain liquidity immediately, exchanging the LST for another asset. This requires an active LST market pair on an exchange.
- Supply as collateral in lending/borrowing protocols, letting you borrow against your staked position. This requires oracle support to price the LST accurately.
- Provide liquidity in AMMs, pairing the LST with another asset in a pool to earn trading fees. This requires sufficient depth in an LST/asset liquidity pool.
- Deploy in yield strategies via vaults or aggregators, which route the LST into additional yield-generating positions automatically. This requires integration between the vault and the LST's underlying protocol.
- Use as margin or collateral in derivatives platforms, where supported. This requires defined collateral and liquidation parameters set by the platform.
When it is time to exit a liquid staking position, users generally have two procedural paths. The first is redeeming through the protocol — the unstake path — where the LST is burned and the underlying asset is returned, subject to any queue or unbonding period. The second is selling the LST on the open market, a secondary-market exit that swaps the token for another asset immediately, without waiting on the protocol's redemption process.
Liquid Staking Rewards
Validator Rewards and Protocol Fees
The convenience is obvious but what about the price of it? Liquid staking yield, unlike a straightforward staking APY, does not arrive as a single number. It is the output of a layered process, and understanding each layer is what separates a marketing figure from the return you actually see. The gross-to-net flow works like this:
- Network staking issuance, plus priority fees and MEV where applicable — this is the base reward pool generated by the protocol's consensus layer as validators propose and attest blocks. On Ethereum, this includes base issuance plus any priority fees and MEV captured during block production.
- Validator/operator commission is deducted — the node operators running the validators take a cut for their infrastructure and operational work. This is the validator commission layer.
- Protocol fee is deducted — the liquid staking protocol, or its governing DAO, takes its own cut, separate from what operators receive.
- Net rewards are reflected to LST holders — what remains after both deductions is the staking reward that actually accrues to your position, whether through a growing balance or a rising exchange rate.
The practical takeaway is simple: always look for net yield after all these layers are accounted for, not only the headline APY a protocol advertises. Gross issuance numbers can look attractive, while the net figure — after commission and protocol fees — tells a different story.
In case you’d like to clear the labels up, protocol fee is taken by the protocol or its DAO, typically as a percentage of rewards generated, not principal. Node operator/validator commission is paid to the operators running validator infrastructure, compensating them for uptime and correct performance. Some protocols layer extra incentives on top to attract or retain high-performing operators, which can further affect the net split.
Needless to say, fee structures vary meaningfully across providers: Lido charges a 10% platform fee, Rocket Pool's fees range from 5% to 20% depending on node operator and configuration, and ANKR's fees fall between 2% and 10%. These ranges illustrate why net returns can diverge even when gross staking rewards are similar — the fee layer alone can swing your realized yield by several percentage points.
Even fee labels are not standardized across providers. What one protocol calls a "protocol fee" another might bundle into "operator commission". Always verify how each provider's terminology maps to the actual deduction before comparing advertised yields.
Rebasing and Exchange-Rate Models
Once you know where rewards come from, the next question is how they show up in your wallet. That depends entirely on which accounting model your LST uses. As mentioned above, it can be grounded in rebasing or exchange rate.
Each model has a distinct practical implication for portfolio tracking, tax reporting, and accounting tools. With a rebasing token, tracking software needs to monitor the balance field because that is what changes. Depending on jurisdiction, each rebase event could be treated as a separate taxable accrual. With an exchange-rate model, the balance field stays static, so tools instead need to track the conversion rate, or exchange rate, to compute gains. This often simplifies transaction-level accounting because there are fewer discrete balance-change events to log.
Despite these mechanical differences, the underlying economic exposure is identical. The mechanism is just a different lens on the same reward stream. To compare value across models on equal footing, use one invariant: underlying-per-LST, meaning how much of the underlying staked asset each LST unit is worth right now.
For a rebasing token, your balance grows while underlying-per-LST stays close to 1. For an exchange-rate token, your balance is fixed while underlying-per-LST climbs. Plug either into the formula above, and you land on the same economic value — the accounting style changes what you see, not what you actually hold.
APY, Compounding, and Net Returns
With the reward flow and accounting model covered, the last piece is interpreting the yield figure itself. This is where APR and annual percentage yield (APY) get conflated, often to the detriment of the user comparing options.
APR is a simple annualized rate. It does not account for compounding, so it understates returns when rewards are reinvested or credited periodically. APY, by contrast, incorporates compounding effects or periodic reward crediting, giving a more accurate picture of what a position actually earns over a year if rewards continue to compound at the stated rate.
For liquid staking specifically, "true APY" should always be interpreted as net of protocol and validator fees — the layered deductions covered earlier. Whenever you see an APY figure, three things should be stated alongside it: the time window it is measured over, whether it is net or gross of fees, and the specific asset it applies to. Without all three, the number is close to meaningless for comparison purposes.

Even if a protocol performs exactly as advertised and delivers its stated net yield, your realized return can still differ because of the price you paid or received for the LST on the secondary market. Buying an LST at a premium to its underlying-per-LST value, or selling it at a discount, changes your realized return independent of the staking rewards themselves. This is pure return math, not a reflection of protocol performance or de-pegging risk.
Suppose you deposit 1.0 unit of the underlying asset and the protocol delivers a stated net annual yield of 4%. After one year, your position — measured via underlying-per-LST — is worth 1.04. If you simply redeem through the protocol, you realize that full 4% annualized return.
But suppose instead you exit by selling the LST on the open market, and at that moment the LST is trading at a 1% discount to its underlying-per-LST value. Your realized proceeds are now 1.04 × 0.99 = 1.0296 — a realized annualized return of roughly 2.96%, not the 4% the protocol reported. The staking mechanism performed exactly as promised; the gap came entirely from where and how you exited.
Liquid Staking Benefits
Liquidity During Staking
The liquidity that liquid staking provides comes primarily from one mechanism: the ability to exit via secondary markets by selling or swapping the LST, not from any change to the underlying network's unbonding rules. Native unstaking still takes however long the protocol's unbonding period requires. Liquid staking does not shorten that.
What it adds is a second, parallel exit path. For the market-exit path to actually be meaningful rather than theoretical, a few conditions need to hold:
- Deep spot liquidity for the LST trading pair or pairs, so a sale does not struggle to find a counterparty.
- Reliable pricing/oracle feeds for the LST, so integrations and venues can value it accurately.
- Sufficient trading venues, on-chain and off-chain, so users are not dependent on a single pool or exchange.
These are the structural prerequisites for liquidity to function as advertised. The specific failure modes when they break down — de-pegs, slippage, thin books — belong to the discussion coming up later in this guide.
DeFi Composability
It helps to separate two distinct sources of value on an LST position. Primary yield is the staking reward accruing to the position itself, the same reward stream covered in the Rewards section. Secondary utility is everything you can additionally do with the token inside decentralized finance while that primary yield keeps accruing underneath.

Composability is what makes the second layer possible, and it tends to follow a handful of recurring patterns:
- Collateral in lending markets — the LST backs a loan, letting you borrow against staked capital without unstaking it.
- Margin or borrowing power on platforms that support it, where the LST's value contributes to what you can leverage.
- Liquidity provision in AMMs — pairing the LST with another asset to earn trading fees on top of staking rewards.
- Yield vault strategies — routing the LST into an aggregator or vault that layers additional yield-generating positions on top.
- Basis trades and arbitrage setups — exploiting spreads between the LST's market price and its underlying-per-LST value.
- Productive collateral in structured products — using the LST as the collateral leg of a packaged strategy that still earns its base staking yield.
None of this composability is automatic. It is gated by whatever the receiving protocol decides to support: collateral parameters, oracle feeds, and risk limits. The practical result is that the same LST can be a first-class citizen in one DeFi ecosystem, usable everywhere from lending to AMMs, and effectively unusable in another simply because that ecosystem has not integrated it. This is an operational dependency to plan around, not a risk in itself.
Infrastructure Outsourcing
Liquid staking's third benefit is what it removes from your plate. Running a validator directly means owning validator uptime and maintenance, managing key security, staying on top of monitoring and software updates, and — on networks like Ethereum — meeting a chain-specific minimum deposit just to participate at all. Liquid staking outsources that operational load to specialized operators. The practical outcome is straightforward: you get staking exposure and the associated rewards without touching validator infrastructure yourself.
That outsourcing itself can take different forms. One model is a decentralized protocol that spreads delegation across a distributed set of validator operators, selected according to the protocol's own criteria. The other is a custodial or centralized "staking-as-a-service" model, where a single provider runs the infrastructure directly.
What is actually outsourced is the same in both cases — validator operations. What you retain also stays consistent: you hold a tokenized claim, the LST, representing your share of the pooled stake, regardless of which model sits underneath it.
Put together, these three benefits describe one shift: liquid staking takes what would otherwise be an illiquid, often locked staking position and turns it into a transferable, composable claim, while handing the operational burden of running validators over to specialized operators.
Liquid Staking Risks
At the same time, liquid staking does not eliminate the risks of staking. It changes their shape and even adds a few new ones on top. Evaluating an LST position purely on advertised APY misses most of what actually determines whether that yield is safe to hold.
Smart Contract Vulnerabilities
Liquid staking protocols are not a single contract but a whole stack of them, and each layer has a distinct blast radius when something breaks. A useful way to think about smart contract risk is as an attack surface map with four layers:

- Core staking/mint-redeem contracts — these handle deposits, LST issuance, and redemption logic directly. What breaks → what you experience: a bug in the redeem function halts withdrawals → the LST can no longer be redeemed 1:1 through the protocol, so it starts trading at a discount on secondary markets while users wait for a fix.
- Delegation/validator management modules — the logic that routes pooled capital to specific validators and manages operator sets. What breaks → what you experience: a misconfigured delegation contract sends stake to an unintended or malicious operator → rewards drop or slashing exposure rises without any visible change to the LST itself at first.
- Upgrade/governance controls — admin keys, timelocks, and multisig/DAO permissions that let the protocol change its own code. What breaks → what you experience: a compromised admin key or rushed upgrade pushes malicious logic live → funds can be redirected or frozen, and the failure often looks identical to a core contract bug from the outside.
- External protocol integrations — bridges, lending markets, and AMMs that hold or price the LST elsewhere. What breaks → what you experience: an oracle feeding LST price data to a lending market is exploited or misreports → positions using the LST as collateral get liquidated even though the LST's own redemption mechanics are unaffected.
The blast radius grows as you move down this list. A core contract bug is contained to the protocol itself, while an integration failure can propagate losses across every venue that accepted the LST as collateral.
Despite what you might think, you do not need to audit code yourself to get a reasonable read on this risk. A short checklist of protocol-level signals is enough to start: has the protocol been reviewed by a recognized third-party auditor, and are the reports public? Does the protocol pay for responsibly disclosed vulnerabilities, and how large is the bounty relative to total value locked? Are the core contracts upgradeable at all, or immutable once deployed? If upgradeable, are changes gated by a timelock, a multisig, or DAO governance vote, and how long is the delay before an upgrade takes effect?
These four items do not guarantee safety, but their absence is a clear signal to weigh against the advertised yield.
Slashing and Validator Performance
Validator-level losses come in two distinct forms: a slashing penalty is a punitive loss imposed by the protocol's consensus rules when a validator violates them outright — double-signing or equivocating, for example. It is a direct, often immediate cut to staked principal, and it is the rarer risk.
Performance leakage, by contrast, is not punitive and way more common. It is the reward you simply do not earn because a validator missed attestations, went offline, or otherwise underperformed its duties. No principal is destroyed, but the reward stream that would have accrued to you never materializes.

Both losses flow through to LST holders the same way: they are netted against the pooled stake the LST represents, not charged to any individual depositor directly. Depending on the protocol's accounting model, this shows up as a smaller balance increase for rebasing tokens or a slower, or reversed, climb in the exchange rate for exchange-rate tokens.
To tell validator risk apart from market risk, look for specific diagnostic cues rather than only watching the LST's market price:
- The protocol itself reports a reduced reward rate or discloses a slashing event tied to a specific operator or validator set.
- Public incident reports or announcements about changes to the operator set — removals, migrations, or downtime disclosures.
- Sustained underperformance against peer protocols staking the same asset, visible over weeks rather than a single day.
A broad discount across most LSTs for a given asset, without any operator-specific announcement, points to liquidity conditions rather than validator failure. That distinction is covered next.
LST De-Pegging and Market Liquidity
De-pegging refers specifically to a secondary-market pricing divergence: the price at which an LST trades on an exchange moves away — either at a premium or a discount — from its underlying-per-LST redemption value as defined by the protocol. It is a market phenomenon, not a change to what the LST is actually redeemable for.
Several distinct drivers can cause this divergence, and they do not overlap:
- Redemption/unbonding delays — if the protocol's redemption queue is long, sellers who need liquidity now accept a discount on the open market rather than wait.
- Shallow liquidity and slippage — thin order books or shallow AMM pools mean any meaningfully sized sell order moves the price, independent of anything happening at the protocol level.
- Leverage and unwind cascades in DeFi — LSTs used heavily as collateral can trigger forced selling when leveraged positions unwind, pushing the market price down faster than redemption fundamentals justify.
- Confidence shocks after incidents — a slashing event, a contract exploit elsewhere in the stack, or even rumors of one can cause holders to sell preemptively, widening the discount before any actual loss is confirmed.
Neither selling nor redeeming is strictly better in any situation. It is a direct trade between speed and price certainty, and the right choice depends on how urgently you need liquidity versus how much a current discount would cost you.
Custody and Regulatory Exposure
Who actually controls your assets varies sharply depending on how you accessed liquid staking in the first place, and this determines what "failure" looks like if something goes wrong.
When you hold the LST directly in your own wallet, the smart contract governs redemption. Withdrawal control sits with the protocol's code, subject to whatever the contract permits. Failure here looks like a contract bug, a frozen redeem function, or a governance decision that changes redemption terms — not an account freeze, since there is no account to freeze.

If the exchange holds the underlying assets and issues you an internal claim or a wrapped token representing your position, withdrawal control sits with the exchange, not with you. Failure here looks like account freezes, withdrawal limits imposed unilaterally, or the exchange halting redemptions entirely during stress — risks that exist independent of the underlying protocol's health.
Lastly, hybrid wrappers — a token that wraps an underlying LST or custodial claim, add another layer of smart contract and counterparty dependency on top. Withdrawal control is split between the wrapper's contract and whatever sits underneath it, so failure can originate at either layer, and diagnosing which one failed takes more effort than with the other two models.
Separate from any of these failures, regulation can also surface as a purely operational constraint rather than a market-driven one. Watch for access risk: KYC gating that suddenly requires identity verification to withdraw, geofencing that blocks users in specific jurisdictions, product shutdowns that force an unwind on the provider's timeline rather than yours, forced migrations to a different token or structure, or redemption terms that change after the fact.
None of these show up in price charts. They show up as a sudden inability to access funds on the terms you originally expected, on any other network the protocol operates on.
Liquid Staking Compared With Other Staking Methods and Liquidity Pools
| Method | Native staking | Pool/liquid staking | Restaking |
| What you deposit | Underlying asset, e.g., ETH, directly to a validator | Underlying asset to a staking pool | Already-staked position, often an LST |
| What you receive | No transferable token — a direct staking position | LST, a transferable claim token | Restaked receipt / additional reward claim |
| Where yield comes from | Base network issuance + fees/MEV | Base network issuance, net of protocol/operator fees | Base staking rewards + fees for securing extra services |
| Liquidity/exit path | Unbonding/withdrawal queue only | Sell LST on market, or redeem via protocol | Depends on underlying LST or restaking token's exit path |
| Who runs validators | You, or an operator you manage directly | Third-party validator set selected by the protocol | Original validator set + additional operators for restaked services |
| Primary risks unique to the method | Illiquidity during unbonding; self-custody/key risk | Smart contract risk; LST de-pegging | Extra slashing domains; added protocol dependencies |
| Best-fit user profile | Users who want direct chain exposure and simplicity | Users who want liquidity and DeFi integration | Users comfortable layering extra yield and complexity |
Liquid Staking vs Native Staking
The core distinction here is control versus liquidity. Native staking means holding a direct network staking position. You delegate or run a validator yourself, and what you hold is not a transferable claim token; it is simply your stake, subject to whatever unbonding or withdrawal constraints the network imposes. Liquid staking inserts a protocol layer between you and the validator set, and in exchange for accepting that layer, you receive a transferable claim token that can move, trade, or plug into DeFi while your stake keeps earning.
Liquid Staking vs Pool Staking
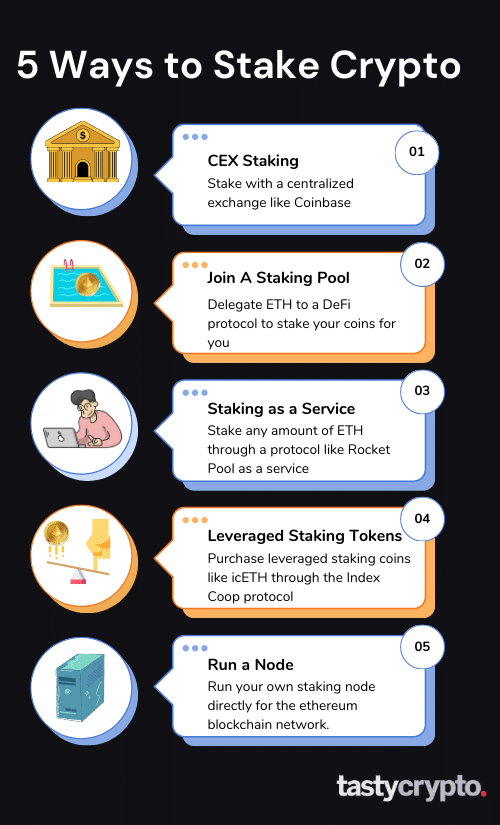
"Pool staking" is a term that gets used loosely, and it is worth pinning down. At its core, pool staking simply means staking with pooled deposits — many users contributing capital that gets delegated together rather than each person staking solo. But that umbrella splits into two meaningfully different sub-cases.
The first is pooled staking that issues an LST, which is liquid staking as covered throughout this article: your deposit is pooled, and you receive a freely transferable token in return. The second is pooled staking that does not issue a freely transferable token — a custodial or non-tokenized pooled staking arrangement, where your deposit is pooled but what you get back is an internal ledger entry or account balance rather than something you can move on-chain.
The practical way to tell these apart is a single operational check: can you transfer or sell what you receive on-chain without redeeming it first? If yes, you are dealing with liquid staking. If no — if the only way to exit is through the provider's redemption process — you are dealing with a non-tokenized pooled staking setup, closer in spirit to staking-as-a-service than to a DeFi-native LST.
Liquid Staking vs Restaking
Restaking builds on top of a staking position rather than replacing it, and the layers need to stay separate. Base staking — whether native or liquid — secures a single proof-of-stake chain and earns that chain's issuance. Restaking typically reuses an already-staked position, often via an LST, to additionally secure other services — oracles, bridges, or other protocols that need their own economic security.
This can add incremental rewards on top of base staking yield, but it does not come free. Restaking introduces additional slashing or penalty domains tied to the services being secured, plus added protocol dependencies, since your position now depends on the health of both the base chain and whatever additional service you are helping secure. The mechanism distinction is the key takeaway here: restaking stacks obligations, it does not just stack yield.
Liquid Staking Protocols and Exchanges
Liquid staking is available through several distribution channels: decentralized protocols and centralized exchanges. The choice between them shapes what you actually hold, how you exit, and what you can do with your position in the meantime.
A protocol here means the on-chain smart contracts plus the validator operators they delegate to. An exchange means a custodial platform offering staking or staking-linked products through its own account infrastructure rather than open smart contracts.
Decentralized Protocols
Interacting with a decentralized liquid staking protocol follows a consistent operational pattern, distinct from the deposit-to-reward mechanics:
- Connect a self-custody wallet directly to the protocol's interface — no account creation, no intermediary holding your keys.
- Deposit the underlying asset into the protocol's smart contracts, which mint the LST to your wallet address.
- Receive an on-chain, freely transferable LST — a token with its own contract address that you control outright.
- Manage the position across DeFi as you see fit: holding, trading, or deploying it into lending markets, AMMs, or vaults.

Three properties are worth verifying directly rather than taking it for granted: the token is transferable on-chain, meaning you can send it to any address or contract; redemption is governed by protocol rules encoded in the smart contract rather than by a platform's discretion; and the position can be moved freely between venues — a decentralized exchange, a lending market, or another wallet entirely.
Before committing capital to a specific protocol, a few due-diligence signals are worth checking against the protocol's own docs and dashboards:
- LST integration breadth — is the token supported across lending markets, AMMs, and yield vaults, or does it sit largely idle outside the protocol itself?
- Secondary-market liquidity depth — is there sufficient order-book or pool depth for the LST to be sold without significant slippage?
- Governance and upgrade posture — are the core contracts upgradeable or immutable, and if upgradeable, is there a timelock or multisig gating changes?
- Validator-operator set design — is the operator set diverse and permissionless, or concentrated among a small, permissioned group?
- Fee transparency — are protocol and operator fees clearly disclosed, and is it obvious how and when they are applied to rewards?
Ecosystem fit is a practical constraint worth planning around, separate from any of the above. An LST that is deeply integrated on one chain or DeFi ecosystem — say, one with broad lending and AMM support on Ethereum — may have little to no support elsewhere. Before choosing a protocol, check that your wallet, target chain, any bridges you would need, and the specific DeFi venues you plan to use all actually support the LST in question. This is a compatibility question to resolve upfront, not a risk to discover after the fact.
Coinbase and Centralized Exchanges
Centralized exchanges like Coinbase offer staking through a different structural model, and the product form matters more than it might first appear.
Exchange-run staking as a service has the exchange stake your deposited asset on your behalf and credits rewards to your account, but does not mint a freely transferable on-chain token. What you hold is an internal account balance, not an on-chain claim.
Exchange-issued or exchange-supported liquid-staking wrappers are offered when an exchange issues or supports a token representing your staked position that does carry an on-chain contract address, functioning closer to a decentralized LST.
The way to tell these apart is straightforward: check whether your position corresponds to an on-chain token contract address you can look up on a block explorer, or whether it is simply a balance reflected inside the exchange's own account system. If there is no contract address, you are holding an internal claim, not a transferable token.
Centralized venues also carry operational constraints worth checking before depositing, distinct from the custody and regulatory risk covered separately in the Risks section:
- Withdrawals or redemptions may be gated by the platform's own processing timelines, independent of any underlying protocol unbonding period.
- Availability can vary by jurisdiction — a staking product offered in one region may simply not appear in another.
- Transfers may be limited to the exchange's supported networks, meaning you cannot necessarily move a position to an arbitrary chain or wallet the way you could with an on-chain LST.
Centralized vs Decentralized Trade-Offs
| Dimension | Decentralized Protocol | Centralized Exchange |
| Custody model | Self-custody — you hold the LST in your own wallet | Account-based claim — the exchange holds the underlying asset |
| Transferability | On-chain LST, freely transferable to any address | Often an internal balance; on-chain token only if the exchange issues one |
| DeFi usability | Usable as collateral, in AMMs, and in vaults across integrated venues | Limited or none unless the exchange supports an on-chain wrapper |
| Redemption path control | Governed by protocol smart-contract rules | Governed by platform policy and processing timelines |
| Liquidity/exit options | Sell via a decentralized exchange or redeem through the protocol | Sell or withdraw through the exchange's own order book or account system |
| Transparency | Verifiable via on-chain data — contracts, dashboards, validator sets | Relies on the platform's own reporting and disclosures |
| Geographic/product availability | Generally accessible wherever the wallet and chain are supported | Can vary by jurisdiction and the exchange's product rollout |
| Operational simplicity | Requires managing a wallet and interacting with contracts directly | Single interface, no wallet or contract interaction required |
Conclusion
Liquid staking solves a specific tension: staking rewards typically require locking up capital, but an LST keeps that capital liquid and usable while it earns. You accept a protocol layer and its associated smart contract, validator, and de-pegging risks in exchange for a transferable claim token that can move, trade, or plug into DeFi without waiting on an unbonding period. Whether that trade-off is worth it depends on how much you value liquidity and DeFi composability against the added smart contract and market-pricing risk it introduces.
The ChangeHero blog is a good place to start! If that is more your thing, we also have social media for daily content and live updates: X, Facebook, and Telegram
Frequently Asked Questions
How does Liquid Staking differ from native staking?
Native staking produces a direct, often non-transferable staking position, while liquid staking produces a transferable tokenized claim — a Liquid Staking Token (LST) — representing the staked position plus accrued rewards. The key nuance is that liquid staking inserts a protocol layer between the user and the validators, which changes how you exit: instead of waiting solely on the network's unbonding process, you can also sell the LST on the open market rather than relying only on protocol redemption.
What are Liquid Staking Derivatives?
Liquid Staking Derivatives (LSDs) are tokenized claims representing staked assets and the staking rewards that accrue to them, and they can be held, transferred, or used elsewhere in DeFi. The nuance worth keeping straight is terminology: "LST" typically refers to the specific token itself, while "LSD" is the broader category name used to describe this class of staking-claim tokens in general.
What is the difference between Liquid Staking and Liquidity Pools?
Liquid staking yield primarily comes from proof-of-stake rewards earned for helping secure a network, whereas liquidity pools primarily earn trading fees and/or incentive emissions for supplying two-sided liquidity to a market. In practice, this means what you actually hold also differs: an LST is a single-asset claim token tied to a staked position, while a liquidity pool position is an LP token representing a share of a two-asset pool.
If you would like to learn about how liquidity pools work, read our guide.
What are the advantages of Liquid Staking Tokens?
Liquid Staking Tokens offer three distinct advantages: transferability and liquidity, since you can trade the claim rather than waiting on an unbonding period; DeFi usability, since the token can serve as collateral, be deployed in liquidity pools, or plug into vault integrations where supported; and operational simplicity, since you gain staking exposure without running validator infrastructure yourself. The nuance to keep in mind is that these advantages only materialize when the specific LST has active secondary markets and real DeFi integrations behind it — an LST without either is functionally illiquid despite its design.
