Stablecoins Explained: What They Are and Why Need Them


Key Takeaways
- ⚖️ Stablecoins are blockchain-based tokens designed to track a reference asset, most commonly the US dollar, but a peg (link to the tracked asset) is a target price rather than a hard guarantee.
- ⚖️ The main stablecoin designs are fiat-backed, crypto-backed, commodity-backed, and algorithmic. Each design uses a different peg mechanism and carries a different risk surface.
- ⚖️ Stablecoins are widely used for crypto trading, DeFi liquidity, payments, cross-border transfers, and synthetic dollar access in unstable economies.
- ⚖️ The core risks are de-pegs (target price deviation), reserve opacity, issuer control, custody failures, smart contract exposure, scams, and regulatory uncertainty.
- ⚖️ Yield on stablecoins is not “free interest.” It usually comes from lending, liquidity provision, or third-party deployment, which means counterparty, liquidity, and smart contract risks must be evaluated separately.
Disclaimer
This article is for educational purposes only and does not constitute investment, legal, tax, or financial advice. Stablecoins can de-peg, platforms can restrict withdrawals, and on-chain transfers are generally irreversible. Always verify the stablecoin contract, network, issuer documentation, redemption terms, and local regulatory status before buying, transferring, or using any stablecoin.
Contents
Although stablecoins look simple from the outside — one token, one dollar — the mechanics underneath are anything but obvious. Some depend on bank-held reserves, some on overcollateralized crypto positions, some on commodity custody, and some on incentive loops that can become fragile under stress. In this guide, we will break down how stablecoin pegs and reserves actually work, what stablecoins are used for, what can go wrong, and how to evaluate whether a specific stablecoin fits your trading, payment, savings, or yield strategy.
Stablecoin Basics
A stablecoin is a token built around a target price — most commonly 1:1 with a fiat currency such as the US dollar. The market price is different: it is whatever traders are willing to pay for that token on an exchange, in a swap, or through a liquidity pool at any given moment.
That distinction is key. A peg is not a guarantee stamped into the code. It is an objective maintained through external mechanisms: reserves, collateral, arbitrage, redemption pathways, market liquidity, or supply incentives. When those mechanisms work, the market price tracks the target price closely. When they fail, the market and target prices can drift apart.
Pegged Digital Tokens
The basic stablecoin lifecycle starts with issuance and redemption.
A simplified example looks like this:
- A user deposits $100 into a stablecoin system.
- The system issues 100 tokens. This is minting.
- Later, the user returns those 100 tokens.
- The system destroys them and releases $100 back. This is burning or redemption.
In reality, most entities working directly with issuers are professionals and institutions, while retail deals with already circulating tokens. Who can mint and redeem — and how reliably they can do it — directly affects how tightly the stablecoin holds its peg. If redemption is fast and trustworthy, arbitrageurs can step in when the market price strays from target. If a token trades below $1, they can buy it cheaply and redeem it at face value. If it trades above $1, they can mint new supply and sell it at a premium.
That is the mechanical channel behind many fiat-backed stablecoins: redemption creates the pressure that pulls price back toward the peg.
A few terms will come up throughout this guide:
- Peg — the target price which a stablecoin is designed to maintain relative to a reference asset.
- Reference asset — the external asset, such as a currency or commodity, whose value the stablecoin tracks.
- Redemption — exchanging a stablecoin back for the underlying value it represents, removing it from circulation.
- De-peg — a situation where the market price moves meaningfully away from the target price.
Stablecoins vs Bitcoin and Other Cryptocurrencies
The core design difference between these digital assets is intent.
A stablecoin aims for low volatility around a reference asset. Bitcoin and most other cryptocurrencies do not have a target price; their prices move freely based on supply, demand, liquidity, and market sentiment.
For a user, the difference is practical. Stablecoins are useful when you want to park value, quote prices in a familiar unit, settle a payment, or move funds without taking full market exposure. Bitcoin is usually held for a different reason: speculation, long-term growth, portfolio diversification, or ideological exposure to a non-sovereign monetary network.
However, “stable” does not mean risk-free. Most de-pegs come from two broad forces:
- Confidence shocks — users begin doubting whether the stablecoin can honor redemptions at face value.
- Liquidity dislocations — thin order books, sudden demand shifts, or temporary market stress push the price away from the peg.
So far we have established the basic goal. The next question is how different stablecoin designs attempt to defend that goal.
Pegs, Reserves, and Stablecoin Types
Before comparing stablecoin types, three terms need to be defined: reserves, collateral, and stabilization mechanism.
- A reserve usually means off-chain assets — cash, securities, or commodities — held by an issuer or custodian.
- Collateral usually means on-chain assets locked in a smart contract.
- A stabilization mechanism is a set of rules and incentives that attempts to hold the peg, sometimes without direct backing.
This is why saying a stablecoin is “backed” is not specific enough. It can mean off-chain reserve assets, on-chain collateral, or no direct backing at all. Those are different systems, and they fail in different ways.
Fiat-Backed Stablecoins
Fiat-backed stablecoins are the most common design. Their mechanics split into three parts.
Issuance and redemption pathway. Typically, only authorized participants can mint and redeem directly with the issuer, often subject to verification, minimum amounts, and redemption terms. Retail users may trade the token freely on exchanges but actually rarely redeem it directly with the issuer.
Reserve composition. The reserve is generally meant to consist of highly liquid, low-risk assets: cash in bank accounts, cash equivalents, and short-duration government bills. The logic is straightforward: if users redeem quickly, reserves must be convertible to cash quickly.
Trust assumption. This model depends on the issuer, custodians, banking partners, and redemption process. Even if reserves exist in full, users still rely on the issuer maintaining operational access to the banking system.
The peg comes from a short chain: market price drifts, arbitrage appears, authorized participants redeem or mint, and the price is pulled back toward target. If liquidity is thin or redemption slows, that correction can lag.
Crypto-Backed Stablecoins
Crypto-backed stablecoins replace off-chain reserve trust with on-chain collateral. Because the collateral is usually volatile, these systems rely on overcollateralization.
For example, a system might require $150 worth of crypto collateral to mint $100 worth of stablecoins. That produces a 150% collateral ratio, giving the system a buffer against price declines. Notable examples include Maker’s Dai and Aave’s GHO.
The failure chain is just as important as the intended design:
- The underlying crypto collateral drops in price.
- The collateral ratio falls toward the minimum threshold.
- The system triggers liquidation.
- Collateral is sold, often through auctions or automated mechanisms.
- If too many positions liquidate at once, the peg comes under stress.
Users caught in liquidation can face slippage and fees, especially when forced selling happens into a falling market.
These systems also depend on oracles. Blockchain oracles feed external price data into smart contracts, allowing the protocol to measure collateral ratios and trigger liquidations. If the price feed is wrong, stale, or manipulated, the protocol can liquidate healthy positions or fail to liquidate risky ones. This is a data dependency risk, separate from the smart contract exploit risks discussed later.
Commodity-Backed Stablecoins
Commodity-backed stablecoins reference physical assets, usually precious metals. There are two dominant structures.
The first is a direct claim on a stored commodity. The token represents a defined quantity of the physical asset held in a vault, and redemption may involve physical delivery or cash settlement. Minimum redemption amounts usually apply.
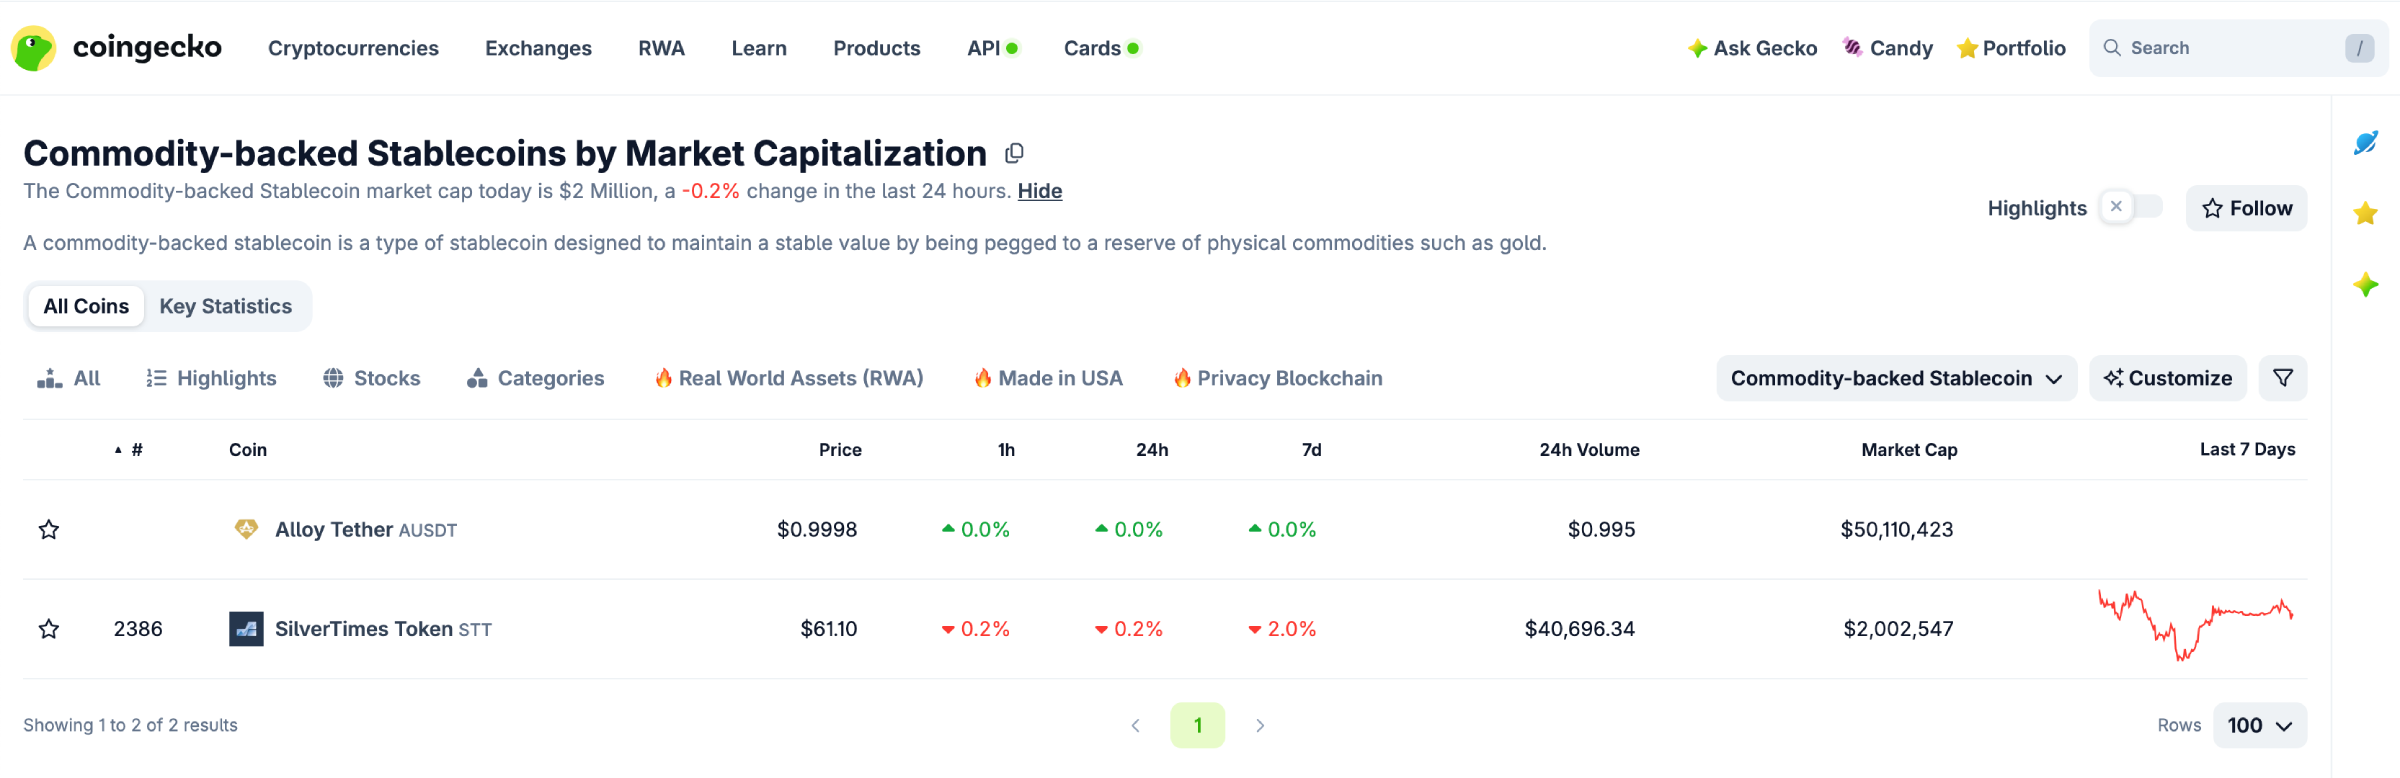
The second is financial exposure via custodians, notes, or exchange-traded structures. Here, the token tracks the commodity’s price but may not give the holder a direct claim on physical metal. Most gold and silver-backed stablecoins work like this from a retail user’s POV.
In any case, “stable” means stable relative to the commodity, not stable in purchasing power. Gold-backed stablecoins can hold their gold peg perfectly while still rising or falling against the US dollar.
Algorithmic Stablecoins
“Algorithmic stablecoin” is a broad term with a couple of sub-types.
- Algorithmic-with-collateral systems use partial or crypto collateral alongside supply rules.
- Pure seigniorage-style systems have no meaningful backing and rely almost entirely on incentives.
The common toolkit includes minting new tokens when price is above target, burning tokens when price is below target, and using bond- or coupon-like instruments to remove supply temporarily.
The central vulnerability of these models is reflexivity. These systems work only if users behave as if they believe other users will keep participating. If confidence falls, demand falls. If demand falls, the system must use more aggressive supply incentives. Those incentives can imply future dilution, which weakens confidence further. At that point, the narrative channel and the mechanical channel begin reinforcing each other in the wrong direction.
| Type | What backs it? | What enforces the peg? | Primary risk surface |
|---|---|---|---|
| Fiat-backed | Off-chain reserve assets: cash, cash equivalents, short-duration government bills | Issuer redemption and arbitrage pressure | Issuer/custodian trust and banking access |
| Crypto-backed | On-chain crypto collateral, overcollateralized | Collateral ratio thresholds and liquidation mechanics | Collateral volatility and oracle data dependency |
| Commodity-backed | Physical commodity or custodial/financial claim on one | Redemption against stored commodity or custodian structure | Commodity price volatility; custody and delivery terms |
| Algorithmic | Partial collateral or no direct backing | Supply expansion/contraction, mint/burn, bond/coupon rules | Reflexivity — falling confidence worsens the peg |
Stablecoin Uses
Stablecoins became important because they solved several practical problems at once: crypto markets needed a stable quote asset, users needed a way to move dollar-like value on-chain, and DeFi needed collateral and liquidity that did not swing as violently as Bitcoin or ETH.
Crypto Trading
In crypto markets, a stablecoin often functions as the cash leg. That role has three parts.
First, stablecoins serve as the quote currency. Instead of pricing Bitcoin against another volatile asset, exchanges can quote it against a dollar-pegged token.
Second, they let traders park value between trades. Selling into a stablecoin allows a trader to step out of volatility without fully exiting to fiat.
Third, they provide venue portability. A trader can move the same USD-like unit from a centralized exchange order book to a decentralized exchange, then into a wallet or DeFi protocol, without converting back to fiat at every step.
Payments and Merchant Settlement
Stablecoin payments are popular with crypto payment gateways as well because they are more familiar and accessible to non-crypto native users. They follow two different settlement paths.
In the first, the customer pays in a stablecoin and the merchant keeps the stablecoin. This lets the merchant hold dollar-denominated value on-chain.
In the second, the customer pays in a stablecoin and the merchant converts it to local fiat through a payment processor or exchange. The merchant receives local currency in a bank account.
The decision depends on what the merchant wants to hold after the transaction: crypto exposure, USD-equivalent value, or immediate local-currency cashflow for payroll, rent, and suppliers.
Cross-Border Transfers
Using stablecoins as if it was fiat on crypto rails makes sense in this use case, too. A stablecoin cross-border payment usually has three links.
- The sender converts local fiat into a stablecoin through an on-ramp.
- The stablecoin moves on-chain from sender to recipient.
- The recipient converts it back to local fiat through an off-ramp.
The on-chain transfer is often the fastest part. The total speed and cost are usually determined by the crypto on-ramp and off-ramp, not by the blockchain transaction itself.
This is where expectations need to stay realistic. The blockchain runs 24/7, but local banks, exchange liquidity, compliance reviews, and payout rails do not always move at the same speed.
Dollar Access in Unstable Economies
There is an important difference between using the US dollar as a unit of account and having actual USD banking access.
In economies with high inflation, capital controls, or limited access to foreign-currency accounts, dollar-pegged stablecoins essentially provide a form of synthetic dollar access. A user can hold dollar-equivalent value without a US bank account.
Compared with physical USD cash, stablecoins are easier to move across distance, easier to divide into small amounts, and easier to transport in size. Physical cash, however, does not require internet access, an exchange account, or a functioning on/off-ramp.
The practical choice depends on which dependency is more tolerable: digital infrastructure and exchange access, or physical custody and movement of paper currency.
Major Stablecoins, Issuers, and Ownership
The largest stablecoins are more than tokens and tickers; they are issuer-operated systems. Understanding who controls minting, burning, redemption, and administrative functions is part of understanding what you actually hold.
USDT and Tether
As the name implies, Tether is the issuer behind Tether USD (USDT), the largest stablecoin by market cap. USDT aims to represent a 1:1 peg with the US dollar.
Operationally, users most often encounter USDT in trading pairs and exchange liquidity. Payment use exists, but its dominant role remains market liquidity.
For USDT holders, issuer control means Tether retains the ability to mint and burn tokens, gate direct redemption access, and take administrative actions at the token level.
USDC and Circle
Circle is the issuer behind USDC (previously known as USD Coin), another major dollar-pegged stablecoin ranked near the top by market cap. Likewise, USDC aims to represent a 1:1 peg with the US dollar.
USDC is widely used in trading pairs, exchange liquidity, payments, and on-chain settlement. Circle retains the ability to mint and burn tokens, gate direct redemption access, and use administrative controls at the token level.
There is also a structural nuance: the issuer and the operational partner are not always the same entity. Distribution, banking, and infrastructure partners may support day-to-day operations, but the issuer remains the party exercising token-level control.
Euro and Regional Stablecoins
Beyond USD-pegged tokens, the market splits into three categories.
- EUR-pegged stablecoins like EURC track the euro.
- Non-USD fiat-pegged stablecoins track other local or regional currencies.
- USD stablecoins used outside the US function as synthetic dollars in local markets.
Regional stablecoins face constraints that are sometimes less visible in USD tokens:
- Local on/off-ramps — whether users can convert reliably into local fiat.
- Local liquidity depth — whether large trades create wide spreads or slippage.
- Settlement network availability — whether supported blockchains have enough regional infrastructure.
Issuer Control and Reserve Transparency
Issuer control has three separate control planes. The titular function, issuance (minting) is the ability to create new tokens. This matters because issuance is part of the mechanism that keeps price near the peg.
Redemption (burning) is the issuer’s ability to process or restrict conversion back to the underlying reference asset. This matters because redemption is the practical cash-out path.
Administrative controls include functions such as freezing or restricting addresses at the token level. This matters because it creates censorship and operational risk independent of market price.
Reserve transparency, which is to a degree expected from a centralized issuer, also sits on a ladder.
An attestation report is a point-in-time check by an outside firm confirming reported reserves on a specific date. It is useful, but it is not continuous proof.
An audit usually examines controls and processes more deeply, but it is still periodic.
Real-time proof of reserves aims to provide continuous or near-continuous assurance, but even then, it may show that assets exist without proving that they are legally claimable by token holders or free of other obligations.
When reviewing a reserve transparency page, check:
- How often reports are published.
- Whether a named third-party firm is attached.
- Whether reserves are broken down into cash, cash equivalents, government bills, or other holdings.
- Whether liabilities, meaning tokens outstanding, are reconciled against reported reserves.
- Where redemption terms and conditions are documented.
Top Stablecoins by Market Share: ChangeHero Data
Market capitalization figures give one angle to rate which stablecoins are the most valuable and popular. On-chain data and usage statistics give another, complementary angle to bring the picture into focus.
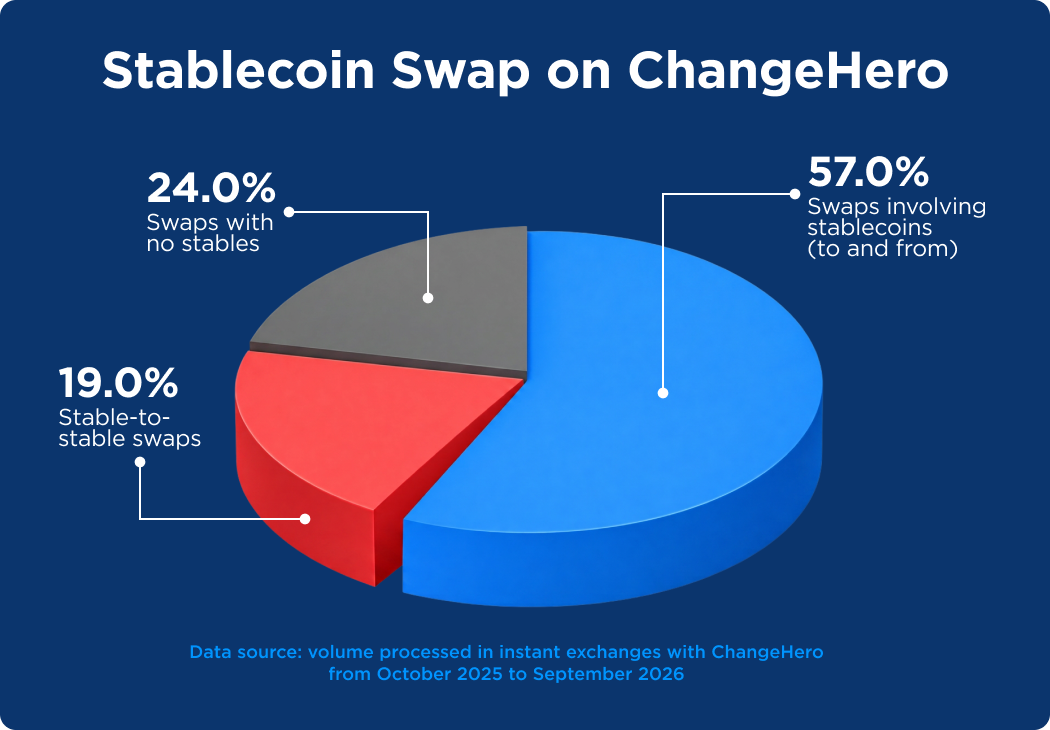
We analyzed stablecoin usage trends on the sample of one-year volume processed by ChangeHero. First, we separated swaps that involved stablecoins from ones that did not: out of all swap transactions, 76% were exchanging to, from a stablecoin, or both. In particular, within this share, 19% of all processed volume was involved in stablecoin-to-stablecoin swap transactions.
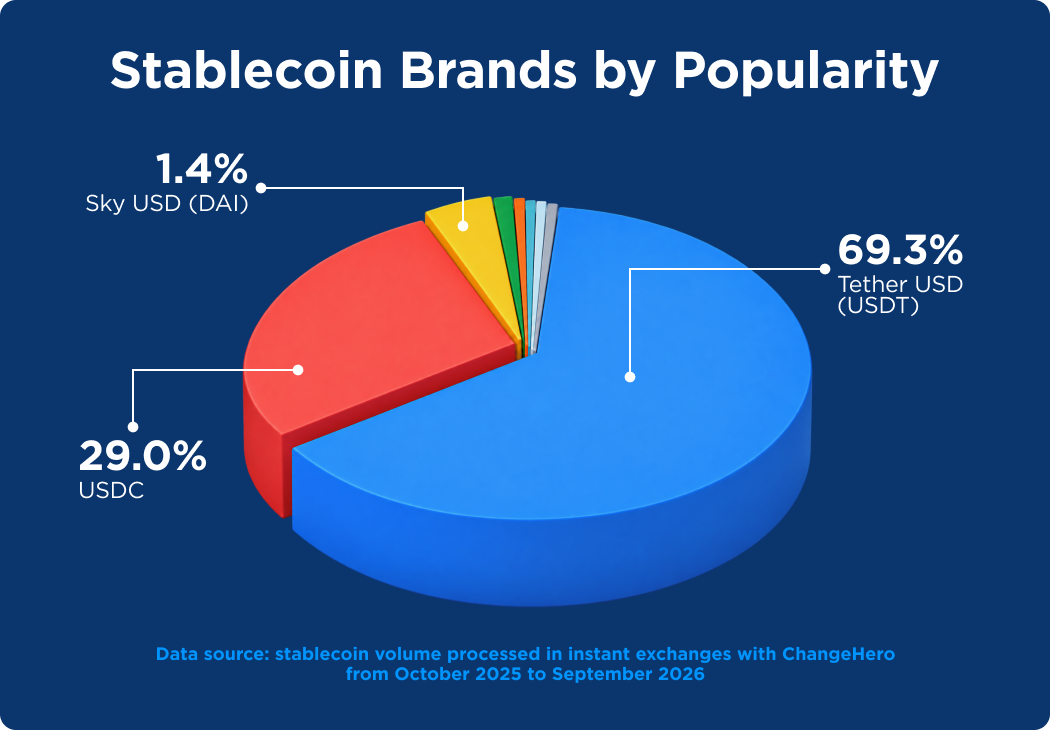
Looking further into those transactions involving stablecoins, we set out to answer two questions: first, how much USDT and USDC dominate the sample. The answer was 98%! Alternative issuers and brands were nearly a rounding error. An honorable mention goes to Sky Dollar (or DAI) that takes up more than 1% of the overall volume.
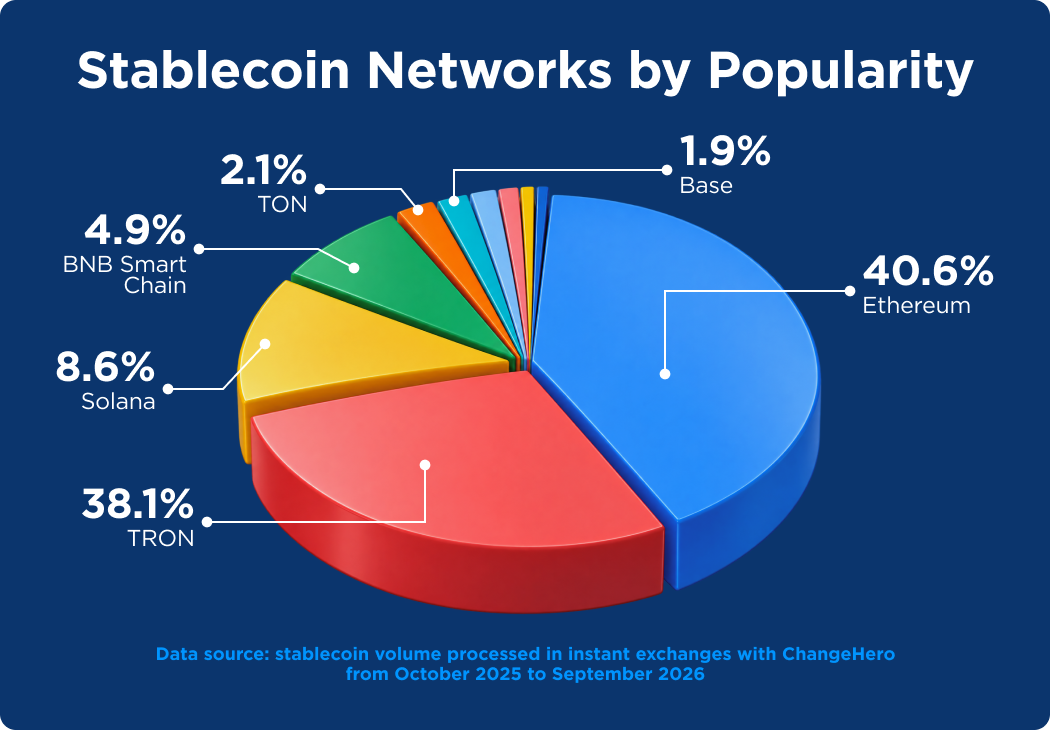
Approaching the same sample from the point of view of blockchain networks paints a somewhat more diverse picture. The two leaders—Ethereum and TRON—still take up 78.74% of the volume but at least, the alternatives are better represented. The minority share is split between Layer-1 networks like Solana, BNB Smart Chain, and TON, and Ethereum L2s: Base, Polygon, Arbitrum (cumulatively 4.95%).
These findings shed light on a few more intriguing facts. For one, at least within the sample of ChangeHero users, stablecoin users prefer established networks to solutions with lower fees. This could be attributed to network effects (more users = less reason to choose other networks) or priorities placing track record and user base over fee economies.
Buying, Storage, and Safe Use
Getting a stablecoin safely into your hands comes down to four decisions: where you buy it, where you hold it, which network you use, and how carefully you verify the destination address.
Exchanges and On-Ramps
There are three common ways to acquire stablecoins.
Centralized exchange purchase via bank/card. You create an account, complete KYC (know-your-customer identification procedure), link a bank account or card, and buy the stablecoin. The friction is usually verification, deposit holds, and withdrawal limits.
Broker/payment-app style on-ramp. Payment apps and brokers often simplify the interface, but the cost may be hidden in a spread rather than shown as a separate fee.
Crypto-to-stablecoin swap. If you already hold crypto, you can swap into a stablecoin on an exchange or swap service. The main issue is withdrawal network support.
On ChangeHero, you can use the second or third route to purchase popular stablecoins with crypto or fiat currencies. The frictions of the first path are not something to worry about here.
Before buying, confirm that the platform supports withdrawing the stablecoin on the exact network you intend to use. A platform may let you buy or hold a token while only supporting withdrawals on one or two chains. The same rule applies to cashing out. Check off-ramp availability in your region before choosing a stablecoin/network combination. Otherwise, you may need an extra bridge or swap later just to convert back to local currency.
Wallets and Custody Options
The first option you have to store stablecoins is exchange custody. You control an account login, not private keys. The exchange holds the tokens. This suits active trading balances, but the failure mode is account lock, withdrawal freeze, or platform insolvency.
The typical second step is a self-custody hot wallet. You control the private keys through a mobile app, desktop wallet, or browser extension. This suits daily transfers, but the failure mode is device compromise, malware, or phishing.
Thirdly, some holders opt for a self-custody hardware wallet. You control keys on a device that stays offline except when signing. This suits larger savings, but the failure mode is losing the device and recovery material.
Network Fees and Blockchain Selection
One of the most common mistakes is assuming that the ticker is all that matters. A stablecoin can exist on multiple blockchains at once. Same ticker, different network, not automatically interchangeable.
Choosing a blockchain for a stablecoin transfer depends on four criteria.
- Typical transfer fee environment. Some chains like Solana are consistently cheap; others become expensive during congestion.
- Confirmation and finality expectations. A trading deposit and a casual peer-to-peer payment may require different waiting periods.
- Ecosystem support. A cheap network is not useful if your exchange, wallet, or off-ramp does not support it.
- Recoverability. On-chain mistakes are generally irreversible.
For any meaningful transfer, send a small test amount first. Confirm it arrives correctly, then send the remainder. This habit catches wrong-network and wrong-address mistakes while the cost of being wrong is still small.
Yield, Lending, and Tradeoffs
If you come across it, a stablecoin peg and stablecoin yield are separate promises. The peg is about price stability. Yield is about someone paying to use your funds.
That difference is crucial. If you earn yield, your stablecoins are usually being lent, deployed, paired in a liquidity pool, or exposed to another venue. The question is not just “What is the APY?” but “Who is paying it, and what can break?”
Stablecoin Interest Accounts
Stablecoin interest accounts usually generate yield in one of two ways.
Sub-case one: the platform lends your stablecoins directly. The platform lends deposits to borrowers, market makers, or OTC desks. You hold a claim on the platform, not a direct on-chain position. Failure modes include withdrawal gating, borrower default, platform insolvency, and unilateral rate cuts.
Sub-case two: the platform rehypothecates or parks funds elsewhere. The platform deploys your funds into DeFi lending pools, liquidity pools, or other third-party venues. You still hold a claim on the platform, but now you also depend on the solvency and security of the venue underneath it.
Before using any interest-bearing account, review:
- Custody status — who controls the private keys?
- Withdrawal terms — instant, queued, locked, or notice-based?
- Yield variability — fixed or variable?
- Principal treatment — fully reserved or actively lent/deployed?
- Counterparty transparency — who borrows or receives the funds?
- Balance sheet segregation — are customer assets legally separated or commingled?
DeFi Lending Pools
A DeFi lending pool such as Aave or Sky, works through a simple mechanism.A user deposits stablecoins into a pool and receives a receipt token or on-chain position. Borrowers draw from the pool by posting collateral worth more than the loan. The interest borrowers pay flows back to lenders.
This is decentralized finance without a platform manually setting every rate. Rates depend on utilization, meaning the share of pooled stablecoins currently borrowed.
- High utilization pushes rates up.
- Low utilization pushes rates down.
The headline APY is usually a snapshot, not a guarantee. Rates can change block by block. If utilization is very high, withdrawals may also be delayed because the pool can only release idle liquidity.
Liquidity Provision
Liquidity provision to liquidity pools is similar to lending but is not the same thing. Lending yield comes from borrower interest. LP yield comes from swap fees paid by traders using a liquidity pool, sometimes supplemented by incentive token emissions.
The pool composition matters. A stablecoin-to-stablecoin pool like Curve usually has lower volatility but still carries de-peg risk. A stablecoin-to-volatile-asset pool can generate higher fees but exposes the LP to the volatile asset.
This is where impermanent loss (IL) comes in. IL is the opportunity-cost effect that occurs when pooled asset prices move apart and the pool’s rebalancing leaves you with less value than simply holding the assets separately. In stable-stable pools, IL is usually limited. However, if one stablecoin de-pegs, the pool can rebalance into the weaker asset, leaving LPs holding more of the depegged token and less of the sound one.
Counterparty and Smart Contract Exposure
Stablecoin yield maps onto four risk categories.
- Counterparty/credit risk — borrower default or platform insolvency.
- Liquidity risk — withdrawal delays, utilization lock, or redemption gating.
- Smart contract/oracle risk — bugs, parameter failures, or faulty oracle-triggered liquidations.
- Stablecoin-specific risk — a de-peg that cascades through lending markets or liquidity pools.
A practical allocation framework is simple: match risk to time horizon. Funds needed soon belong in the most liquid, lowest-risk option. Longer-horizon funds can tolerate more complexity, but only if the added yield compensates for the added exposure.
Unusually high yield is a signal, not a gift. It usually points to longer lockups, weaker borrowers, additional leverage, or risk layered somewhere upstream, if not outright scam.
Risks, Regulation, and Consumer Protection
Every stablecoin design has a failure mode. The key is to identify which one you are exposed to before it appears in the market price.
De-Pegging and Reserve Risk
A depeg is often treated as one event, but it has two layers.
De-peg as a market symptom. The token’s price drifts in secondary markets because of order flow, sentiment, or liquidity imbalance. This can happen even if reserves are sound.
De-peg as a broken correction pathway. Redemption, arbitrage, or liquidity mechanisms fail to close the gap. This is more serious. A temporary discount that closes within hours is not the same as a persistent depeg caused by redemption frictions.
Reserve risk is separate from price behavior. It lives on the asset side of the ledger.
- Asset quality — what the reserve is actually made of.
- Liquidity and maturity matching — whether assets can be converted to cash quickly enough.
- Operational access — whether banking rails and redemption windows function under stress.
Early-warning signals include:
- Persistent small discounts or premiums across venues → the stabilization pathway may not be fully closing the gap.
- Widening spreads or thin order books → market makers may be reducing exposure.
- Redemption frictions → liquidity or operational strain may be building.
- Changes in reserve disclosure cadence or detail → transparency may be weakening.
- Unusual minting/burning volume spikes → large holders may be repositioning.
- Cross-exchange price divergence under normal conditions → structural weakness may be present.
Custody, Hacks, and Fraud
Three threat models are often blended together, but they require different responses.
Custodial/platform risk. If stablecoins sit on an exchange, you hold a claim on the platform. If the platform halts withdrawals, becomes insolvent, or restricts your account, the stablecoin itself can be functioning normally while your funds remain inaccessible.
Smart-contract/token risk. This concerns the token contract itself: bugs, admin key misuse, freeze functions, or other token-level controls.
Fraud and social engineering. This targets the user directly: fake support, fake recovery services, impersonation, deposit-address swapping, and phishing.
Consumer protection differs sharply between regulated financial accounts and on-chain transfers. A bank account may have deposit insurance, chargeback mechanisms, or formal recourse depending on jurisdiction. An on-chain stablecoin transfer generally does not. Once confirmed, an action is usually final.
The GENIUS Act and MiCA
Two currently developing regulatory frameworks are especially relevant to stablecoins.
The GENIUS Act in the United States
- Scope: Targets fiat-referenced, payment-oriented stablecoins rather than crypto assets broadly.
- Core policy levers: Establishes reserve and backing expectations, redemption rights, disclosure, audit, and attestation requirements, plus supervision and licensing. Issuers also remain subject to standard financial-crime obligations like anti-money-laundering (AML) screening.
- What changes for users: Reserve composition and redemption terms should become clearer and more standardized for issuers operating under the framework. What does not change: market price can still drift, custodial risk remains, and the SEC retains separate jurisdiction over securities-like crypto assets where relevant.
The vast majority of stablecoin volume currently is in dollar-denominated tokens, with a sizeable portion provided by issuers based in the US.
MiCA (Markets in Crypto-Assets) in the European Union
- Scope: Covers crypto-assets broadly within the EU, including “e-money tokens” and “asset-referenced tokens.”
- Core policy levers: Requires issuer authorization, reserve and custody rules, redemption rights at par value, and ongoing disclosures.
- What changes for users: Authorized issuers under MiCA must meet baseline reserve and redemption standards. What does not change: a MiCA-authorized stablecoin can still de-peg in secondary markets, and platform-level custody risk remains outside the stablecoin issuer itself.
Stablecoins vs CBDCs
A central-bank-issued digital currency or CBDC and a stablecoin can look similar because both are digital and both aim to represent currency value. Structurally, they are different. A stablecoin is a private liability designed to mimic money-like stability. A CBDC is central bank money in digital form.
Issuer and liability. A stablecoin is issued by a private company. A CBDC is a direct liability of a central bank.
Distribution model. Stablecoins move through token networks and blockchain rails. CBDCs typically distribute through banks and licensed intermediaries.
Privacy and compliance posture. Stablecoin transfers are generally pseudonymous on-chain, with compliance concentrated at on/off-ramps. CBDC privacy depends on national design and is usually implemented closer to the central bank or intermediary layer.
Programmability and control surfaces. Stablecoins can include issuer-level controls such as freezing or blacklisting addresses. CBDC control surfaces depend on policy choices and implementation.
“CBDC” is not one design. Every country can implement it differently, so the real comparison is always between a specific stablecoin and a specific CBDC model.
Conclusion
Although stablecoins appear to be “crypto dollars” in daily usage, the reality is more nuanced. Beyond USDT and UDSC, there are many more brands and types of stablecoins but as it is today, these two brands, and by proxy, their model, dominate in the market.
If you enjoyed this rundown, check out and subscribe to our blog for more. Give ChangeHero a follow on X, Facebook, and Telegram for live updates and more content.
Frequently Asked Questions
What are stablecoins?
Stablecoins are digital tokens designed to track the value of a reference asset, most commonly a fiat currency like the US dollar. “Stable” means the token attempts to stay close to that reference price; it does not mean the token is risk-free or immune to secondary-market price movement.
How do stablecoins work?
Stablecoins hold their peg through issuance, redemption, arbitrage, reserves, collateral, or supply incentives. The exact mechanism depends on the stablecoin type. Who can redeem directly matters as much as the peg design itself, because redemption access determines how quickly arbitrage can close price drift.
Are stablecoins actually stable?
Stablecoins are usually stable in the sense that their market price stays close to the target most of the time. However, “close” and “guaranteed” are not the same thing. A brief discount that closes quickly is different from a true depeg where the correction pathway breaks down.
How are stablecoins regulated today?
Stablecoin regulation differs by jurisdiction. Most regimes focus on the same core issues: reserve quality, redemption rights, issuer disclosure, supervision, and financial-crime compliance. The GENIUS Act and MiCA are two important examples of frameworks that address these concerns.
What is the difference between stablecoins and CBDCs?
A stablecoin is issued by a private company and represents a private liability. A CBDC is issued by a central bank and represents central bank money. The difference is not only the issuer; it also affects distribution, privacy, compliance, and control surfaces.