Ultimate Guide to USDT — What Is It & How to Utilize Tether Payments


Key Takeaways
- 💲 USDT is the ticker for Tether’s dollar-referenced stablecoin, designed to track 1 U.S. dollar per token;
- 💲 The dollar peg depends on reserves, liquidity, redemption access, arbitrage incentives, and market confidence;
- 💲 USDT exists across multiple blockchain networks, including Ethereum, TRON, Polygon, and other supported chains, but USDT on one network is not automatically interchangeable with USDT on another.
Disclaimer
Nothing on this page constitutes investment, legal, tax, or financial advice. Stablecoins can reduce exposure to crypto volatility, but they do not remove issuer risk, counterparty risk, redemption risk, custody risk, smart contract risk, or network execution risk. Always verify deposit networks, wallet addresses, fees, and platform requirements before transferring funds.
As an elevator pitch, “USDT is like a digital dollar” gets the point across. However, it is a gross oversimplification and even a misrepresentation of what it is in reality.
USDT is a stablecoin token issued by Tether that targets a 1:1 value with the U.S. dollar. In plain terms, it is a blockchain-based token used as a dollar-like unit inside crypto markets, so traders and platforms can move value without constantly switching back to traditional bank money. There is more to it, so walk through this guide to complete the puzzle.
USDT Meaning and Stablecoin Model

Let’s circle back to the definition: USDT is the ticker for a stablecoin token issued by Tether and designed to reference 1 U.S. dollar per token. Here, “USDT” is the token unit, “Tether” is the issuing company, and “1 U.S. dollar” is the target value the token is meant to track.
If each ‘Tether USD’ you see in a wallet were literally a dollar sitting in your personal bank account, the definition would be a lot shorter and simpler. It also is not identical to “dollars on an exchange balance,” because an exchange balance is an internal platform record, while USDT is a token that can be transferred on a blockchain.
Tether USD Definition
What does stablecoin mean? A stablecoin is a crypto asset designed to track another reference value. In the case of Tether USD, the reference value is the U.S. dollar.
This gives USDT a specific role in the market. It is not primarily used for upside exposure like Bitcoin, nor is it simply an internal exchange accounting unit. It is used as a transferable dollar-linked token that can move through supported blockchain networks and trading venues.
Dollar Peg Mechanism
USDT’s price peg works as an incentive and arbitrage model, not as a guarantee as if the market price can never move away from $1.
Here is how it works. When USDT trades above $1, market participants have an incentive to bring more USDT into the market or sell existing USDT at the higher price. That extra selling pressure can push the market price back toward the dollar target.
Vice versa, when USDT trades below $1, market participants may buy USDT at the discount if they believe it can later be sold, redeemed, or otherwise used closer to $1. That buying demand can pull the price back toward the intended reference value.
This peg can and does weaken when the mechanics behind that arbitrage become harder to use. Liquidity, redemption access, fees, and broader market stress can all affect how tightly USDT trades around $1, even if the target remains the same.
In other words, the peg is not magic. It is a market structure that works best when liquidity is deep, confidence is intact, and participants can move between USDT and dollars efficiently.
USDT as a Blockchain Asset
Operationally, USDT is a token on a blockchain. Ownership is tied to blockchain addresses, transfers happen as on-chain transactions, and the same ticker, USDT, can exist as separate token contracts on different networks.
Basically, USDT on Ethereum and USDT on Tron are not automatically interchangeable in a wallet simply because they share the same ticker. To move between them, a user generally needs to use a bridge or swap, or avail of an exchange-supported transfer path, and must choose the correct network when sending or receiving.
Tether Reserves and Dollar Parity

Tether USD’s peg to the US dollar is not something traders agreed on. It is backed by Tether’s reserves.
More precisely, it refers to the assets Tether says support the token’s ability to maintain dollar parity. A reserve asset is something held or claimed by the issuer to back obligations connected to the token; that can include cash, short-term instruments, or other assets depending on the disclosure.
Tether regularly publishes attestations to disclose the reserve composition and backing. This is an accountant’s point-in-time report based on information provided for that reporting moment, while an audit is generally a broader and more comprehensive assurance.
The reader implication is important: an attestation can help you see what was reported at a specific point, but it does not prove continuous solvency at every moment after that snapshot. It also does not remove the need to understand what the reserves are made of, how quickly they could be converted to cash, and where the main dependencies sit.
Reserve Assets and Attestations
Tether having reserves does not mean they actually keep cash. Reserve disclosures provide information on the asset type mix. Cash is different from short-term instruments, and both are different from less liquid or more complex holdings. That mix matters in case many holders want liquidity at the same time.
If you evaluate USDT as an instrument, also look at liquidity under stress. An asset may look safe in normal conditions but still take time or price concessions to convert into cash during redemption pressure.
Finally, consider counterparty and concentration exposure. Heavy dependence on a small number of banking partners, custodians, or issuers can affect market confidence if one of those relationships becomes strained.
Price Fluctuations Around $1
USDT’s market price is formed on exchanges through order books, spreads, and available liquidity. Buyers place bids, sellers place offers, and the last traded price reflects where those orders meet. Because order books are not infinitely deep, the traded price can move slightly above or below the dollar target even when the intended reference remains stable.
A simple scenario is a sell wave: bids thin out, sellers accept lower available bids, and the price prints slightly below the target until arbitrage traders step in or liquidity refills. The reverse can happen when demand is heavy and sellers are scarce, causing trades to print slightly above the target for a period.
Normal wobble is different from depegging. A temporary small deviation driven by exchange liquidity, spreads, or venue-specific order flow is not the same as a sustained discount caused by redemption friction, reduced confidence, limited access to liquidity, or concerns about whether market participants can move between USDT and dollars efficiently.
A few factors can help distinguish between a momentary wrinkle and a cause for concern about a depeg:
- how long the deviation lasts;
- whether it appears across major venues;
- whether redemptions remain accessible;
- whether the market still trusts the mechanism that should pull the price back.
Bank Deposit and Insurance Status
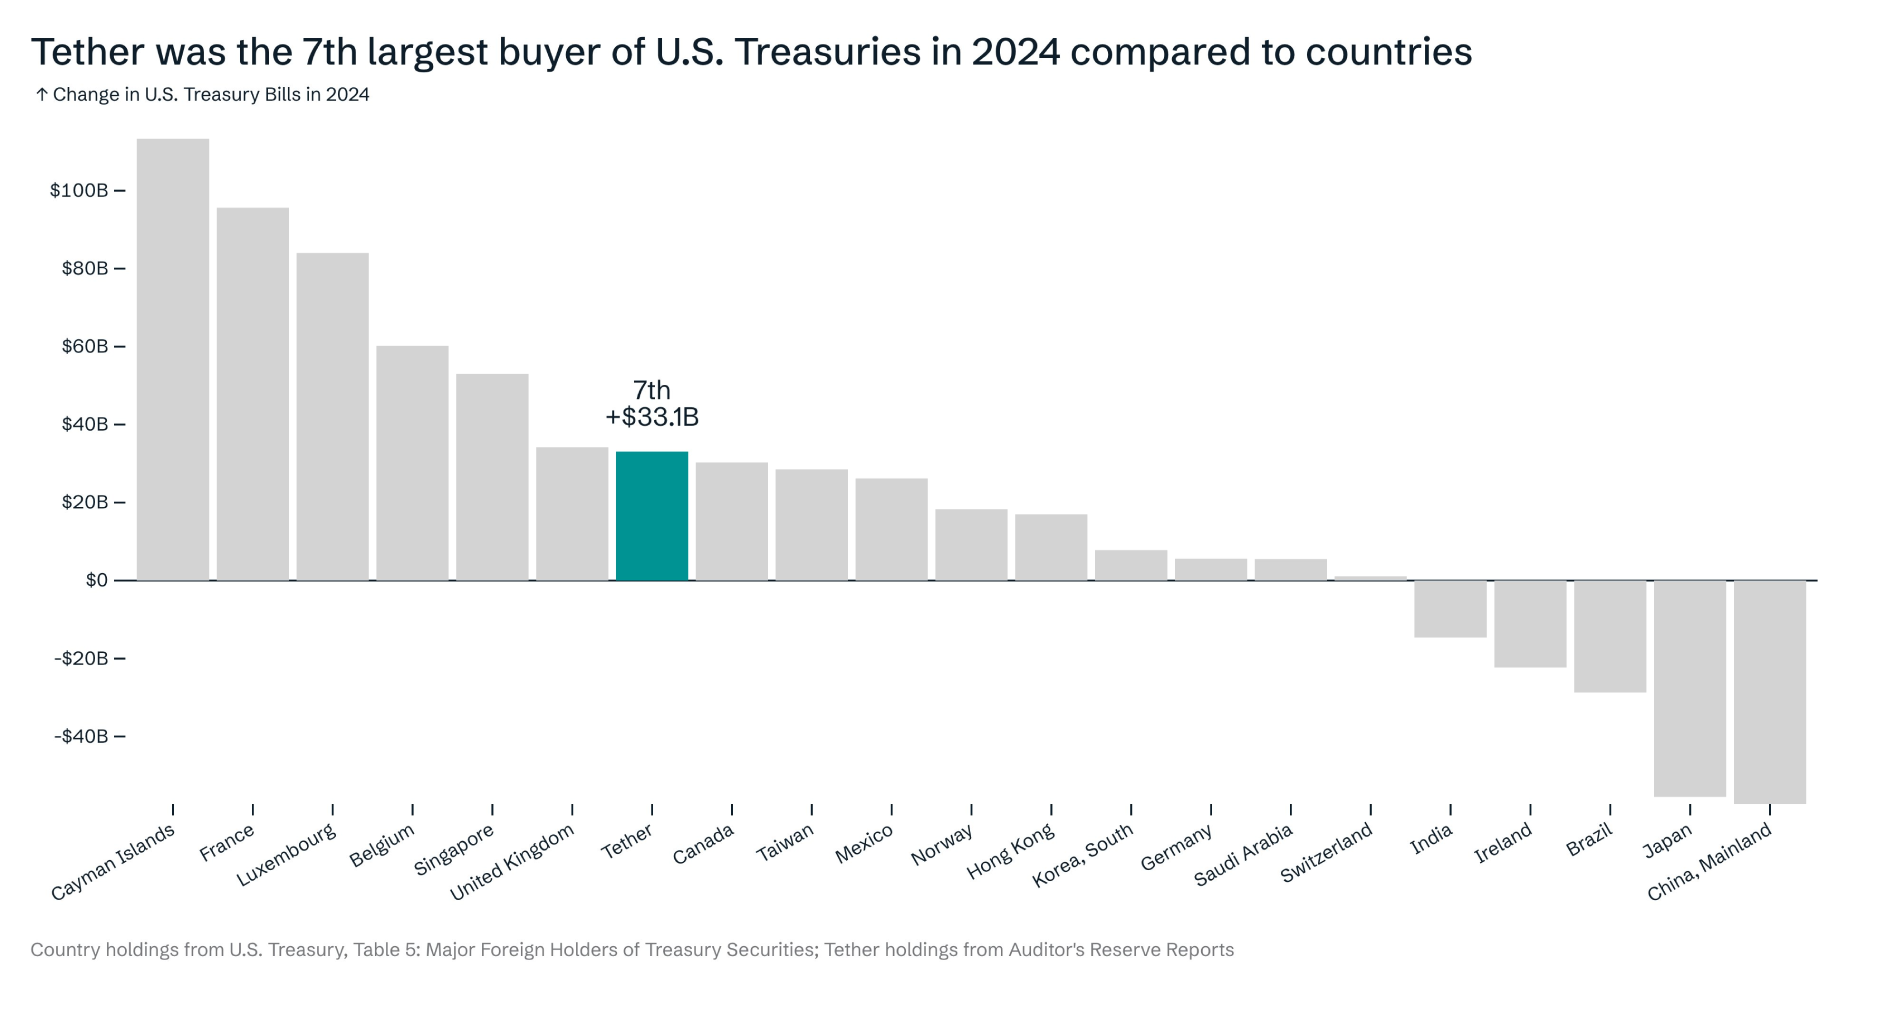
USDT is used not just to hedge against volatility in cryptocurrencies. It is a well-known fact that dollar stablecoins serve as real-world dollar replacement in foreign economies at the grassroots level but it comes with a major catch all the same.
Holding USD in a bank account and holding USDT are not the same legal or practical position. A bank deposit is generally a claim on a regulated bank, and many jurisdictions have deposit insurance regimes that may protect eligible balances up to stated limits or even restrict dollar-denominated accounts.
USDT, by contrast, is a blockchain token tied to an issuer liability structure. It is not itself a bank deposit, and ordinary bank deposit insurance protections typically do not apply just because the token references the dollar. It’s important to remember that USDT does not even qualify as a fiat currency.
A USDT balance on an exchange app may expose you to both issuer risk and exchange or custodian risk, because the platform is recording what it owes or holds for you. A USDT token on-chain in a wallet is a token position that still depends on the issuer’s ability and willingness to support the token’s value. A USD balance at a bank is a bank liability and carries bank-specific protections and bank-specific risk, rather than the same issuer and token-market risks connected to USDT.
Main Uses of USDT
USDT is most useful when a crypto user needs a dollar-like unit inside crypto infrastructure. That can mean trading, parking value during volatility, making global transfers and payments, or using DeFi liquidity.
In any case, it would be useful to know how to send USDT; read our dedicated guide if you need only the essentials.
Crypto Trading Base Currency
Earlier crypto exchanges used to rely on local currencies more but USDT has come to often be used as a base currency on a crypto exchange, letting traders move in and out of assets through a USDT trading pair instead of returning to fiat after every trade.
Typically, trading on a centralized exchange looks like this:
- convert fiat or another crypto asset into USDT;
- use USDT trading pairs to enter a position such as BTC/USDT or ETH/USDT;
- exit back into USDT when you want to pause or switch strategies;
- move USDT between venues if another exchange has better liquidity or access to a specific market;
- optionally settle back to fiat later when you are ready.
This use case is most common with active traders who want a common quote asset across many markets and exchanges. Thin trading pairs can still have wide spreads or slippage, and leaving funds on an exchange adds venue-specific risk while you trade.
Market Volatility Parking
USDT is also used to “park” value during volatile market periods, keeping funds available inside crypto markets rather than cashing out to a bank and waiting through traditional transfer timelines.
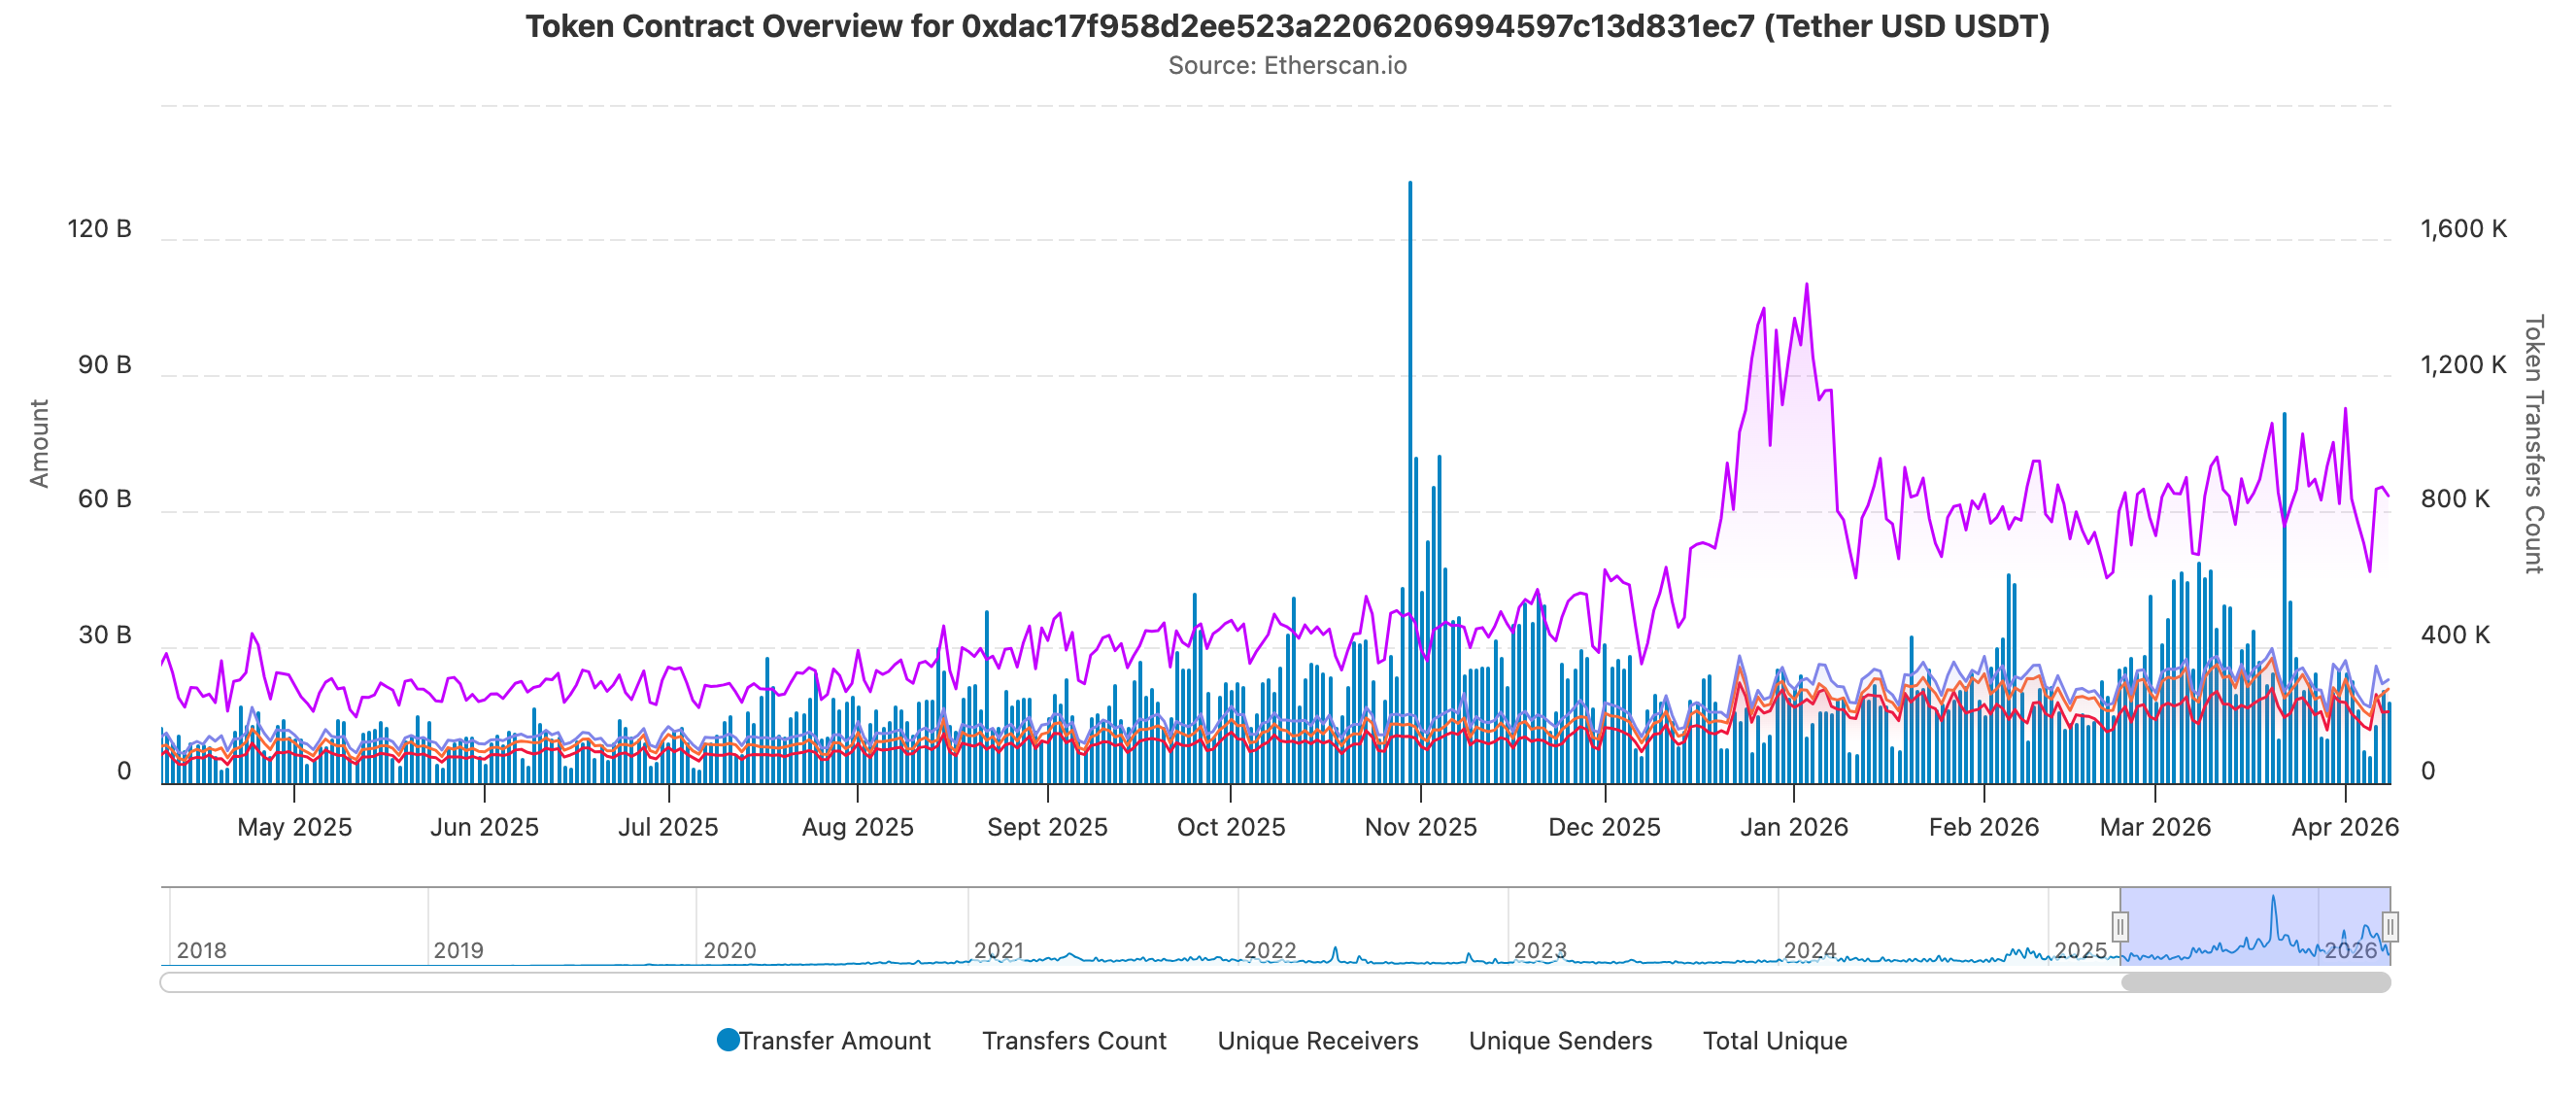
Think of hedging as this scenario:
- sell a volatile asset into USDT during a drawdown;
- keep the balance available on the exchange or in a wallet;
- monitor the market for a re-entry signal;
- rotate back into the asset when conditions match your plan;
- repeat the process when you need temporary stability without leaving the crypto environment.
Traders or holders who want fast availability during market moves without fully stepping out of crypto rails make the most out of this use case. That being said, during market stress, USDT can trade slightly away from its intended dollar reference, so “parking” is not the same as eliminating all price risk.
Global Transfers and Payments
As briefly mentioned before, USDT is used for global transfers and payments, including person-to-person remittance and exchange-to-exchange treasury movement where users want a dollar-linked crypto asset to move across borders or platforms.
Compare it to how cross-border transfers usually are:
- choose the network that the recipient or receiving platform supports;
- send USDT to the recipient’s wallet address;
- wait for the transaction to settle;
- have the recipient convert to local currency or spend through a supported service if needed.
There is real demand with users who need to send dollar-denominated value across platforms, countries, or counterparties without relying only on bank wires. However, the recipient’s ability to convert or spend USDT can vary by country, service provider, compliance checks, network conditions, and fees.
DeFi Liquidity
Last but not least, USDT is used in DeFi for liquidity and yield-related activity, especially by providing USDT into a liquidity pool or using it as a borrow/lend collateral or quote asset. Essentially, this is similar to using it as base currency, just in a purely crypto setting.
A typical workflow looks like this:
- connect a wallet to a DeFi protocol;
- acquire USDT on the correct chain for that protocol;
- supply USDT to a liquidity pool, lending market, or collateral position;
- receive a position token, receipt, or dashboard balance showing your claim;
- withdraw later according to the protocol’s rules and available liquidity.
Putting stablecoin liquidity to work in decentralized markets, lending pools, or automated trading venues is more niche than using it on a centralized exchange (CEX) but it is a real use case nonetheless. DeFi adds protocol-specific risks such as smart contract failure, variable rates, and impermanent loss for liquidity pool positions still happen, stablecoins or not.
Your primary use should match your intent: trading, holding through volatility, sending value, or earning through DeFi. Once the intent is clear, the next question is mechanical — which network, which wallet, and which address.
USDT Networks, Wallets, and Addresses
Choosing a USDT network is not just a preference setting; it determines which blockchain will process the transfer and which version of the token the recipient must be able to receive.
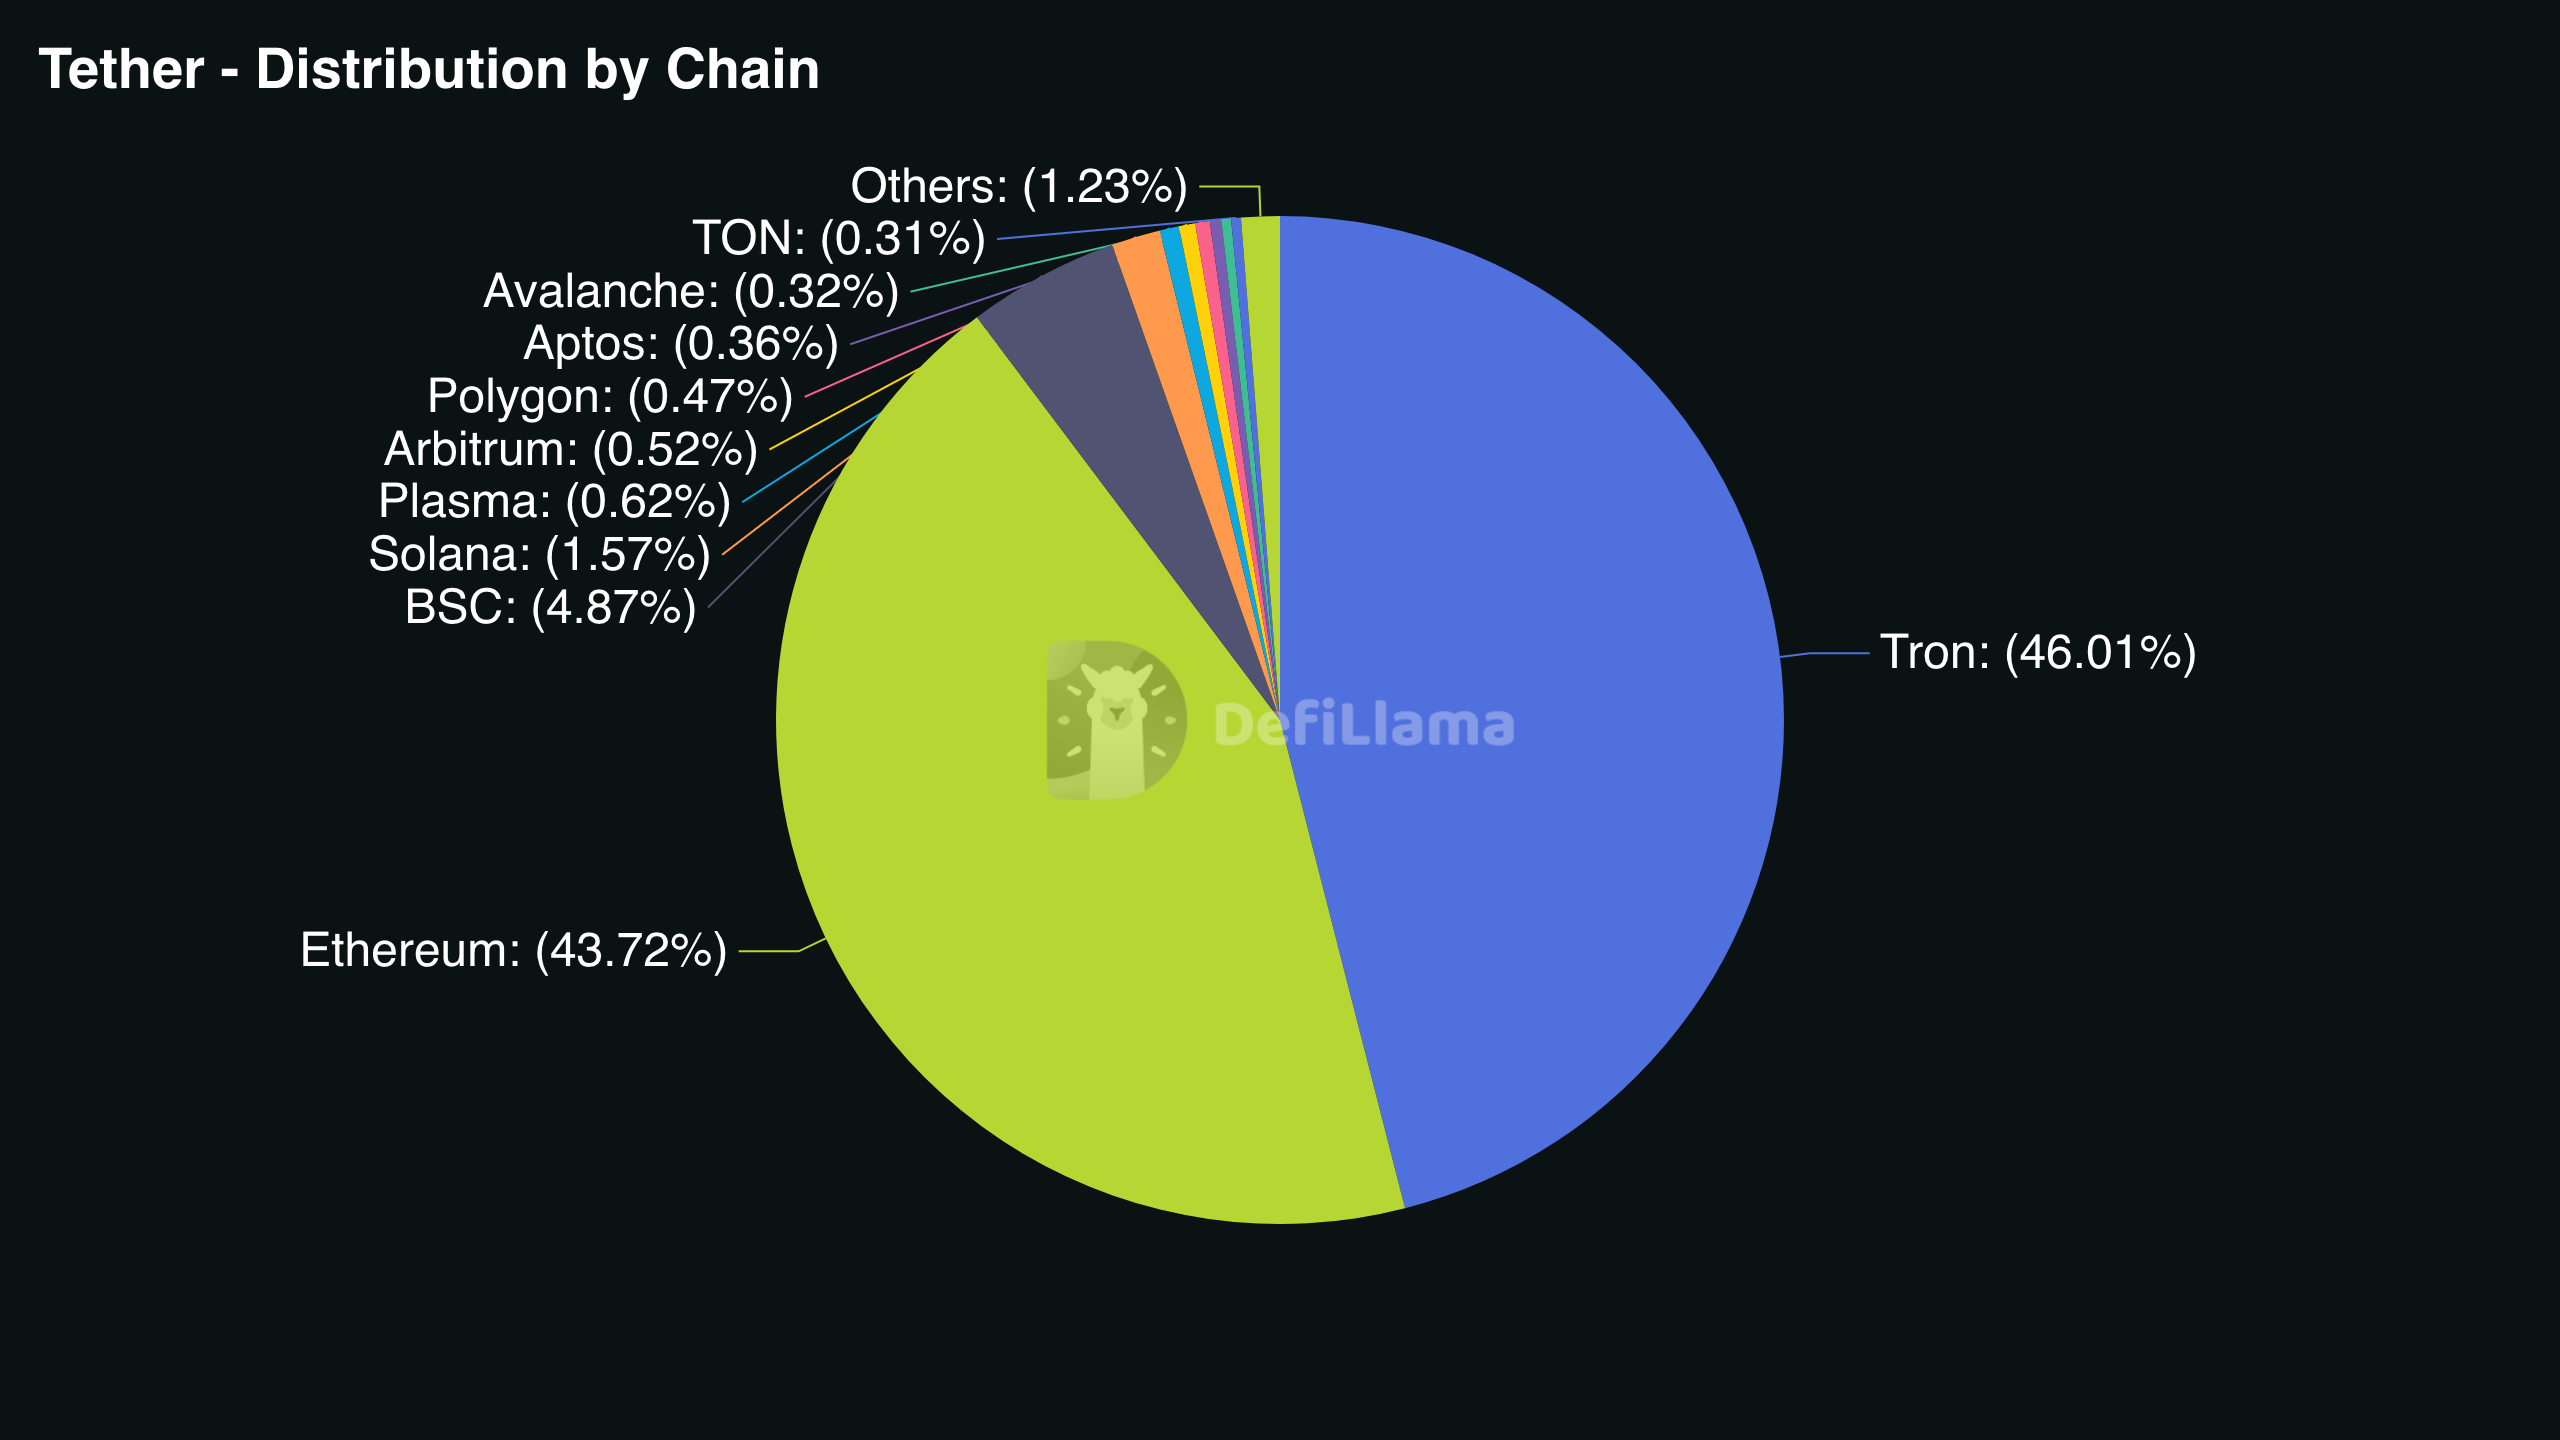
Before every transfer, use a quick network selection check:
- confirm where the USDT currently is, including whether it sits on an exchange or in a wallet and which chain it is on;
- confirm where it needs to arrive by checking the recipient platform’s supported deposit networks;
- choose based on your constraints, such as lower fees, faster settlement, or ecosystem needs like using DeFi on a specific chain.
Ethereum, Tron, Polygon, and Other Networks
Once again: USDT on Ethereum is a token contract on Ethereum; USDT on Tron is a token on Tron; they are not the same asset instance.
The Ethereum network, TRON, Polygon, and other supported chains can all carry USDT, but a transfer must still match the network selected by the sender with the network supported by the receiver.
What happens otherwise? If networks do not match, the transaction is still executed on the chosen network. The problem is that the receiving platform or wallet may not monitor or support that network and token combination, so the funds may not appear automatically. In some cases, recovery may require platform support or technical access to the receiving address; in other cases, recovery can be difficult or impossible.
This is the stablecoin version of a very old crypto rule: the transaction can be valid on-chain and still wrong for the destination you intended.
Wallet Custody Options
To use it, you (and your recipient) need to have a crypto wallet app compatible with USDT on the network of your choice.
A custodial wallet, usually an exchange account, means the platform controls the private keys and credits your balance inside its system. The convenience benefit is that network choices are usually shown inside the deposit and withdrawal flow, which makes it easier to select from supported USDT networks. The main failure mode is platform control: account restrictions, withdrawal limits, maintenance, or unsupported networks can affect whether and how you can move funds.
A self-custody software wallet, also called a hot non-custodial wallet, means you control the private keys through wallet software. The convenience benefit is direct access to on-chain transfers, DeFi applications, and multiple networks from one interface. The main failure mode is user-managed execution: you must choose the correct network, hold the right gas token if required, and confirm that the recipient accepts USDT on that same chain.
A self-custody hardware wallet, often described as cold storage, also gives you control of the private keys, but signs transactions through a separate device. The convenience benefit is stronger key isolation for longer-term holding while still allowing network-specific USDT transfers when connected to compatible wallet software. The main failure mode is device and backup management, plus the same network selection responsibility that applies to other non-custodial wallet setups.
For a quick choice, use our rating of the best USDT wallets. A common migration path looks like this:
- buy USDT on an exchange;
- verify which withdrawal networks the exchange supports;
- withdraw USDT on a selected network to your self-custody wallet;
- later deposit back to an exchange using that same network.
Before initiating each send, verify the supported networks at both ends, then confirm that the wallet address and selected network match the receiving platform’s deposit instructions.
Address Formats and Network Matching

By now it should be clear how critical it is to get the address right. Address format can help you recognize a network family, but it should not be the only thing you rely on: it may look valid while still being wrong for the selected withdrawal network.
| Network | Common address prefix/format cues | Common pitfall |
|---|---|---|
| Ethereum-compatible networks (EVM: Ethereum/Polygon) | Usually start with 0x... | The same address format can appear across multiple EVM networks, so an Ethereum-style address does not prove the recipient supports USDT on that specific chain. |
| Tron / TRON | Often start with T... | Sending to a Tron-style address only works when the sender has selected the matching TRON network and token type supported by the receiver. |
| Exchange deposit addresses (varies) | Format depends on the platform and selected network | Rely on the platform’s displayed network label rather than guessing by address appearance. |
An address-looking string alone does not guarantee the network; you must match the selected withdrawal network to the recipient’s deposit network selection.
When depositing to an exchange, select the network first, then copy the address shown for that network. When withdrawing, pick that same network.
Some deposits also require an additional memo, tag, or similar field. This is usually exchange-specific, and failing to include it can delay crediting even if the on-chain transaction itself is confirmed. Follow the deposit instructions on the receiving platform and copy any required memo/tag exactly when it is shown.
Transaction Fees and Confirmation Times
Here is another thing that can often throw a wrench into your plans if you fail to account for it. USDT transfer costs can include two different fee types. Network fees, often called gas, are paid to validators or miners for processing the transaction on the blockchain. Exchange or platform withdrawal fees are set by the service that sends the withdrawal and may not equal the exact on-chain cost at that moment.
For example, a wallet-to-wallet transfer usually requires only the network fee for the selected chain, assuming you control the sending wallet and have the required gas token. For example, if you send USDT across TRON, you must also have TRX to pay for gas; the same goes for Ethereum and ETH.
An exchange withdrawal may show a platform withdrawal fee, while the exchange handles the underlying network fee dynamics in the background. It sounds convenient until you end up with USDT in your wallet that you can’t move because the exchange paid for your gas.
Confirmation time is also network-dependent, but crediting time is not only about the blockchain. Confirmations are block-based, and a recipient platform may wait for its own required number of confirmations before showing the deposit as available. For USDT in particular, the waiting times are normally way shorter than Bitcoin’s hour to settle but it can still take a while. If your transfer is pending, check the transaction hash on the correct network explorer and confirm the recipient’s required confirmations.
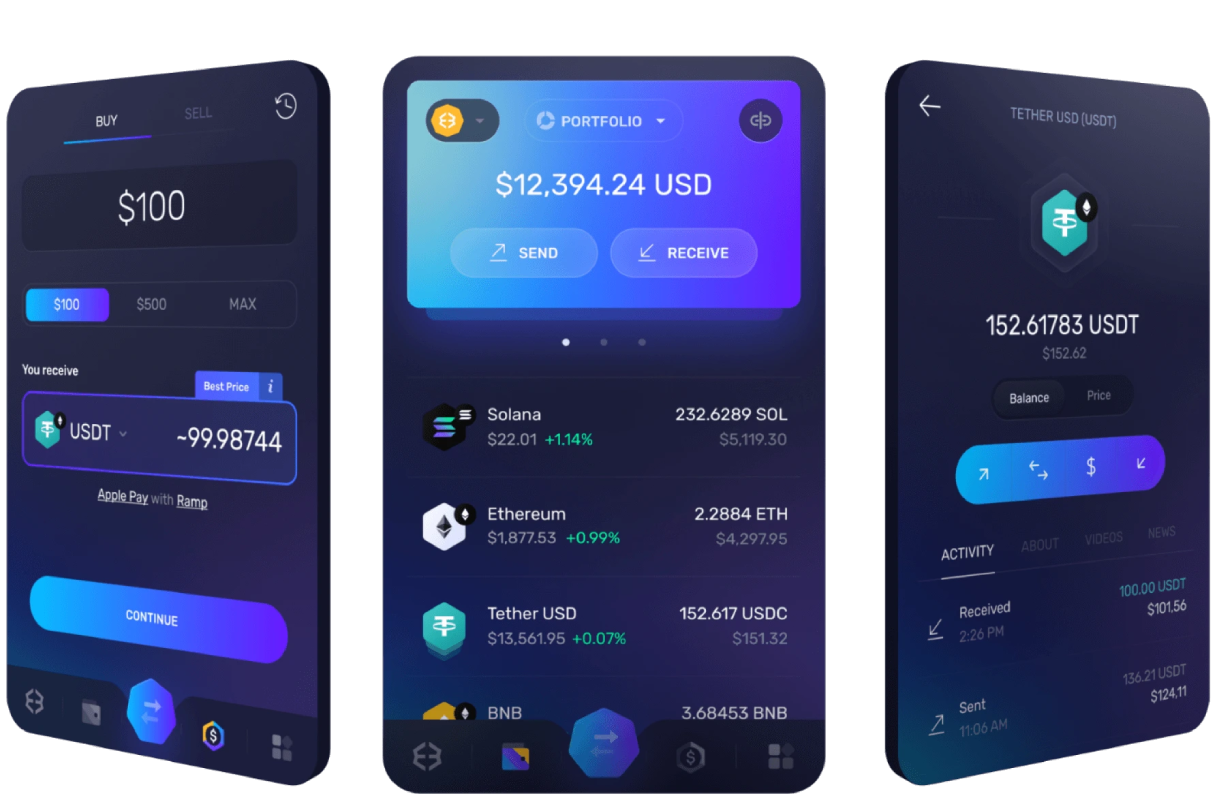
If USDT was sent but not received, work through the issue in order:
- verify the network chosen for the send;
- verify the receiving wallet address;
- check the transaction hash status on the correct chain;
- confirm that the token type on that chain is the USDT version the recipient supports;
- if the transaction is confirmed on-chain, contact the recipient platform’s support with the transaction hash.
That procedure does not guarantee recovery, but it gives support teams the information they need and helps you identify whether the issue is network mismatch, address error, token support, or platform crediting delay.
Buying, Selling, and Cashing Out USDT
Buying USDT is usually straightforward; cashing out can be more constrained. The difference comes from payment rails, verification, banking access, exchange wallet structure, and network support.
Exchange Purchases
There are two basic paths to buy USDT. If you are buying USDT with fiat via a crypto on-ramp, the sequence is:
- fund the account with a supported payment method;
- choose either a USDT market or a buy/convert tool;
- confirm the quote;
- check where the USDT settles inside the platform.
If you trade USDT by swapping cryptocurrencies, the sequence is:
- make sure you can receive the crypto in the account or wallet;
- choose the relevant crypto/USDT market or conversion tool;
- confirm the swap quote;
- verify the destination balance.
In both cases, clarify where the purchased USDT lands — Spot wallet, Funding wallet, or a general “balances” page — because that determines whether it can be traded immediately, withdrawn on-chain, or used in another platform feature.
Instant buy and convert flows are usually preferable when speed and certainty matter more than fine price control. A spot order book is usually better when the user wants to set a limit price, compare depth, or avoid accepting the first available quote.
The first-timer gotcha is that the displayed rate in an instant flow can include a spread or markup, so it may not match the spot mid-price shown on the crypto exchange.
USDT-to-Cash Off-Ramps
The first cash-out route is selling USDT to fiat on a centralized exchange, then withdrawing the fiat balance to a bank account. The user typically starts with USDT already credited to an exchange balance, or deposits it there first. The action is a trade from USDT into a fiat currency, followed by a fiat withdrawal request. The main tradeoff is compliance friction: the route is structured and bank-connected, but it may require Know Your Customer checks, supported bank rails, and withdrawal approvals before cash arrives.
The second route is using a third-party on/off-ramp widget or service integrated into a wallet or app. The user often starts from a self-custody wallet or an app balance. The action may involve sending USDT to the service or authorizing a sale flow inside the interface, after which the service sends fiat through an available payment method. The main tradeoff is availability: the flow can be convenient when supported, but region, network, payment method, and identity requirements can make it unavailable to some users.
The third route is a peer-to-peer marketplace cash-out. The user may start with USDT on an exchange P2P wallet, funding balance, or another supported internal balance, depending on the venue. The action is a sale to another participant, with fiat paid through an agreed method and USDT released according to the platform’s escrow rules. The main tradeoff is counterparty risk: pricing may be flexible, but the user must follow marketplace rules, confirm payment carefully, and avoid settling outside the protected flow.
Fees, Limits, and Verification
In addition to network fees and platform fees, here are a few more costs to keep in mind:
- Trading fees apply when buying or selling USDT through a market order, limit order, or platform conversion;
- Deposit fees are often absent for many exchange deposits, but they can still exist depending on the payment rail, asset, or service used;
- Withdrawal fees apply when moving fiat to a bank or sending crypto out to an external wallet;
- Hidden price costs come from spread and slippage.
For example, the execution price may be worse than the reference price, especially in instant conversion tools or thin markets.
A simple comparison is two users cashing out the same amount. One uses instant convert and then a bank withdrawal; the other uses a spot sell and then a bank withdrawal. Their final cash received can differ because the instant route may embed cost in the quoted conversion rate, while the spot route separates the trading fee from the execution price and may give the user more control over when the sale fills.
Verification should be mapped to what the user is trying to do. Account verification confirms the person or entity behind the account and may affect buying access, selling access, higher fiat withdrawal limits, certain payment methods, P2P participation, and bank transfer availability.
Payment method verification is separate: even if the account itself is approved, a bank account, card, or local payment channel may still need confirmation before it can be used. In practical terms, account verification may block or cap the trade, while payment method verification may block the funding or withdrawal step.
Common Cash-Out Restrictions
Real-world cash-outs can fail or stall for several reasons.
- Banking rails may not be available in the user’s region. The withdrawal method appears unavailable, and the practical move is to try another supported rail or jurisdiction-appropriate method.
- Compliance flags or holds can send a transaction to pending review. The user may need to complete verification or provide requested information.
- A name mismatch between the bank account and exchange account can cause rejection. The user should use an account in the same verified name.
- Deposit or withdrawal cooldowns after password resets, device changes, or security updates can grey out withdrawals. This usually means waiting out the cooldown.
- Asset or chain maintenance can disable a USDT route temporarily. The mitigation is to wait or use an alternate supported network if the platform offers one.
USDT Compared With Other Crypto Assets
USDT is best understood by comparing what it is trying to do against what other crypto assets are trying to do. Bitcoin floats freely. USDC targets the dollar through a different centralized issuer model. Sky Dollar and DAI targets the dollar through protocol mechanics and governance. Stablecoins overall share the goal of reference-value stability, but the stability model varies sharply.
| Asset | Primary value behavior (target vs floats) | Issuer/governance model | Primary risk type the user actually experiences | Common use in a portfolio/workflow | Typical “failure mode” in plain language |
|---|---|---|---|---|---|
| USDT | Targets dollar value | Central issuer | Issuer, redemption, and counterparty risk | Trading base, payments, transfers | Discount during stress or limited redemption access |
| Bitcoin | Floats freely | Decentralized network | Price risk | Long-term hold, directional cryptocurrency exposure | Volatility drawdowns |
| USDC | Targets dollar value | Central issuer | Issuer and compliance risk | Payments, trading, regulated-counterparty workflows | Redemption or transfer friction |
| DAI / Sky Dollar | Targets dollar value | Crypto-backed with protocol governance | Smart-contract and parameter risk | DeFi collateral, borrowing, liquidity | Protocol changes or collateral stress |
| Stablecoins overall | Target reference value | Varies by model | Model-specific stability risk | Settlement and cash-like workflows | Price target weakens when confidence or liquidity breaks |
USDT vs Bitcoin
For a trader who needs a dollar-like unit to enter and exit positions quickly, USDT usually fits the workflow better than Bitcoin. It is commonly used as a pricing and settlement asset inside crypto markets, especially when the goal is to move between trades without taking on the full price movement of another cryptocurrency.
For a holder who wants exposure to crypto price upside and a long-term thesis, Bitcoin fits a different intent. Bitcoin is not designed to stay near a dollar reference; it floats based on market demand, liquidity, macro sentiment, network confidence, and its own market capitalization.
In short, these assets solve different problems: USDT is used for pricing and settlement inside crypto markets, while Bitcoin is used for directional exposure.
What you give up when you choose each: With USDT, you give up upside because the point is stability rather than appreciation, and you still accept stablecoin-specific risks around issuer trust, redemption conditions, liquidity, and counterparty risk. With Bitcoin, you get exposure to potential upside, but you also accept volatility, drawdowns, and the practical problem that it is not a stable unit of account for most day-to-day pricing.
USDT vs USDC
USDT and USDC are both centrally issued fiat-backed stablecoins, but users often compare them through practical tradeoffs rather than only through design labels.
The first axis is issuer, redemption, and compliance posture. Both depend on centralized entities, but counterparties may view their issuer structures, access rules, and compliance positioning differently. This is a user-choice factor, not legal advice.
The second axis is support where you actually transact. USDT may be more useful where your trading pair, transfer route, or payment counterparty prefers it; USDC may be more useful where your app, DeFi protocol, network, or business workflow supports it more directly.
The practical step is simple: check availability where you transact before assuming either stablecoin will work.
The third axis is perceived risk tradeoff. Some users focus on issuer concentration and redemption access; others focus on transparency expectations, reporting practices, and how comfortable a counterparty is with a specific issuer. Avoid treating USDC vs USDT as automatically “safe” in all contexts, because the relevant risk depends on the venue, chain, custody setup, and purpose.
A practical selection heuristic is:
- if your venue or liquidity is deepest in USDT, use USDT for that specific workflow;
- if a regulated-custodian narrative or USDC preference is a requirement for your counterparty, USDC may be preferred;
- always verify the exact network and token supported for deposits and withdrawals before sending funds.
USDT vs DAI
USDT and DAI (and its newer iteration Sky Dollar, USDS) differ most clearly in the mechanism behind their stability. DAI’s stability depends on overcollateralization, protocol parameters, liquidation rules, and governance decisions inside its system. USDT’s stability depends more on issuer reserves, redemption access, and market liquidity around the token.
That mechanism difference changes the user-facing risk. DAI exposes users more to smart-contract risk, governance risk, oracle assumptions, and parameter changes that can affect how the protocol behaves under stress. USDT exposes users more to issuer, counterparty, and redemption access risks, especially when confidence in centralized support or liquidity weakens.
The gotcha is that neither label removes risk. DAI is not “risk-free” just because it targets $1, because the protocol still depends on collateral behavior and governance choices. USDT is not “the same as USD” just because it is often priced near $1, because it remains a token with issuer and market-structure dependencies.
Choose based on intent first. If you need pricing and settlement, a stablecoin such as USDT, USDC, or DAI may fit better than Bitcoin. If you want exposure to crypto price movement, Bitcoin is the clearer directional asset. Then choose between centralized and decentralized stablecoin models based on your risk preference, and finally confirm where liquidity and support exist for your specific venue and chain.
Conclusion
USDT is a dollar-referenced stablecoin issued by Tether and widely used as a trading base, transfer asset, volatility parking tool, and DeFi liquidity component. Its usefulness comes from the combination of dollar-like pricing and crypto-native transferability.
However, that convenience comes with dependencies. USDT relies on issuer confidence, reserve disclosures, redemption access, exchange liquidity, network support, and correct user execution. It is not a bank deposit, not automatically insured like a bank balance, and not interchangeable across networks without the right bridge, swap, or exchange-supported path.
Browse the ChangeHero blog to learn more about the latest crypto news, projects, and platforms. And for quick bite-sized updates, follow us on social media: Twitter, Facebook, and Telegram.
Frequently Asked Questions
Is Each USDT Really Backed by 1 US Dollar?
No, “backed” does not mean each USDT corresponds to a segregated $1 bill in an individual account. The strict distinction is between the $1 price target USDT is designed to track and Tether’s reserve backing claim about assets supporting the token.
To evaluate backing, look for reserve disclosures or attestations and check what they say about the assets behind USDT.
Can the Price of USDT Drop Below $1?
Yes, USDT can trade below $1 in the market. A brief deviation can happen through order books, liquidity gaps, market stress, or redemption access frictions, while a sustained discount suggests a deeper confidence or depegging concern rather than a normal price wobble.
Compare prices across venues first, then consider whether liquidity or redemption constraints are affecting the market.
Why Is USDT Used Across Different Blockchains?
USDT is used across different blockchains because users choose networks based on fees, speed, and ecosystem compatibility.
The nuance is that “USDT” is a token representation that exists as separate instances on each blockchain, so USDT on one network is not automatically interchangeable with USDT on another. Before transferring, confirm the sender’s withdrawal network matches the receiver’s supported deposit network.
How Do You Convert USDT to Cash?
You convert USDT to cash by selling it through an off-ramp and withdrawing the resulting fiat balance.
If USDT is already on an exchange, you may be able to sell it there. If it is in a self-custody wallet, you may need to transfer it to a venue that supports selling USDT on that same network before withdrawing fiat.
Check fees, limits, and KYC requirements before sending USDT to an off-ramp so you do not get stuck mid-process.