
Crypto Futures Last Price vs. Mark Price — Meaning Explained

Key Takeaways
- 🏷️ Last Price is the most recent executed trade price on a specific venue’s order book. It is a trade print, not a fair-value estimate;
- 🏷️ Mark Price is a calculated reference used for unrealized PnL, margin health, and liquidation checks in derivatives trading;
- 🏷️ In perpetual futures and futures contracts on a crypto exchange (CEX), last price and mark price can diverge because they are built for different purposes;
- 🏷️ Order execution follows the order book and last price stream. Liquidation and unrealized PnL usually follow mark price.
Disclaimer
This article is for educational purposes only and does not constitute financial, investment, or trading advice. Futures and perpetual futures involve leverage, liquidation risk, funding costs, and platform-specific rules. Always confirm how your own crypto exchange calculates Mark Price, trigger price, liquidation price, and unrealized PnL before placing trades.
Your chart shows one number, but the price your exchange uses to calculate liquidation, unrealized PnL, or trigger a stop order can be entirely different. This mismatch becomes especially jarring in fast-moving or thin markets, where a candle wick may look like it crossed your liquidation level even though the reference price that matters never actually touched it.
This confusion is specific to derivatives trading — perpetual futures and futures contracts on a crypto exchange (CEX) — where both prices often sit side-by-side on the trading interface with very little explanation of why they diverge.
By the end of this guide, the distinction should be practical rather than theoretical: which price governs order execution, which one drives your unrealized PnL display, and which one the exchange actually references for liquidation and trigger mechanics.
Last Price and Mark Price Definitions
A useful way to start is to separate the trade tape from the risk engine. In particular, last price belongs to the trade tape, and mark price to the risk engine.

Last Price
Last price is the most recent executed trade price for a given contract on a specific venue’s matching engine. It is not a midpoint, not a quote, and not an average. It is a purely transactional data point: last price can only change when a trade actually prints on that order book.
If the best bid or ask moves but no trade occurs, last price does not update. This is why it can appear “stuck” in quiet markets and then jump abruptly when the next execution finally happens.
Mark Price
Mark price, by contrast, is a calculated reference designed to approximate fair value for risk controls like unrealized PnL and liquidation systems. Rather than reflecting a single trade, it is typically derived from external spot/index inputs plus a funding or basis adjustment.
That means mark price is not necessarily a tradable price. It can update even when no trade prints at all, because it is reading broader reference inputs rather than waiting for the local order book to produce the next fill.
Futures and Crypto Derivatives Context
Derivatives contract trading needs more than one reference price because execution, valuation, and liquidation are not the same function.
- Execution answers: what price did I actually trade at?
- Risk and valuation answer: what is my position worth right now?
- Liquidation logic answers: has my margin fallen below the required threshold?
A single price cannot cleanly serve all three roles without creating exploitable distortions.
This is also a contract-level versus market-level distinction. Last price is purely local to that specific exchange’s order book and reflects only what happened there. Mark price is anchored to external or aggregated reference inputs, making it less susceptible to the quirks of any single venue’s order flow in broader cryptocurrency markets.
Two different numbers on the futures trading screen does not mean one of them is “wrong.” They are not competing answers to the same question. They are outputs from different internal engines built for different jobs.
The volatility gap in these metrics is exactly why a separate calculated reference price exists in derivative markets: a momentary, thin-book distortion in last price should not automatically be treated as the real value of the contract.
Mark Price vs Last Price: Key Differences in Futures Trading
So far we have established the definitions. The next step is understanding where each price is actually used, because this is where most practical trading errors happen.
Trade Execution
Order execution is tied strictly to the contract’s order book and matching engine, not to the calculated reference price.
When you place a market or limit order, it interacts with existing bid/ask liquidity on that specific venue. Your fill price, and any slippage you experience, tracks the last price stream because it is, by definition, the most recent matched trade.
Mark price plays no role here: it is not an executable quote, no order can fill “at Mark Price” by default, and the matching engine has no mechanism to route trades against it.
If you are trying to predict where an order will actually land, the order book depth and recent prints are what matter. Mark price is simply not part of that mechanical channel.
Unrealized PnL
Unrealized PnL (or P&L, profit and loss) works differently. It is typically marked to mark price, not last price, meaning your position’s displayed value updates continuously based on that calculated mark-to-market reference rather than on individual trades happening on the book.
Realized PnL, by contrast, is only locked in once an order actually executes — when you close all or part of a position at a specific traded price.
Here is the point that trips up many traders: you can watch recent trades print at favorable levels on the tape and still see negative unrealized PnL on your position. That is because the platform is referencing Mark Price, which can sit meaningfully apart from what the order book is doing at that moment.
Price Divergence
Divergence between last price and mark price is not random noise. It usually traces back to several concrete causes:
- Thin liquidity and price impact. A single large order can push a last-trade print away from where the broader market is actually trading, simply because there was not enough depth to absorb it cleanly.
- Fast volatility. Index inputs feeding into mark price can lag or average over a short window, so it temporarily smooths out a move that last price already reflects in full.
- Perpetual contract basis. In perpetual contracts specifically, basis and fair-value adjustments built into the mark price formula can create a persistent small gap even in calm conditions.
In any case, this divergence is a signal about microstructure noise as opposed to a broader market consensus.
For example, say a contract is trading near $100 and a thin patch of liquidity lets one order sweep the book, briefly printing a last price of $106. An order placed right after that sweep can still execute near $105–106, since fills follow the order book, not a calculated reference.
Mark price, meanwhile, might barely move from $100.20, because it is anchored to broader inputs rather than that single print. Your unrealized PnL display stays calm even as the trade tape looks like it just spiked.
Price Calculation Methods
The cleanest way to understand Last Price vs Mark Price is to look at how each number is formed. We have already briefly gone over last price but mark price deserves a closer look.
Last Price Formation
As the name is meant to communicate, last trade print does not come from a quote update. It comes from an actual order execution.
The mechanical sequence looks like this:
- A market or limit order is submitted;
- The matching engine checks the order book for a crossing counter-order;
- A buy and sell meet at an agreeable price;
- The engine records that execution — price and size — as a fill;
- That fill populates Last Price on your screen.
Critically, the UI only refreshes this price when a trade actually prints.
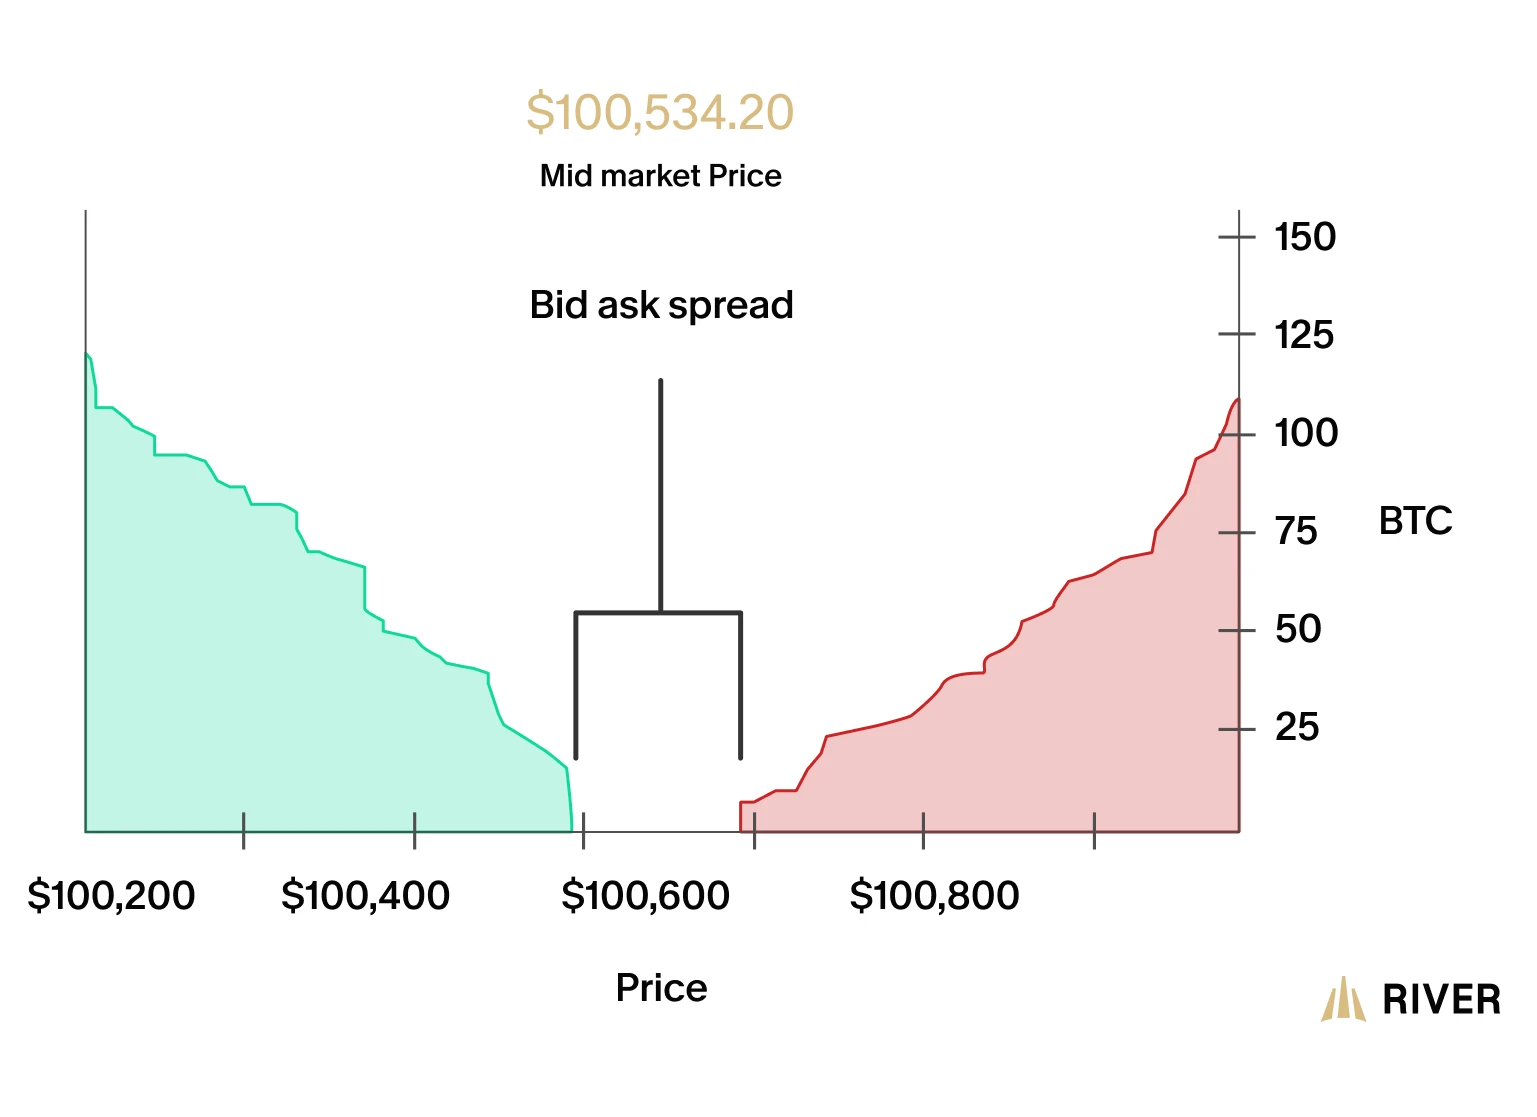
There is also mid price, a midpoint between the best bid and best ask. It can move continuously as quotes update. Last price is strictly transactional.
Mark Price Formula Components
To keep the rest of this article consistent, it helps to break Mark price into three functional building blocks rather than treating it as one opaque number.
- Index Price — the external anchor; a composite spot-market reference that mark price is built around.
- Premium/basis or funding-derived term — the adjustment; captures the gap between where the derivative is trading and where spot sits, correcting for structural premium or discount.
- Clamp/band or smoothing mechanism — the guardrail; limits how far mark price can drift from index price, preventing a single distorted input from producing an extreme valuation.
Anchor, adjustment, guardrail — that three-part split is the mental model to carry forward.
Index Price Inputs
And now it’s time to address what index price is. In practice, an index price is often a weighted average of spot prices pulled from roughly 4–10 major crypto exchanges, rather than a single venue’s order book. Aggregating across venues protects against one exchange’s idiosyncratic order flow skewing the reference, but it only works if the inputs feeding the average are reliable.
That is where input hygiene rules come in. If a single feed is stale, manipulated, or simply thin, an unweighted average would let it distort the entire index. Exchanges therefore layer in outlier and availability controls.
A common approach combines three rules:
- Any input source that deviates more than 5% from the median gets capped or floored at that ±5% boundary until it returns within range;
- Any input source that fails to send a price update for more than 10 seconds is excluded from the calculation entirely;
- Index weights are frequently based on each exchange’s trading volume over the past 4 hours, so venues with deeper, more active markets carry proportionally more influence.
Together, these rules mean the index price is not just “an average.” It is an average actively filtered against stale feeds and outlier venues before it ever reaches the mark price formula.
Fair Value Adjustments
Derivatives contracts can trade at a premium (higher) or discount (lower) to spot due to funding dynamics or basis. Demand for leverage on one side of the market pushes the perpetual or futures price away from where the underlying asset is actually trading.
Fair value adjustments exist to correct for this. Rather than letting risk systems mark positions purely off a derivative price that might be temporarily inflated or depressed, the adjustment nudges mark price back toward what the market’s fair value genuinely looks like once the basis is accounted for. This is sometimes referred to as a premium index component — it specifically measures that derivative-to-spot gap so it can be netted out.
You will typically notice this adjustment mattering in two situations:
- When funding rates are elevated or a premium persists over time, since that is exactly when the derivative price and fair value diverge most;
- During stressed markets, where perpetuals can briefly decouple from spot as liquidity thins and order flow becomes one-sided.

As a non-obvious guardrail, some exchanges also clamp mark price within roughly 2–5% of index price specifically to prevent extreme divergence during these stressed windows. This is a protective mechanism some venues implement, not a universal standard across every crypto exchange.
Putting it together: say index price sits at $100, based on that weighted, outlier-filtered average across several spot exchanges. A thin-book sweep on one venue prints a last price of $106 — a real, executed trade, but isolated to that order book. The fair value adjustment for basis/funding on this contract is small, say +$0.20, reflecting a mild ongoing premium.
Mark price ends up around $100.20. It is much closer to index price than to the $106 print because it is built from the index anchor plus that modest adjustment, not from the last trade. The practical implication is simple: your unrealized valuation stays anchored near fair value even while the trade tape momentarily looks far more dramatic.
Liquidation and Risk Management
This is where the distinction stops being cosmetic. In leveraged derivatives, the wrong reference price can make the screen look safer — or more dangerous — than it really is.
Mark Price Liquidation Logic
Liquidation is not decided by watching the tape. It is decided by a background health check that runs continuously against your position.
The pipeline is straightforward:
- The system calculates your current margin health;
- It compares your account balance and maintenance margin requirement against a reference price;
- That reference price is mark price, not last price;
- As mark price moves, your margin ratio is recalculated in real time;
- The moment mark price crosses your liquidation price, the position becomes liquidatable and forced closure begins.
At least, liquidations are generally triggered by mark price rather than much more flexible last price. The exchange is checking margin sufficiency against a calculated fair-value number, not against whatever just printed on the order book.
Wick Protection
A “wick” in this context is a brief, sharp excursion in last price caused by thin liquidity or price impact. One order sweeps through a shallow order book, prints an extreme price for a moment, and then the market snaps back once that isolated trade clears.
Mark price exists precisely as a guardrail against this kind of noise. Because it is anchored to broader index inputs rather than a single print, it stays largely unmoved by a wick even while the trade tape looks dramatic.
If liquidation logic used last price as its reference, a few-second spike could be enough to forcibly close a position that was never actually in danger. Using mark price instead, the position rides through the wick untouched because the calculated reference barely registered the disturbance.
Stop-Loss and Take-Profit Triggers
Here is when the distinction goes further than two display numbers. Trigger conditions for a stop-loss order or take-profit are not just a checkbox. Choosing last price or mark price as the trigger input changes what kind of risk you are exposed to.

- Last Price as trigger
- Protects you from missing a move that is actually tradable on the order book, since it fires on real executed prints;
- Failure mode: a thin-book wick can trip the trigger on a price that never reflected genuine market value.
- Mark Price as trigger
- Protects you from being triggered by a transient, thin-liquidity spike that does not represent fair value;
- Failure mode: the trigger can fire late or early relative to what is actually tradable in the order book, since Mark Price may sit apart from executable prices at that moment.
Say mark price sits at 0.0300 while last traded price briefly dips to 0.0297. A stop-loss set to trigger on last price would fire here, since 0.0297 breached the threshold on the tape even though mark price never moved off 0.0300. A stop-loss set to trigger on mark price would stay untouched, since the reference the system actually checks has not crossed the level at all.
The takeaway: which price you choose as your trigger source has to match what you are actually trying to protect against.
Thin Market Manipulation
Thin liquidity creates a structural vulnerability. When an order book is shallow, it does not take much size to move last price meaningfully away from where the broader market is actually pricing the asset. A handful of trades — sometimes even one — can print an off-market last price that looks like a real move on a chart but reflects almost no genuine trading interest.
Two mechanisms discussed above are directly exposed to that distortion:
- Last price-based triggers can be tripped by a manufactured print;
- Chart perception can mislead anyone reading the tape as if it represents consensus value.
Mark-based liquidation checks are comparatively insulated, since they are anchored to aggregated index inputs rather than a single venue’s thin order book.
The Mango Markets incident is a cautionary vignette worth keeping in mind here: an attacker manipulated the price of a low-liquidity asset used as collateral, inflating its value enough to borrow roughly $116 million against that distorted price before the market reverted and the collateral’s real worth collapsed.
It is a stark illustration of why reference-price integrity is not a minor technical detail. When the number feeding risk systems can be pushed away from genuine market value, the exposure that accumulates on top of it can be enormous — and can revert just as fast once the distortion clears.
Related Reference Prices
Last Price and mark price are the main pair traders focus on, but they are not the only reference prices on a derivatives interface. Close price, index price, and settlement price can all appear in the same environment, which is why label discipline matters.
Last Price vs Close Price
Last price and close price answer two different questions, even though both show up as “the price” in different corners of the same interface.
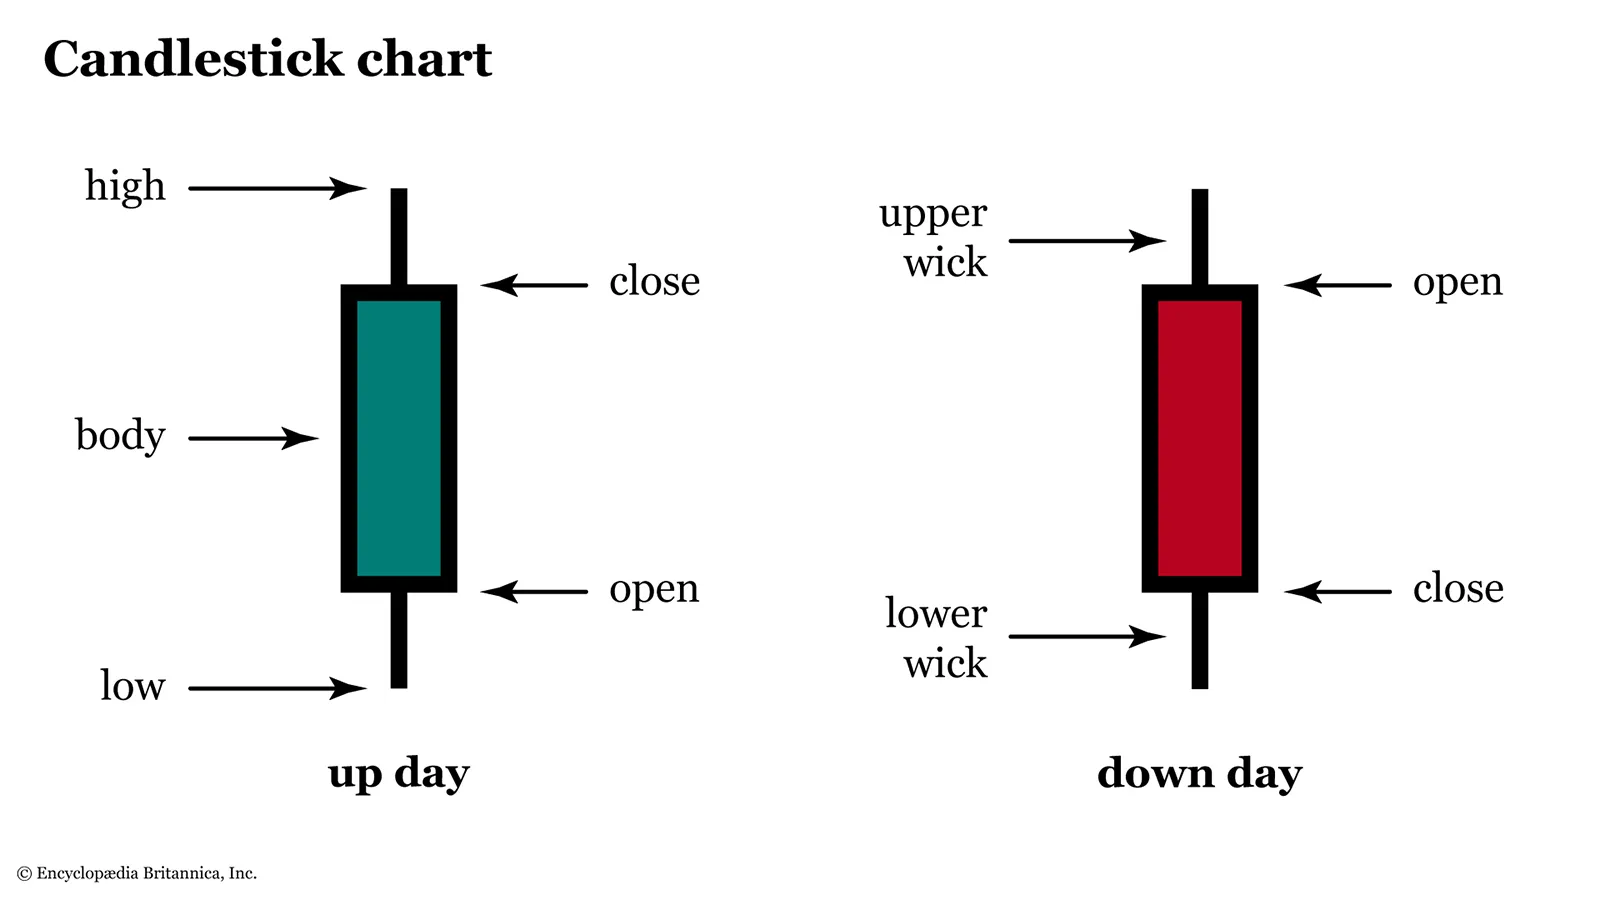
Unlike last price, which updates continuously as long as trading is active, close price, by contrast, is a snapshot: it is the last price recorded at the boundary of a specific period, and it is what most daily statistics — percentage change, candle close, day-over-day performance — are actually built from.
“Close” is entirely timeframe-dependent. A 1-minute chart closes 1,440 times a day, a 1-hour chart closes 24 times, a 1-day chart closes once. None of these involve a fair-value calculation. Each is simply whatever last price happened to be at that period’s cutoff. “The close” is really shorthand for “the close of whichever timeframe you are currently viewing.”
Imagine the same contract on the same crypto exchange, viewed on a 1-hour chart and a 1-day chart at the same moment. The 1-hour candle just closed at $102.40, based on the last trade printed exactly at that hour’s boundary. The daily candle, still in progress, is tracking a different close value entirely, since its boundary has not arrived yet.
For dated futures, there is a related term worth distinguishing from close price: settlement price. Where close price is simply the last traded price at a chosen chart interval, settlement price is typically a formally calculated value used to settle contracts at expiry or determine daily mark-to-market obligations. It is closer in spirit to a fair-value calculation than to a raw trade print.
Mark Price vs Index Price
Index Price and Mark Price get treated as interchangeable more often than they should be, but they play distinct roles.
- Index Price is the external anchor. It is a composite reading built from spot markets outside any single venue’s order book, meant to represent where the underlying asset is actually trading.
- Mark Price is the exchange’s risk/valuation reference. It starts from the Index Price and then layers on internal adjustments and guardrails — basis correction, smoothing, drift limits — so the number stays usable for margin and PnL calculations even when index inputs get noisy.
- On most interfaces, these show up under different labels. You might see “Index,” “Mark,” “Fair,” or “Reference” depending on the platform’s terminology, but the underlying split is usually the same: one number tracks external spot, the other is the exchange’s adjusted version of it.
A simple interpretation rule helps when the two numbers pull apart. If index price is drifting steadily while mark price moves by a noticeably different amount, that gap usually reflects a basis or funding adjustment being applied, or an internal guardrail limiting how far mark can move in one step.
If instead last price is jumping around while both index and mark stay essentially flat, you are likely looking at order-book microstructure noise — a thin trade or a brief imbalance — rather than any real shift in the underlying value the exchange is tracking.
Charting and Market Session Context
Most price charts you encounter on a derivatives interface are plotting the last price stream. Each candle is built from actual trade prints on that venue’s order book.

Risk widgets, on the other hand, often display mark price separately, since that is the number driving margin and PnL. This distinction matters specifically for reading wicks: a sharp wick on a last price chart can reflect a real, executed trade that swept thin liquidity, even if the mark price line sitting beside it barely moved. The chart is not wrong. It is just showing you a different reference than the one your risk metrics are built on.
Before treating any sudden chart move as meaningful, a short label-level check can save you from misreading it:
- Is the chart currently plotting last price or mark price?
- What timeframe defines the candle you are looking at, and does that match the “Close” value you are comparing against?
- Is the instrument a perpetual contract or a dated future, since that affects whether a settlement price applies at all?
- Does the move show up consistently across multiple timeframes, or only on the one you happen to have open?
None of these checks require digging into platform-specific settings. They are label-reading habits that keep you from mixing up which reference price a given chart or widget is actually built on.
Trading Use Cases
Knowing the definition is useful. Applying it under pressure is the real test. In practice, last price and mark price matter most during order entry, position monitoring, and volatility events.
Order Entry and Exit
The first step — selecting entry or exit levels — happens on the chart, where you are reading price action and picking a level you want to transact at. The second step — assessing fill quality — happens in the order book, where actual bid/ask liquidity determines whether your order gets filled at, near, or far from that chosen level.
A simple three-point checklist keeps these two steps from blurring together:
- Last price = the trade tape. It shows where trades have actually printed and where fills tend to cluster, since it is built from real executions rather than a calculated estimate.
- Order book = your slippage reality. The visible bid-ask spread and depth at each level tell you how much size can be absorbed before your fill price drifts away from what you expected. This is where slippage risk actually lives, not on the mark price line.
- Mark price = a context check, not a target. It tells you whether the current tape looks reasonable relative to broader fair value, but no order can execute “at mark.”
Here is how skipping that distinction can go wrong. A trader sees mark price sitting at a level that looks attractive and places a limit order right at that price during a brief divergence between last price and mark price. The order sits unfilled for several minutes, because the order book simply is not offering liquidity there.
The actual bid-ask spread at that moment is clustered closer to the last price stream, several ticks away from mark. The lesson is straightforward: executable levels need to be anchored to where the order book actually has depth and where last price is printing. Mark price stays useful as a fair-value reference to judge whether the tape itself looks off-market.
Position Monitoring

Once a position is open, the screen is showing you several different things at once. Knowing which one to check when something “looks wrong” saves a lot of unnecessary panic.
Think of it as an on-screen interpretation map:
- Unrealized PnL is a mark-to-market figure. If it suddenly looks off relative to what the chart is doing, check mark price first, since that is the number PnL is actually built from.
- Liquidation proximity / margin health is a risk-engine reference. If your margin indicator looks alarmingly close to threshold, check mark price movement and your maintenance margin requirement before assuming the chart’s candle wick is the cause.
- The chart itself is, on most platforms, plotting the last price stream. If a candle spikes sharply, check whether that move is echoed in Mark Price before treating it as a risk event.
That last point creates a useful split between false alarms and real ones.
If last price jumps sharply while mark price stays essentially flat, that is typically microstructure noise — a thin print or a brief imbalance on one venue’s order book — and it does not necessarily mean anything about your actual exposure. If mark price itself moves meaningfully, that reflects a broader shift in fair value. That is the number worth paying attention to when you are scanning your position for real risk.
The practical habit is simple: when something on screen looks scary, glance at whether mark moved too before reacting. If it did not, you are likely looking at tape noise, not a genuine change in your position’s standing.
Volatility Scenarios
Last price and mark price often diverge in distinct, recognizable patterns depending on what is driving the move.
- Thin-liquidity wick: Last price spikes or drops sharply on a single sweep through a shallow order book, then snaps back almost immediately. Mark price barely reacts, since it is anchored to broader inputs rather than one isolated print. Do not misread this: a dramatic wick on the chart does not mean fair value moved. It usually means one order briefly outran available depth.
- Fast trend with continuous prints: Last price moves steadily in one direction as trade after trade prints in the same direction, reflecting genuine, sustained order flow rather than a single outlier. Mark price tends to follow, though often with a slight lag, since it is smoothing across index inputs rather than reacting to each individual trade. Do not misread this either: the lag does not mean mark is “wrong” or behind reality. It means it is deliberately less reactive to any single print by design.
- Index-driven move where Mark leads: During quiet trading on a particular venue, an index-wide shift can cause mark price to update meaningfully even while the local trade tape stays sparse and last price barely changes. A still chart does not guarantee a stable position. If mark is moving off broader index inputs, your margin health and unrealized PnL can shift even without fresh local prints.
The point is, an eye-watering last price move is not automatically evidence that your underlying exposure has deteriorated. Checking mark price is what tells you whether the volatility is cosmetic or consequential.
Conclusion
The distinction between last price and mark price is not a technicality you can afford to skip. It is the difference between reading your risk correctly and misjudging it entirely.
Last price tells you what just happened on a specific order book: a real, executed trade, local to that venue, and nothing more. Mark price tells you something different: what the broader market currently agrees your position is worth, once index inputs and fair-value adjustments are factored in.
Neither one is “the” price. They are both accurate answers to different questions.
Read more about crypto trading and the variety of digital assets in ChangeHero blog — our team always has insights to share. Keep up to date by following ChangeHero on Telegram, X (Twitter), and Facebook.
Frequently Asked Questions
What Are Last Price And Mark Price?
Last price is the most recent executed trade price on a specific exchange’s order book, while mark price is a calculated reference used for risk metrics like unrealized PnL and liquidation checks.
The key clarifier is this: last price is a tradable print that only changes when an actual trade occurs, whereas mark price is a derived number that can move even without any new trade taking place.
Both appear side-by-side on most derivatives interfaces, but they answer different questions rather than competing to be “the” correct price.
Why Do Exchanges Use Mark Price For Liquidation?
Exchanges use mark price for liquidation because it is anchored to broader index inputs rather than a single trade, making it far less prone to momentary distortion.
The design intent is straightforward: a brief off-market print — a wick caused by thin liquidity — should not be able to force a liquidation that would not hold up against genuine market value.
By checking margin health against this calculated reference instead of the raw trade tape, exchanges reduce the odds that a fleeting, unrepresentative price triggers a forced closure.
Does Liquidation Happen At Mark Price Or Last Price?
The liquidation trigger check is typically based on mark price, not last price, since it is the number exchanges use to continuously assess margin sufficiency.
However, it is worth separating the trigger reference from actual execution. Once a position is flagged for liquidation, the closing trades themselves still happen on the order book. In other words, the decision to liquidate and the mechanics of closing the position rely on two different processes.
When Should Traders Use Last Price Vs Mark Price?
Use last price when you are focused on execution — reading the trade tape to understand where fills are actually happening and where slippage risk lives.
Use mark price when you are checking risk or status metrics, such as unrealized PnL or how close your position sits to its liquidation threshold, since that is the number those systems are actually built from.
Because conventions can vary, it is worth confirming which reference your platform uses for trigger price purposes before assuming your stop-loss or liquidation logic behaves the way you expect.