How to Short Bitcoin in 2026? Beginner’s Guide


Key Takeaways
- 🔘 Shorting Bitcoin means taking a position that benefits if BTC falls, but the risk profile depends entirely on the instrument: futures, margin spot shorting, put options, or inverse Bitcoin ETFs.
- 🔘 Futures and perpetual contracts offer direct downside exposure but introduce leverage, funding rates, liquidation risk, and continuous position management.
- 🔘 Margin trading and spot shorting use a loan-and-sale structure: borrow BTC, sell it, buy it back later, and repay the principal plus interest.
- 🔘 Put options cap maximum loss at the premium paid, making them structurally cleaner for traders who want bearish exposure without liquidation risk.
- 🔘 Inverse Bitcoin ETFs such as BITI can be accessed through a brokerage account, but their daily reset makes them better suited to short holding periods than long bearish theses.
- 🔘 Platform access matters as much as strategy choice. CME, Kraken, Coinbase Advanced, Robinhood, Binance, and traditional brokerage accounts all differ in eligibility, product availability, and account requirements.
Disclaimer
Nothing in this guide is investment advice, financial advice, legal advice, or a recommendation to short Bitcoin. Shorting BTC can lead to substantial losses, especially when leverage, margin, liquidation, borrow fees, or derivatives are involved. Always verify product availability, account permissions, and local regulations before trading. When in doubt, the platform’s own risk disclosures, margin rules, and order confirmation screens are the primary source of truth.
Even during “Uptober,” when historically Bitcoin shows gains (read more about it in our article on Bitcoin seasonality), there is a chance to make some profit on betting against it. Shorting Bitcoin means taking on selling exposure now with the intent to buy back later at a lower price. However, the method you choose determines exactly how you can lose money: through liquidation, a margin call, a paid premium, borrow interest, funding rates, or ETF tracking decay.
There are four main routes:
- Futures and perpetual contracts
- Margin trading and spot shorting
- Put options
- Inverse Bitcoin ETFs
Each route gives you bearish exposure, but they are not interchangeable. The mechanics, costs, account requirements, and worst-case outcomes differ enough that choosing the wrong vehicle can turn a correct market view into a poor trade.
Shorting BTC Futures and Perpetual Contracts
A futures short is a derivatives position that profits when Bitcoin falls. A perpetual swap works similarly but has no expiry date, which is why it relies on funding payments to keep the contract price anchored to spot.
Short Position Mechanics
Before you open a short position, you’d need to decide on the vehicle, for one. A perpetual swap has no expiry date, so the position stays open as long as margin requirements are met. Because there is no settlement date to force price convergence, perpetuals use periodic funding payments exchanged between longs and shorts.
A dated futures contract, by contrast, has a fixed expiry. The position settles or must be rolled into a new contract at that date, and there is no perpetual-style funding mechanism. In simple terms: a perpetual is a continuous position with funding, while a dated future is a fixed-term position with settlement.
Opening a short on a crypto exchange follows a fairly consistent sequence regardless of the platform:
- Select the contract — choose the Bitcoin perpetual swap or a dated futures contract from the exchange’s derivatives menu.
- Choose margin mode — decide between isolated margin, where risk is contained to this position, or cross margin, where account collateral is shared.
- Set leverage — pick a multiplier such as 5×, 10×, or 20×. This determines how much collateral backs your notional exposure.
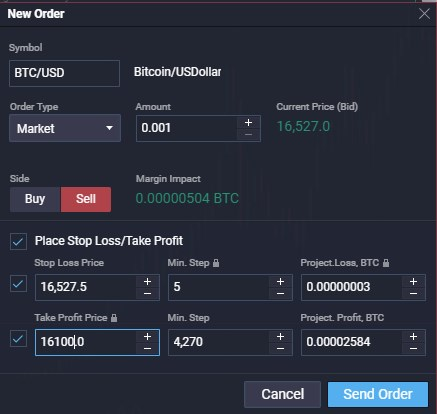
- Place the sell/short order — submit a market or limit order to open the short and establish your entry price.
- Monitor mark price vs. last price — these prices serve different purposes and should not be treated as interchangeable.
- Manage the position — add or remove margin, adjust leverage, or set take-profit and stop-loss orders as the market moves.
- Close by buying back or using Reduce-Only — exit by purchasing back the equivalent contract size, making sure you do not accidentally open a new position in the opposite direction.
Three prices matter once a short is live:
- Entry price — your P&L baseline.
- Mark price — the price most exchanges use for liquidation and auto-deleveraging (ADL).
- Last/trade price — the most recent executed trade price on that specific order book.
Conflating them is a common mistake. The mark price is usually smoothed or index-derived to reduce manipulation risk, while the last price can wick sharply during low liquidity. For further explanation, see the article on last price vs mark price. Practically, monitor mark price for liquidation risk and last price for execution context.
Closing a short and reversing it are also different actions. Closing means buying back the same contract size you sold, flattening exposure to zero. Reversing means buying back more than your short size, crossing through zero and opening a new long position. If your intention is only to exit, a Reduce-Only order is the cleaner tool. It can only shrink or close an existing position; it cannot flip you into a long by accident.
Leverage and Liquidation Exposure
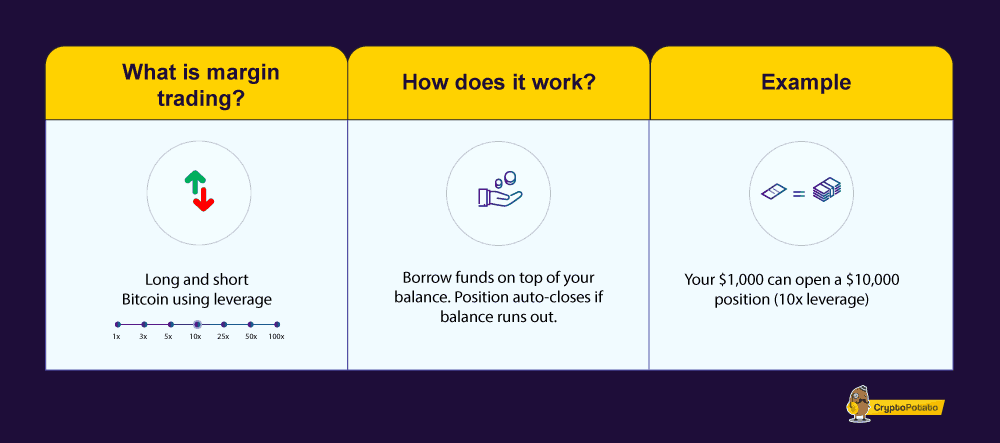
Speaking of leverage, the fact it amplifies both gains and liquidation risk by shrinking the distance between your entry and the point of forced closure is a common warning for a reason.
Consider a trader with $1,000 in collateral opening a Bitcoin short at $60,000:
- At 5× leverage, the notional position size is $5,000, or about 0.083 BTC. A roughly 18–20% adverse move against the short — price rising toward 72,000 — would erode the collateral enough to approach liquidation, assuming no added margin.
- At 20× leverage, the same $1,000 controls a $20,000 notional position, or about 0.33 BTC. Here, an adverse move of only roughly 4–5% — price rising to about 63,000 — could trigger liquidation.
The takeaway is straightforward: higher leverage does not just increase potential profit. It compresses the distance between ordinary volatility and forced exit.
Several variables shift how close a futures or perpetual short sits to liquidation:
- Maintenance margin — the minimum equity required to keep the position open.
- Unrealized P&L — losses reduce available margin in real time.
- Fees and funding accrual — trading fees and funding payments can slowly drain margin.
- Margin mode — isolated margin contains risk to one position, while cross margin draws on the full account balance.
Think of isolated versus cross margin as defining the blast radius of a liquidation. Isolated margin limits losses to the capital assigned to that specific short. Cross margin can delay liquidation by using more available collateral, but it can also expose the entire portfolio if the market turns sharply.
A reasonable rule of thumb:
- Use isolated margin when testing a position size or taking a higher-leverage short you want contained.
- Use cross margin only when actively managing multiple positions and when you understand the wider account exposure.
Finally, liquidation is not a stop-loss. A stop-loss is a voluntary order you control. Liquidation is a forced market action triggered by the exchange’s risk engine. Because forced closures often execute during the same volatility that caused the margin shortfall, the realized exit price can be meaningfully worse than the mark price that triggered it.
Bitcoin Margin Trading and Spot Shorting
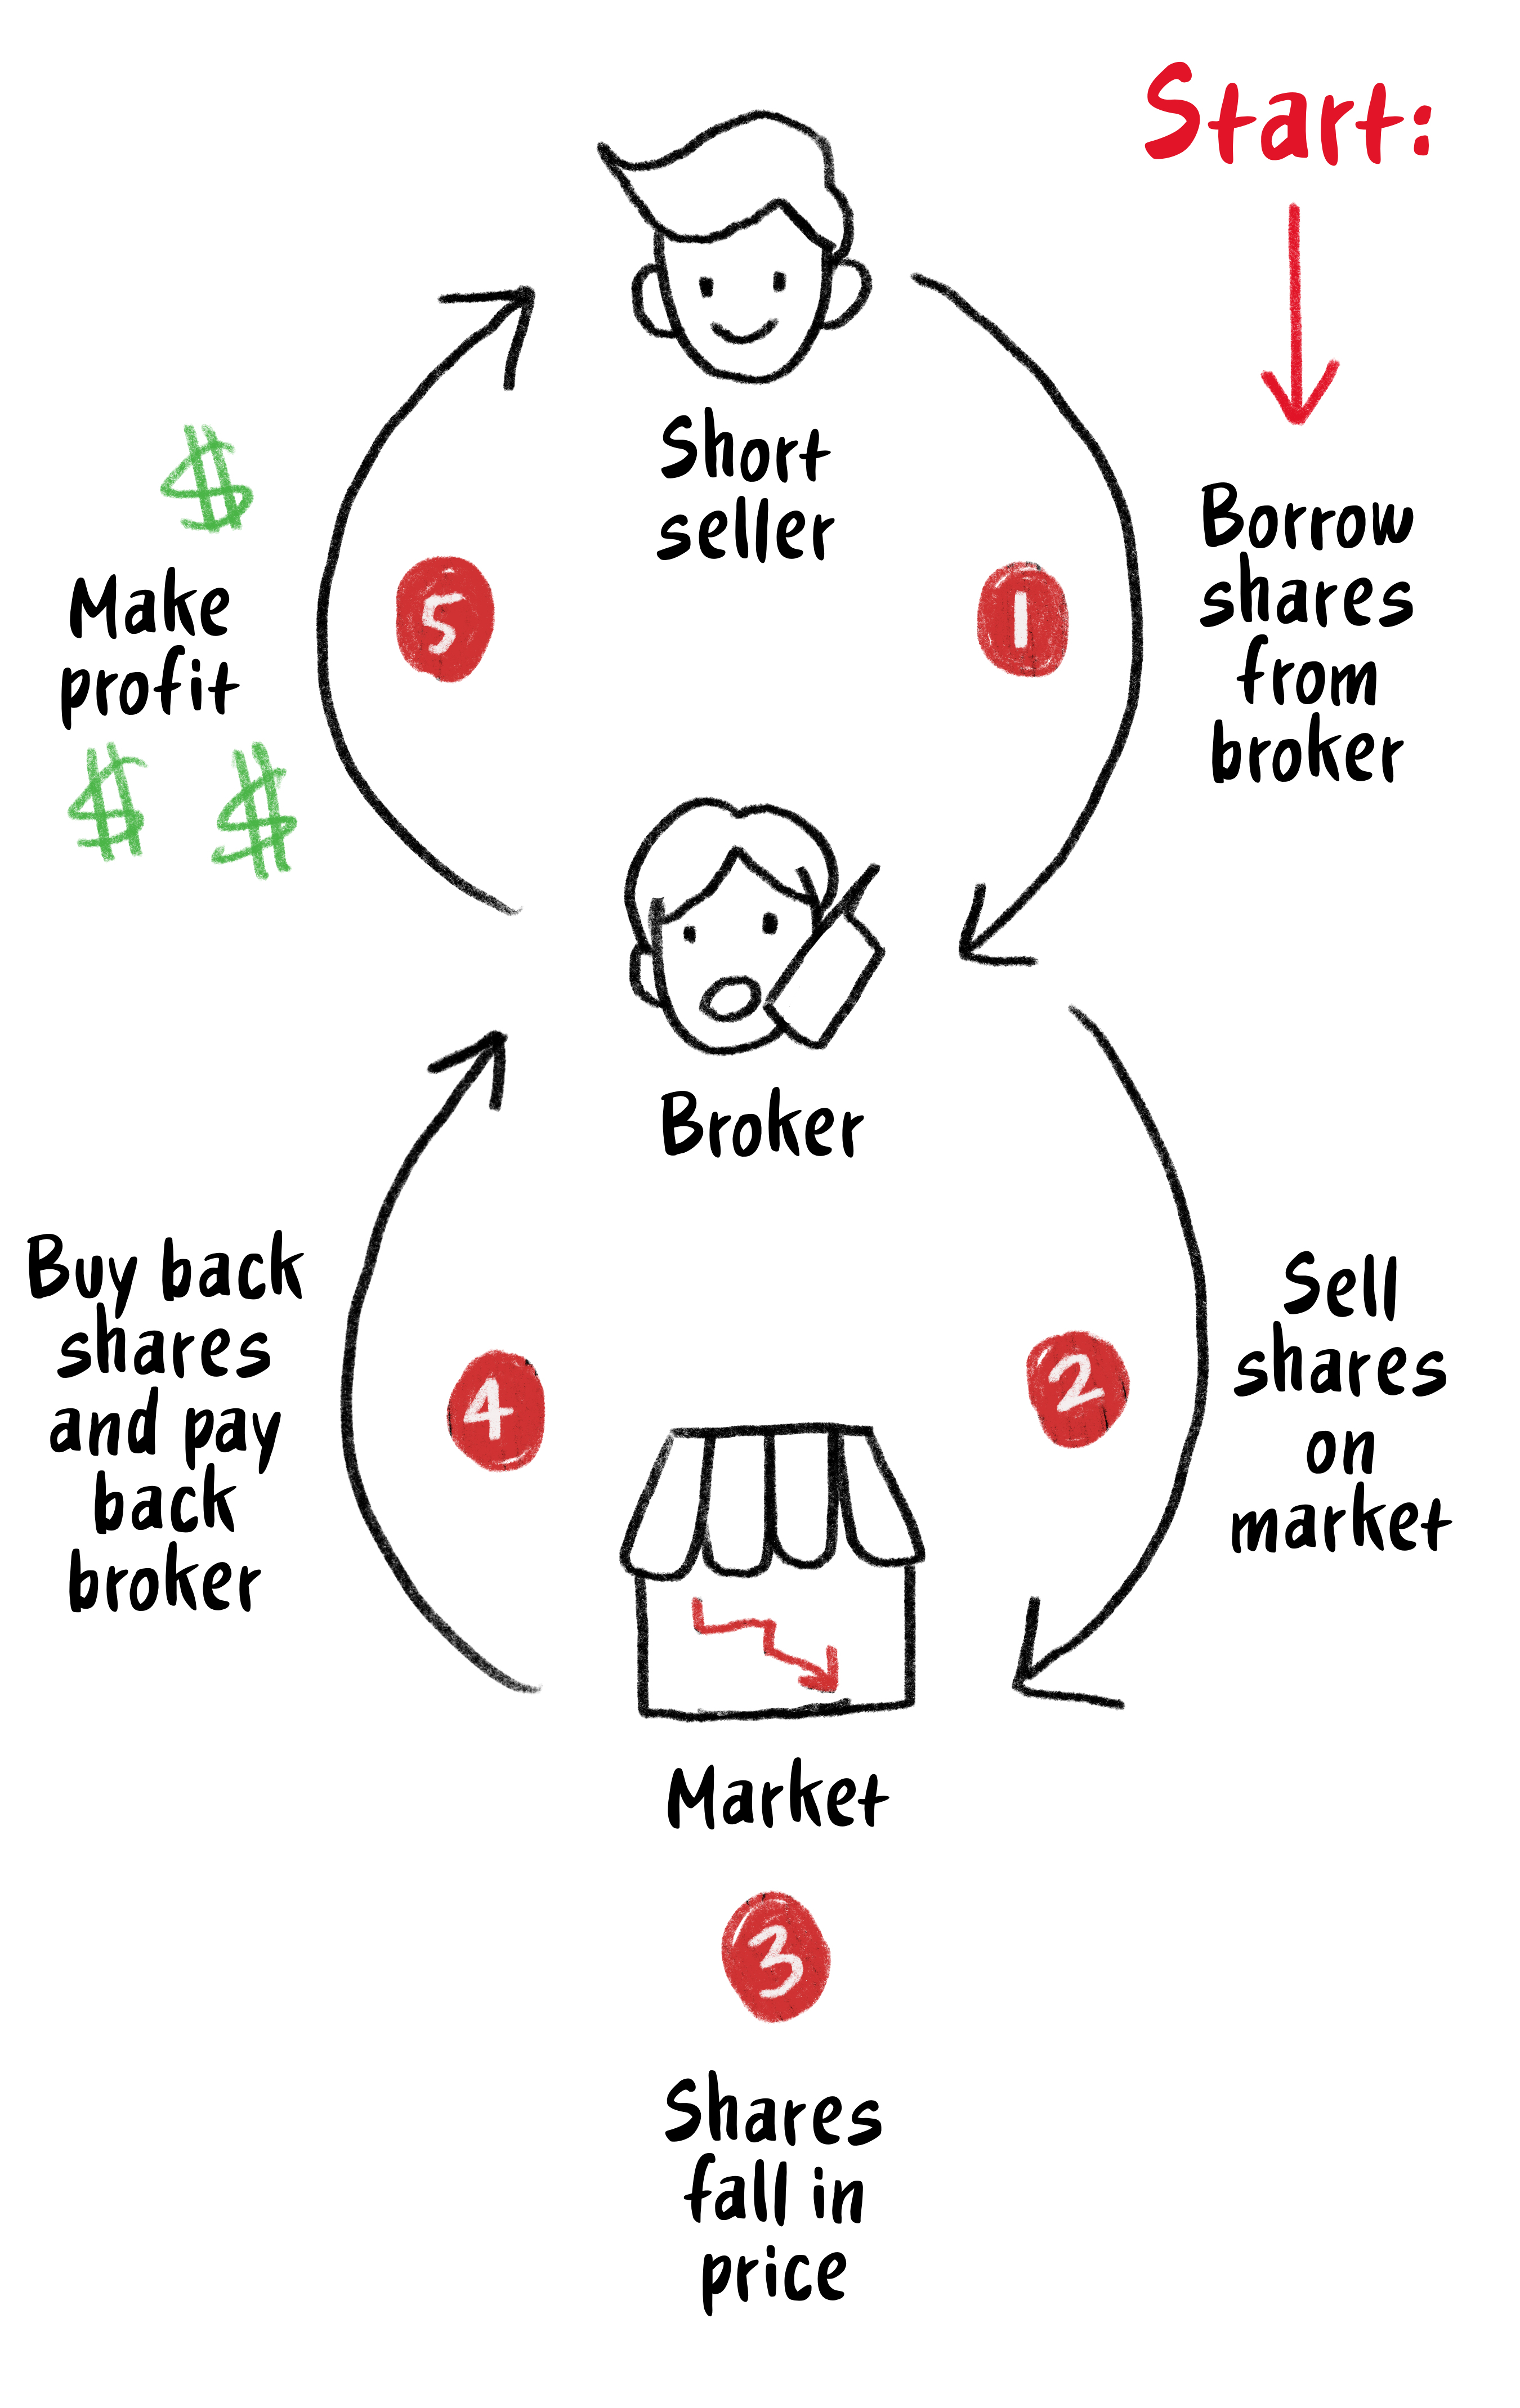
Margin spot shorting looks similar from the outside — you still profit if BTC falls — but the internal mechanics are very different. Instead of entering a derivatives contract, you are borrowing actual Bitcoin, selling it, and later buying it back to repay the loan.
Borrowing Bitcoin Against Collateral
A spot short on a crypto exchange follows a loan-and-sale lifecycle:
- Post collateral — deposit cash, stablecoins, or another eligible asset into your margin account.
- Borrow BTC — request a loan of Bitcoin from the exchange’s lending pool.
- Sell the borrowed BTC on spot — this creates the short exposure.
- Hold the proceeds — the cash from the sale sits in your account.
- Monitor the position — track price movement, interest accrual, and collateral value.
- Buy BTC back — when closing, purchase BTC on spot.
- Repay principal + interest — return the borrowed BTC plus any accrued borrow fee.
- Confirm the loan is cleared — make sure the borrowed balance is zero.
The key distinction from futures is that this position is created by a loan + spot sale, not a derivatives contract. There is no mark price, no funding rate, and no contract to settle. There is only a liability — the borrowed BTC — and collateral that must remain sufficient against it.
On the margin dashboard, three figures matter most:
- Borrowed amount (BTC) — the Bitcoin you owe the exchange.
- Loan-to-value (LTV) / margin level / collateral ratio — the relationship between collateral value and what you owe.
- Equity — your net value after accounting for the current cost of buying back the borrowed BTC.
For example, suppose you deposit $10,000 in collateral, borrow 0.2 BTC, and sell it at $50,000, receiving $10,000 in proceeds. If BTC climbs to $60,000, buying back 0.2 BTC now costs $12,000. That $2,000 paper loss eats directly into your equity and pushes your margin level/collateral ratio toward a margin call threshold.
At that point, you generally have three choices:
- Add more collateral.
- Partially buy back BTC to shrink the loan.
- Close the position before the exchange forces liquidation.
Exact liquidation math varies by platform, so treat this as directional rather than formulaic.
Closing a spot short is not merely placing a buy order. It is buying BTC on spot and then repaying the loan. One operational mistake is buying back the BTC but leaving the loan outstanding. The position may look closed, but interest continues accruing until the borrowed amount is actually repaid.
Interest Rates and Borrow Availability
Borrow cost mechanics are simple in structure: interest accrues on the BTC you borrowed, and the total carrying cost depends on rate × time × borrowed size. In practice, the rates are often variable, so what you pay today may not be what you owe next week.
Borrow availability constraints matter just as much. Opening or maintaining a short depends on whether BTC is available to borrow on that exchange. When lending supply tightens, you may see:
- Higher borrow fees.
- Lower maximum borrowable amounts.
- Inability to increase or roll the position.
Therefore, before opening a borrow-based short, check:
- What is the current borrow rate?
- Is the rate fixed or variable?
- What is the maximum BTC you can borrow against your collateral?
- Is interest charged hourly, daily, or on another cycle?
- Where can you check borrow utilization or availability?
- Does the platform notify you if rates change?
The gotcha is time-based interest drag. Even if price moves in your favor, borrow fees can quietly erode gains the longer the position stays open. As a rule, the longer you hold a margin spot short, the more the borrow rate matters relative to the expected price move.
BTC Put Options
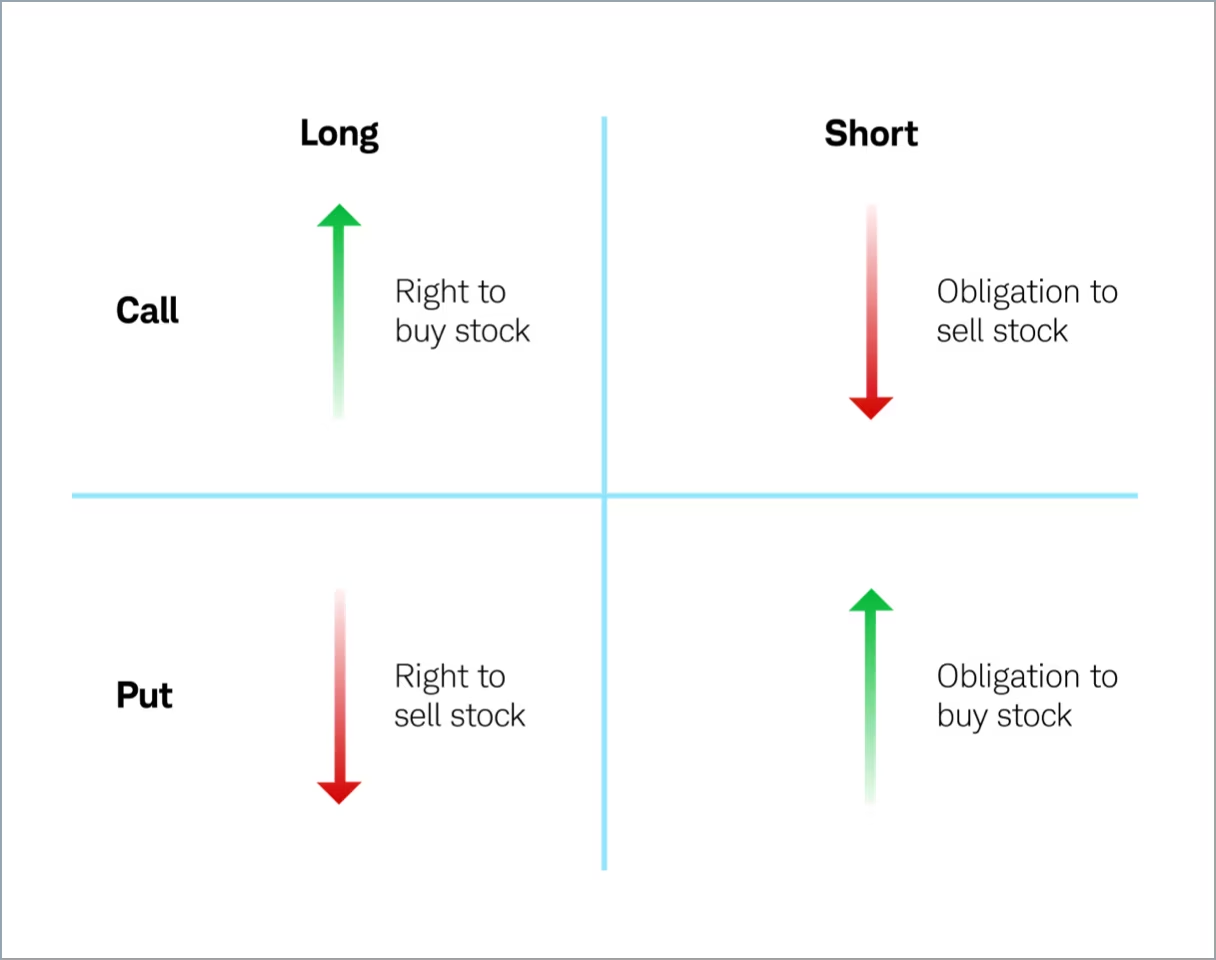
Going long (think buying) on a put option gives the right — but not the obligation — to sell Bitcoin at a predetermined price before or at a set expiration date. Instead of borrowing coins or opening a leveraged derivatives position, you pay an upfront premium for bearish exposure.
This structure caps your maximum loss at the fee paid, which is why puts are often the cleaner instrument for traders who want downside exposure without liquidation risk.
Strike Prices and Expiration Dates
Choosing a put is really two linked decisions:
- Strike price — how far below or above spot the contract sits.
- Expiration date — how much time the trade has to work.
If your thesis is a sharp, near-term drop, shorter-dated expirations can make sense. They are cheaper in absolute premium terms and provide leveraged exposure to a fast move. The tradeoff is time-decay sensitivity. If the move does not happen quickly, the option can lose value even if your broader view is eventually correct.
If your thesis is a slow grind down, longer-dated expirations are usually the better fit. You pay more upfront because you are buying more time value, but the position is less punished by short-term noise or a delayed move.
A simple example anchors strike selection. Suppose Bitcoin is trading at $60,000:
- A $60,000 strike put is at-the-money (ATM).
- A $50,000 strike put is out-of-the-money (OTM).
- A $70,000 strike put is in-the-money (ITM).
In short, moneyness describes where the strike sits relative to spot. That relationship directly affects both the cost of the option and the probability that it finishes profitable.
One practical note: many crypto options are effectively treated as European-style, meaning they can only be exercised at expiration rather than at any point beforehand. In practice, many traders do not plan to exercise the put at all. They manage the position by selling the option back into the market before or at expiry.
Premiums and Maximum Loss
The premium is both your cost of entry and your ceiling on risk. Because a put option has no margin call or liquidation mechanism, the payoff structure is cleaner than futures or margin spot shorting.
The basic framework:
- Max loss = premium paid (+ fees).
- Breakeven at expiry ≈ strike − premium.
- Profit increases as BTC falls further below the breakeven level.
- Before expiry, the option’s market price also reflects time value and implied volatility.
For example, suppose BTC is at $60,000, and you buy a $55,000 strike put for a $2,000 premium.
- If BTC settles at $48,000 at expiry, intrinsic value = $55,000 − $48,000 = $7,000. Net P&L = $7,000 − $2,000 = +$5,000 profit.
- If BTC settles at $57,000 at expiry, the put expires out-of-the-money. Intrinsic value = $0. Net P&L = −$2,000, the full premium lost.
Before expiry, the same put can trade above or below what simple strike-minus-spot math would suggest because the market also prices in time remaining and expected volatility.

What moves a put’s price day to day?
- Underlying BTC price — the direct driver.
- Time to expiration (theta) — time decay accelerates as expiry approaches.
- Implied volatility — higher expected volatility inflates premiums.
- Bid/ask spread — the gap between buying and selling prices eats into realized returns.
One execution pitfall deserves emphasis: thinly traded strikes and far-dated expirations can have wide bid/ask spreads. Before entering a put trade, check the spread and available liquidity at your target strike. Favor limit orders over market orders when entering or exiting.
Inverse Bitcoin ETFs
In contrast to regular spot Bitcoin ETFs, an inverse Bitcoin ETF gives bearish exposure through a standard securities account rather than a crypto derivatives venue. The trade is easier to access for many investors, but the return path is not the same as simply shorting spot BTC.
BITI and Daily Inverse Exposure
The ProShares Short Bitcoin Strategy ETF (BITI) trades through a standard stock brokerage account. No crypto wallet, derivatives exchange, or margin loan is required for the ETF share purchase itself.
What BITI delivers is inverse daily exposure to the performance of Bitcoin futures contracts, not spot Bitcoin itself. The target is the opposite of the underlying index’s 1-day move, and the fund must rebalance daily to maintain that exposure.
That daily reset is the key. A multi-day inverse ETF position does not behave like a simple mirror image of Bitcoin’s cumulative move.
Consider a two-day example:
- Bitcoin futures rise 10% on day one.
- Bitcoin futures fall 10% on day two.
The underlying’s cumulative two-day return is close to −1%. A daily-reset inverse product compounds in the opposite direction each day: −10% on day one, then +10% on day two, also landing near −1% in this specific path. But change the sequence, increase the volatility, or extend the holding period, and the result can diverge materially. That divergence is the mechanical signature of daily compounding, not a flaw in the product.
BITI tends to fit a narrow set of intentions:
- Short-term downside bets — usually a day or two, not a multi-week thesis.
- Brokerage-only access — bearish exposure without opening a crypto derivatives or margin account.
- Avoiding liquidation mechanics — no margin call or forced close tied to the ETF share itself.
Operationally, BITI and a direct futures short require different management. With BITI, you buy and sell ETF shares during standard market hours. With futures or perpetuals, you monitor a live derivatives position around the clock, including liquidation price, margin levels, and funding.
The ETF trades like a security. The futures short behaves like a managed, time-sensitive obligation.
Tracking Error and Holding Periods
Tracking error is the gap between BITI’s realized return and the simple inverse of the underlying index’s 1-day move. Several factors contribute to it:
- Daily reset/compounding — multi-day results diverge from a static inverse position.
- Futures roll and basis effects — rolling expiring contracts into new ones can add cost or slippage.
- Fees — the expense ratio creates ongoing drag.
- Bid–ask spread — ETF trading spreads affect entry and exit.
- Volatility-induced path dependence — choppy price action amplifies the compounding gap.

Holding period is the deciding variable:
- Intraday/1-day: closest to the product’s intended design.
- Several days: daily resets begin compounding against intuition, especially in choppy markets.
- Weeks+: results can deviate widely from the simple “BTC down X%, ETF up X%” expectation.
Here is the deal, though: Bitcoin futures can move up 8% one day and down roughly 7.5% the next, repeating that pattern for a week while landing near flat cumulatively. An inverse daily product can still lose value over that period because volatility drag prevents the daily compounding from netting cleanly to zero.
The takeaway from this section: with inverse ETFs, direction matters, but holding period and realized volatility matter too.
Platform Access and Account Requirements
Before planning any short, see if you can actually open one. Access to futures, margin, derivative products, and inverse ETFs is gated by account type, verification level, product permissions, and jurisdiction.
CME and Crypto Derivatives Exchanges
Shorting Bitcoin through futures splits into two distinct access paths.
Regulated futures access through the Chicago Mercantile Exchange (CME) requires an account with a traditional futures broker (e.g. Interactive Brokers). CME-listed Bitcoin futures fall under oversight frameworks that include the CFTC. Approval usually requires futures trading permissions, broker margin approval, and identity verification consistent with regulated securities or derivatives accounts.
Crypto-native derivatives exchanges offer perpetual swaps and futures directly through the exchange. Onboarding usually depends on tiered identity verification, basic versus enhanced KYC, and jurisdiction eligibility.
If you are comparing offshore or crypto-native venues, eligibility can differ sharply between large exchanges. Binance, for example, may offer derivatives functionality in some jurisdictions while restricting it in others. Always confirm product permissions and location-based eligibility before building a plan around any single platform.
Before funding either type of account, verify whether:
- your country or state is permitted on that exchange or broker.
- futures or perpetual products are enabled for your account tier.
- leverage or margin trading requires a separate opt-in.
- the venue supports relevant fiat on/off-ramps.
- your identity verification level is sufficient for derivatives access.
Kraken and Margin Platforms
On Kraken and similar margin-enabled platforms, creating and funding an account does not automatically mean you can short. There is often a separate activation layer between “having an account” and “placing a margin trade.”
Look for:
- Margin trading enablement.
- Borrow or lending agreements.
- A visible margin level or collateral ratio.
- Short risk disclosures or quizzes.
- Eligible collateral requirements.
If you cannot find the borrow or short button, check three things first:
- identity verification is fully complete.
- you accepted the platform’s margin terms or risk disclosures.
- you hold eligible collateral assets.
A funded account with the wrong asset type may still be unable to borrow.
Coinbase and Coinbase Advanced
Coinbase draws a meaningful line between its basic app and Coinbase Advanced. The standard app is generally built around spot buying and selling, with limited order types and no built-in path to margin trading or derivative products.
The advanced interface typically offers more sophisticated order types and, depending on region and eligibility, access to additional products beyond simple spot trades. However, availability varies by jurisdiction and account standing.
To check your eligibility:
- Review account settings or permissions for margin or derivatives-related toggles.
- Confirm whether margin or derivatives products are supported in your region.
- Check your verification tier.
- Look for required disclosures or agreements.
- Confirm your funding method is compatible with the product you want to use.
Do not assume a feature is available everywhere just because it appears in general marketing or help documentation.
Robinhood Limitations
Interestingly enough, Robinhood is a useful example of a retail app where buying and selling Bitcoin is simple, but opening an actual short is not possible. You can purchase BTC and sell what you hold, but the app does not support borrowing Bitcoin to short, nor does it offer crypto perpetuals or futures contracts.
This is a hard access constraint, not merely a risk-based limitation. Users on this type of platform need another route for short exposure, such as put options or inverse ETFs.
A common misconception: selling Bitcoin you already own is not the same as shorting it. A short requires either borrowing the asset to sell or entering a derivative contract that profits from a price decline. Simply selling what you hold only returns you to cash.
Brokerage Access for Inverse ETFs
Since inverse Bitcoin ETFs like BITI trade as standard securities, access runs through a stock brokerage rather than a crypto platform. However, access is not always automatic.
Confirm:
- Your account type permits trading US-listed ETFs.
- The ticker is actually available in your broker’s catalog.
- Your account is not restricted by retirement, custodial, or regional rules.
- The broker does not require an extra suitability acknowledgment for inverse products.
- You understand that trading is bound by market hours, unlike 24/7 crypto derivatives.
One more practical check: availability of specific US-listed inverse Bitcoin ETFs can vary by country and broker. Search your broker’s ticker lookup directly before treating this route as your fallback option.
Short Bitcoin Trade Setup and Order Management
Once the instrument is chosen, the next task is turning the idea into a repeatable trade plan. That means defining position size, invalidation, entry, stop-loss, take-profit, and execution method before the trade goes live.
Collateral and Position Sizing
Regardless of method, position sizing starts with three inputs:
- Account equity — total capital you are working with.
- Max loss per trade — often expressed as a percentage of equity, commonly 1–2%.
- Invalidation level — the price at which your short thesis is wrong.
The sizing logic can be expressed in one line: Position size ≈ risk $ / stop distance $ per BTC
This is not a leverage calculation. It is a risk calculation.
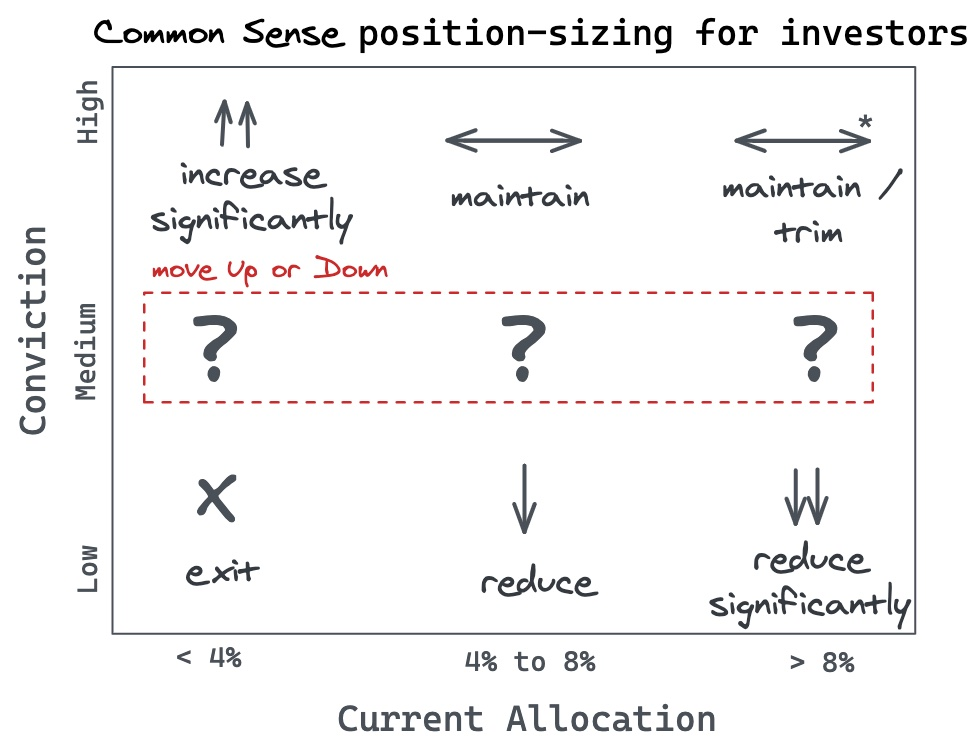
How that formula gets constrained depends on the instrument:
- Futures/perps: size must leave a liquidation buffer beyond the raw risk calculation.
- Margin spot short: size is capped by borrow availability and collateral ratio.
- Puts: the premium is the position size, since max loss equals premium paid.
- Inverse ETF: sizing is share count, but tracking and holding-period effects still matter.
For example, suppose your account equity is $20,000, and you risk 1% per trade, or $200. You plan to short Bitcoin at $65,000, with a stop-loss 2% above entry at $66,300. The stop distance is $1,300 per BTC. The calculation is: $200 / $1,300 ≈ 0.154 BTC
Notice that leverage does not appear in the formula. Leverage and liquidation price are instrument-specific mechanics. The position size calculation only translates a defined dollar risk into BTC exposure.
One operational rule applies across every method: do not allocate 100% of available collateral or margin to a single short. Keep unused headroom so fees, interest, funding payments, or routine volatility do not force an unplanned close.
Entry, Stop-Loss, and Take-Profit Orders
Every titular order type serves a specific purpose. Mixing them up is one of the cleaner ways to turn a sound thesis into poor execution.
- Limit order vs. market order (entry): a limit order controls price; a market order prioritizes immediate execution. Use limit orders when you can wait for a specific level. Use market orders only when execution certainty matters more than price precision.
- Stop-market vs. stop-limit (stop-loss): a stop-market order prioritizes getting out; a stop-limit order prioritizes price control. The gotcha is that a stop-limit can fail to fill during a fast squeeze.
- Take-profit limit order: this locks in a predefined favorable exit. The risk is that price approaches the level, reverses, and never fills the order.
Once your entry fills, place stop-loss and take-profit orders immediately. Ideally, use linked or conditional orders so one fill cancels the other. If the platform does not support linked orders, set them manually. On derivatives venues, mark both as Reduce-Only so they can only close or reduce the position.
Example:
- You short Bitcoin at $65,000.
- You place a stop-loss at $66,300.
- You place a take-profit at $61,500.
If price rises and hits the stop, the position closes near $66,300. If price falls and hits the target, the position closes near $61,500. If price chops between the two, both orders remain unfilled and the trade stays open.
Before placing an entry, check three microstructure signals:
- Order book depth — how much size sits near the current price.
- Spread — the gap between best bid and best ask.
- Slippage — the difference between expected and actual execution price.
When spreads are wide or the book is shallow, reduce position size, prefer limit orders, and assume stop-loss execution may be worse than expected.
Bitcoin Shorting Costs and Risk Management
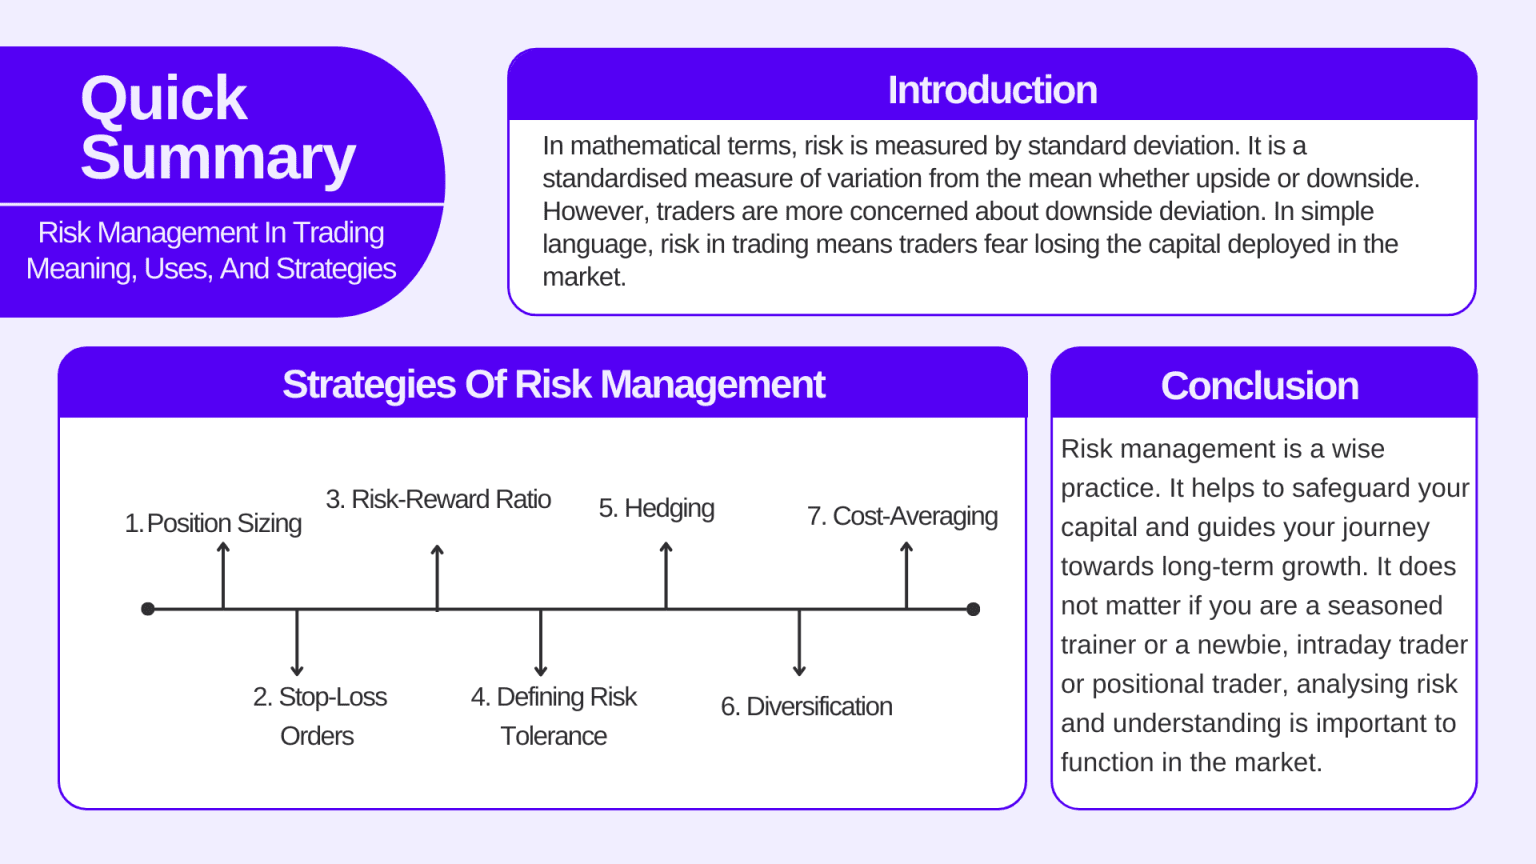
Every method of shorting Bitcoin has its own cost structure. Some costs are obvious, like option premiums. Others are quieter, like funding rates, borrow fees, spreads, slippage, and ETF tracking drag.
Funding Rates, Borrow Rates, and Spreads
Mapped by instrument, the ongoing cost driver changes sharply:
- Perps/futures: the main recurring cost is the funding rate, along with trading fees and liquidation risk.
- Margin spot short: the dominant cost is the borrow fee on borrowed BTC.
- Puts: the cost is time decay and changes in implied volatility.
- Inverse ETF: cost comes from expense ratio, roll effects, rebalancing drag, and spread.
A funding rate is a periodic payment exchanged between long and short holders on a perpetual swap. It exists to pull the contract price back toward spot levels.
The important detail: funding can flip sign. Holding a short does not guarantee you collect funding. When the market leans heavily short, funding can turn negative, meaning shorts pay longs.
A simple example: on a $10,000 notional short, a funding rate of 0.01% paid three times a day equals $3 daily. That sounds small, but over a month it becomes roughly $90 — deducted regardless of whether BTC has moved.
Spread cost is also easy to underestimate because it hits twice: once on entry and again on exit. It also tends to widen during volatility, precisely when shorts are most likely to be under pressure.
Hidden costs include:
- Maker/taker fees — market orders usually pay the higher taker fee, while resting limit orders may qualify for a lower maker fee or even rebate.
- Slippage on market orders — especially during fast moves or thin liquidity.
- Roll/close-and-reopen friction — switching futures expiries or moving between instruments means paying spread and fees again.
Mitigation is practical rather than theoretical: use limit orders when liquidity allows, break large orders into smaller clips, and plan rolls during normal liquidity hours.
Liquidation Costs and Margin Calls
Ideally, before you even dip your toes into margin trading, you should know about a margin call — a warning state. It occurs when your margin level has fallen below a maintenance threshold, and the exchange expects you to add collateral or reduce exposure.
Should you fail to deal with it, liquidation is the platform forcibly closing your position without further input from you. It is triggered when the mark price crosses your liquidation threshold.
A margin call gives you time to act. Liquidation means the platform has already acted. Unsurprisingly, liquidation is usually costlier than a planned stop-loss because of three factors:
- Forced market execution — the risk engine is not optimizing for your fill.
- Slippage — forced orders can sweep through thin liquidity.
- Fees — liquidation may carry a penalty fee on top of standard trading costs.
A numerical stress test isolates cost drag from price movement. Suppose you hold a $25,000 notional short backed by $5,000 margin, and BTC stays essentially flat for ten days. If funding averages 0.02% per 8-hour period paid by shorts, that is roughly $15 per day in funding, plus ordinary trading fees on adjustments. Over ten days, $150–200 can disappear from margin even though BTC barely moved.
The solution is not complicated: keep a larger buffer above maintenance margin than feels necessary.
Short Squeezes and Unlimited Loss Potential
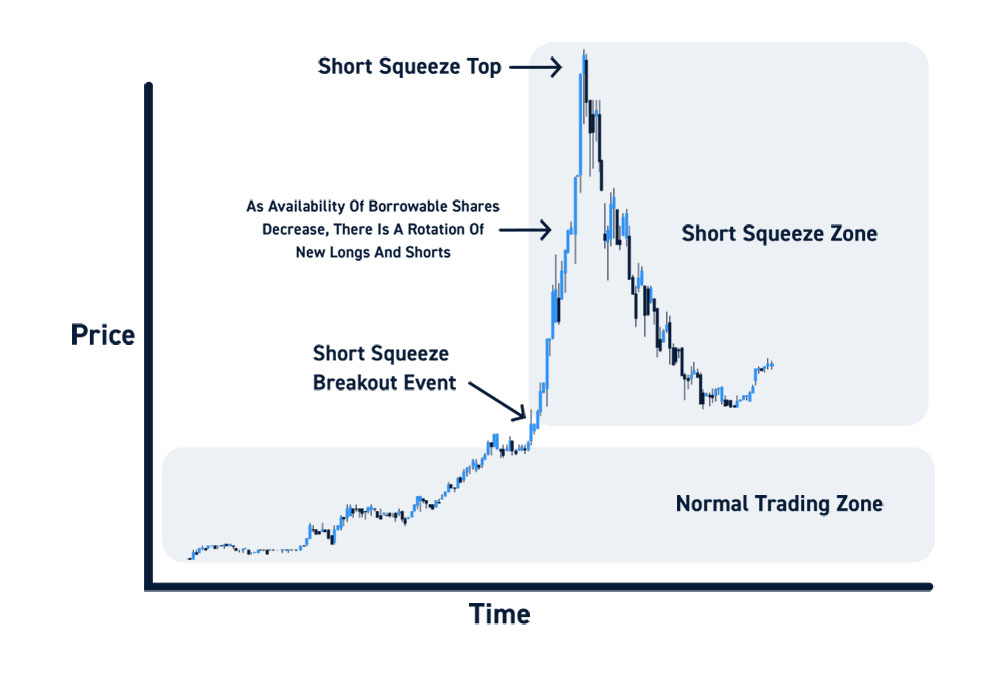
Short squeezes can be sharper in crypto because liquidity is uneven across a 24/7 trading cycle. Thin off-peak windows mean less depth to absorb forced buying. When liquidations begin, the resulting market buy orders can reprice the asset quickly, triggering the next tier of leveraged shorts.
On the dashboard, a squeeze has a recognizable signature:
- Mark price and last price begin diverging.
- The order book thins.
- Bid/ask spreads widen.
- The liquidation price moves closer to the current price.
- Exit orders become more expensive to execute.
Another thing to know about the instruments that enable shorting is loss shape is not the same across them all:
- Puts: loss is capped at the premium paid.
- Inverse ETF: loss is capped at capital invested in shares, although returns can diverge from simple inverse expectations.
- Futures or margin shorts: loss has no clean ceiling in the same way; adverse movement can escalate quickly and realize through forced liquidation.
A major, although not the main, risk of short-selling is that you are betting against the upside, which is unlimited on paper. When you go long, at least the maximum loss is limited to zero. It is not very likely that BTC can shoot up to infinity sooner than you can react but theoretically, this risk is present for this mode of trading.
You cannot always safeguard your positions against cascading events like short squeeze but you can mitigate its impact by:
- Maintaining a margin buffer well above maintenance requirements.
- Pre-placing Reduce-Only exit orders where available.
- Not sizing the position assuming a perfect exit fill.
- Accounting for spread widening under stress.
- Deciding in advance whether you will add collateral or cut exposure near a margin threshold.
Conclusion
Shorting Bitcoin in 2026 is not one strategy but a set of instruments with different failure modes. Futures and perpetual contracts provide direct bearish exposure but require active margin, liquidation, and funding management. Margin spot shorts use a more literal loan-and-sale structure, where borrow costs and collateral ratios define the trade. Put options cap risk at the premium paid, while inverse Bitcoin ETFs simplify access at the cost of daily reset and tracking behavior.
At the end of the day, the question is not only whether Bitcoin will fall. It is whether the instrument you choose matches your time horizon, account access, risk tolerance, and ability to manage the trade under stress. If you’re also planning exits on spot holdings, review when to sell your Bitcoin alongside your hedge timing.
Did you find our guide useful to learn how to short sell crypto? Feel free to share what you think on our Telegram, X (Twitter), and Facebook. While you’re at it, follow us so as not to miss out on any updates and content! For even more guides for exploring the crypto world, take a tour around the ChangeHero blog.
Frequently Asked Questions
Can beginners short Bitcoin safely?
It depends on what “safely” means. Beginners can access some shorting methods, but can and should are different questions.
Risk-bounded tools are the more prudent starting point: buying put options or using an inverse ETF. Both cap loss to a known amount — the premium paid or the capital invested in shares. Leveraged futures and margin-based short selling introduce liquidation and margin-call failure modes that can close a position faster than a beginner may be prepared to manage.
Do you need to own Bitcoin to short it?
No. Owning BTC is not required for most shorting methods. Futures, perpetuals, and inverse ETFs create downside exposure synthetically. Spot-based short selling directly involves Bitcoin, but even there you borrow BTC to sell it, so you do not need to own it upfront.
Is shorting Bitcoin legal?
It depends on your jurisdiction and the product used. Regulated routes such as CME futures or US-listed inverse ETFs operate within established securities and derivatives frameworks. Offshore perpetual swap exchanges may be restricted or unavailable depending on your country or state.
In the US, derivatives market conduct and many futures products sit within frameworks that include the CFTC, while spot cryptocurrency trading rules can differ by venue and state. Before attempting any short, check your broker or exchange eligibility rules and your local regulations.
What is the safest way to short Bitcoin?
The safest structure is one with predefined maximum loss and no liquidation risk from leverage. Buying put options fits that definition: downside is capped at the premium paid, with no margin call or forced closure.
Inverse ETFs offer a simpler brokerage-access alternative for shorter time horizons, but their daily reset means returns can diverge from a straightforward inverse of Bitcoin’s price over multi-day holds.